
Company secretarial requirements Sri Lanka: the filing map
A private company map from incorporation to closure, with annual filings, ownership updates, event notices and their source rules.
On this page
Last verified against the primary sources on 4 November 2026.
Company secretarial requirements Sri Lanka, in brief. As at 4 November 2026, section 131 of the Companies Act requires a company to deliver an annual return at least once a year, except in its incorporation year. When an AGM is held, the return is completed within 30 working days and a signed copy forwarded forthwith. Beneficial ownership details accompany the return. Other events have separate deadlines. [1] [2] [3]
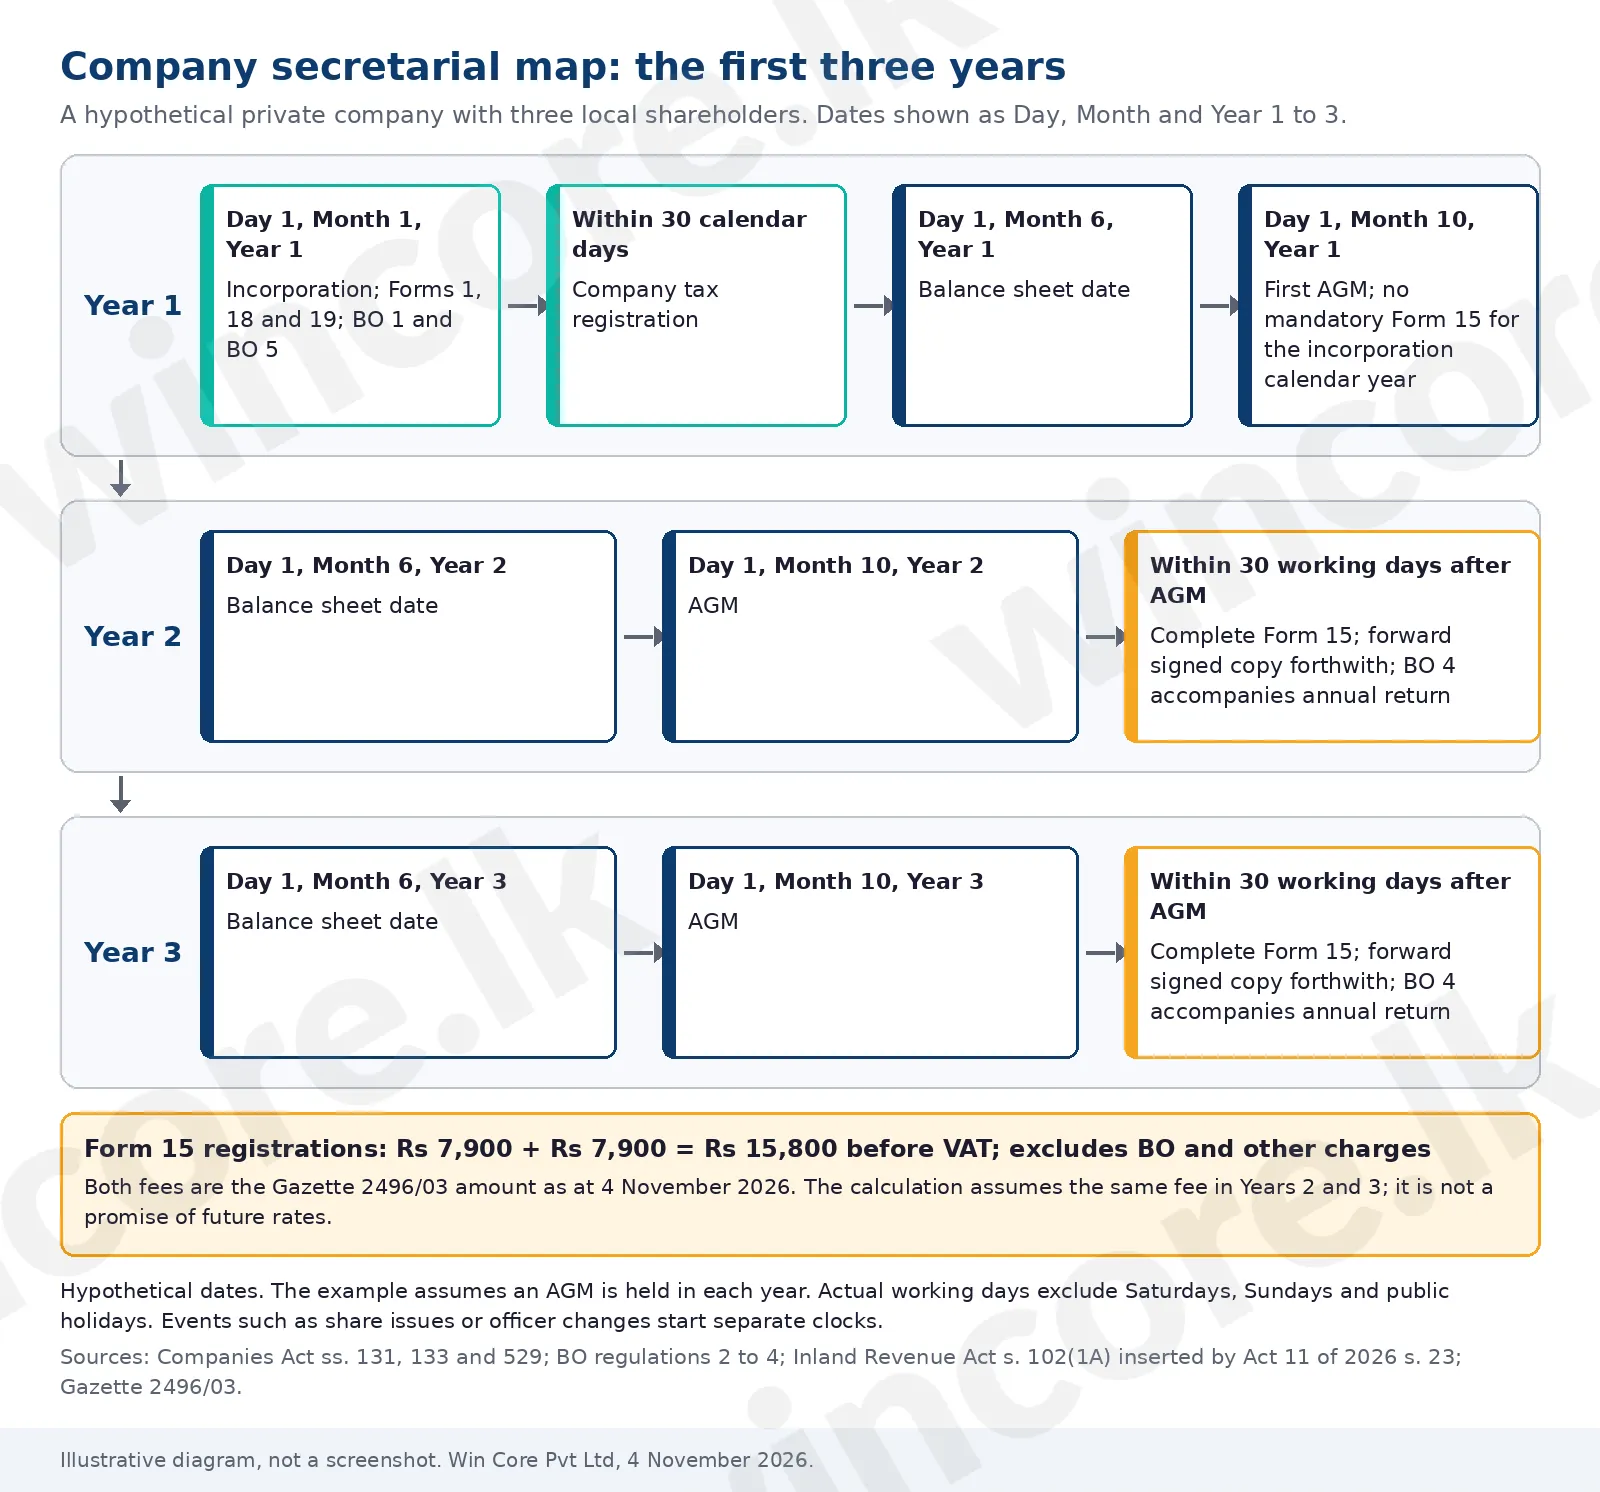
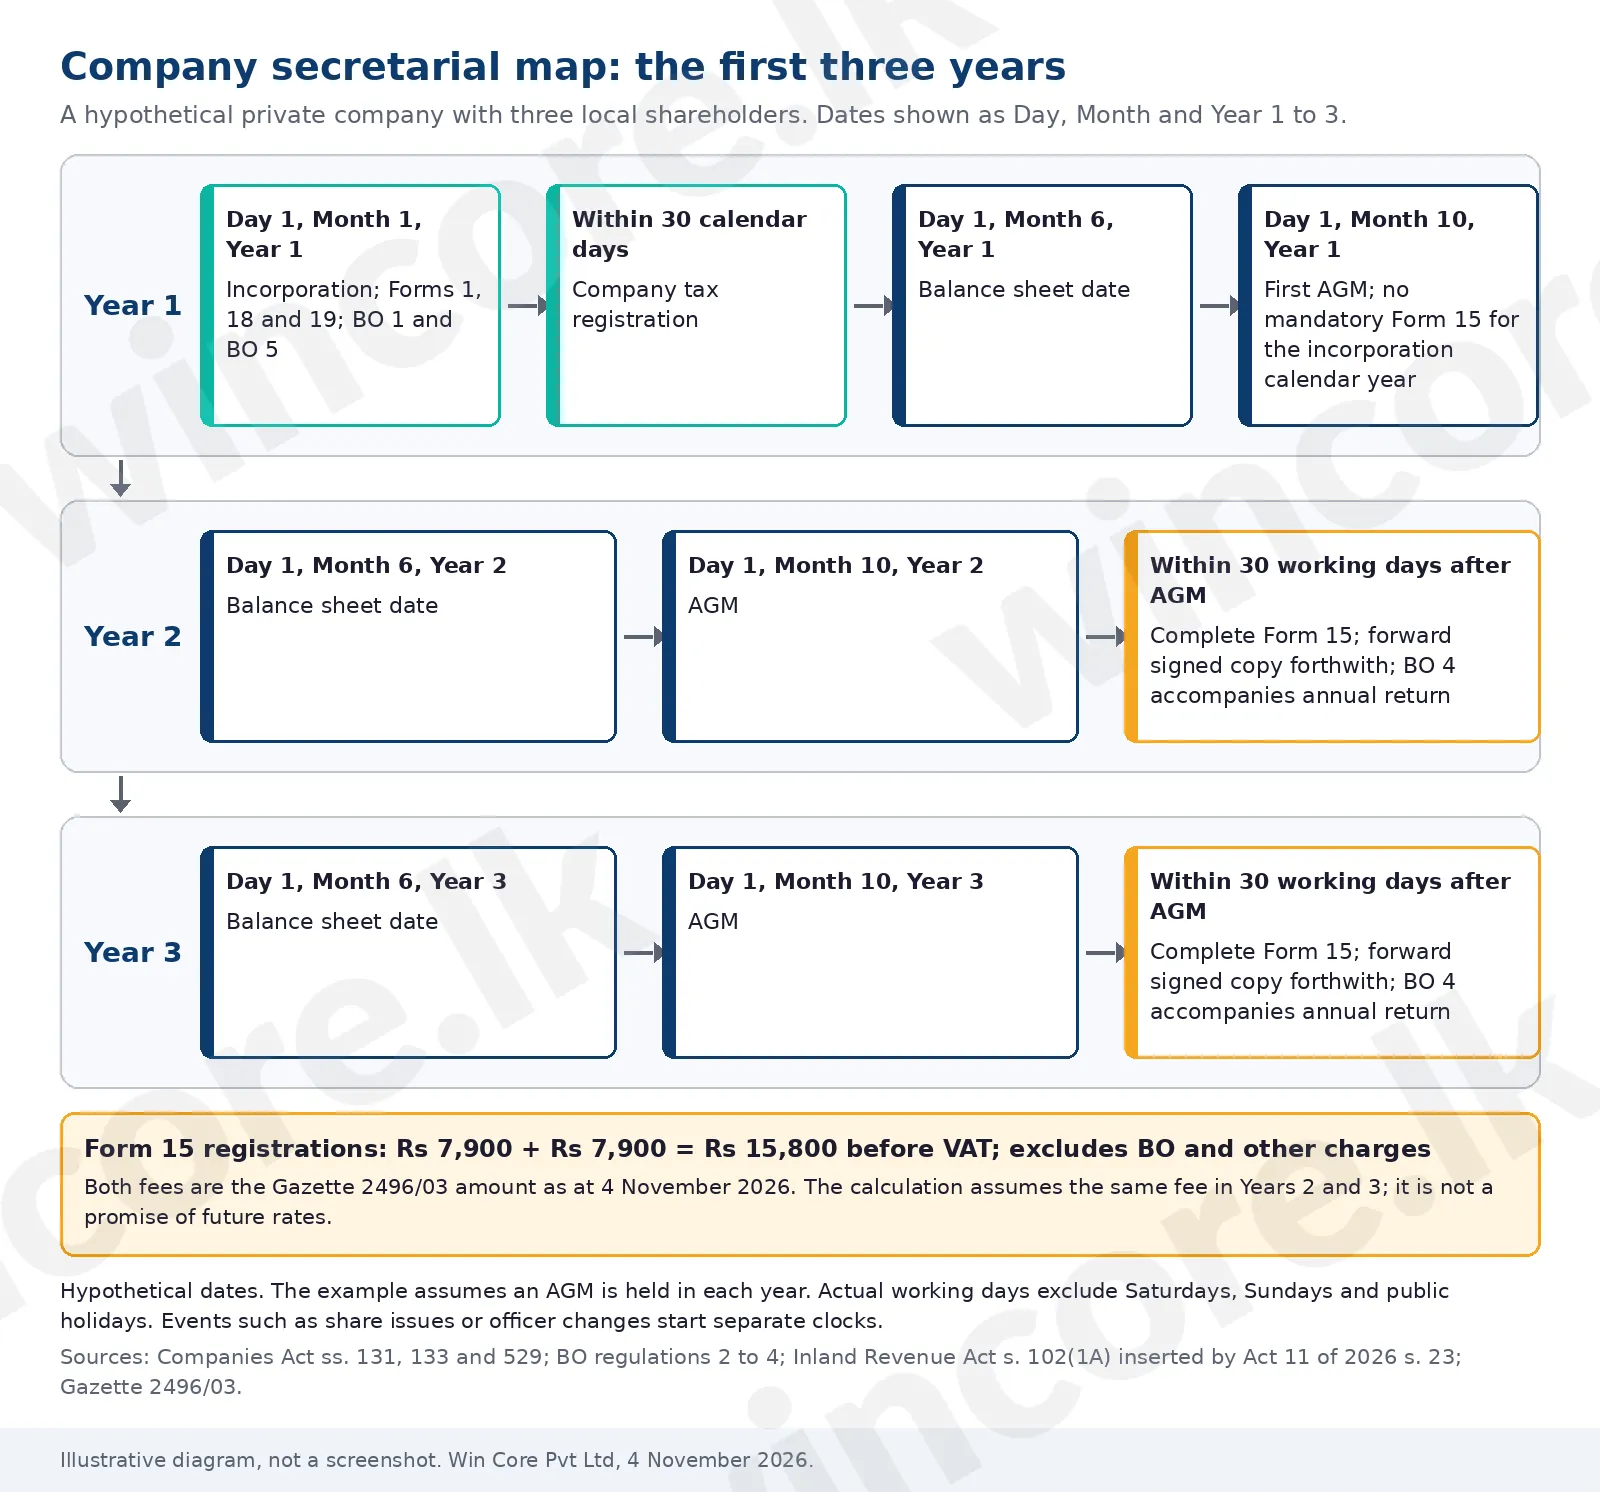
Take a hypothetical private company with three local shareholders. It holds its first annual meeting in its incorporation year, then one in each of the next two years. Using the Rs 7,900 per return fee in the schedule as at 4 November 2026, and assuming it stays unchanged, two later Form 15 registrations cost Rs 15,800 before VAT, excluding beneficial ownership charges and any other filing. [1] [4]
Company secretarial requirements Sri Lanka include annual and event filings
One clock follows the balance sheet date, AGM, annual return and beneficial ownership return. Another starts when something changes, such as a share issue or a new director. A dormant company should not assume inactivity stops the annual cycle. [1] [3]
For the Companies Act, a working day excludes Saturday, Sunday and a public holiday. Calendar days and months are different. The table identifies each trigger; statutory exceptions and extensions still apply. [1]
The illustration uses calendar years: incorporation on Day 1 of Month 1, balance sheet dates on Day 1 of Month 6, and AGMs on Day 1 of Month 10. Actual dates and holidays determine filing days. [1]
Incorporation starts the register and tax identification duties
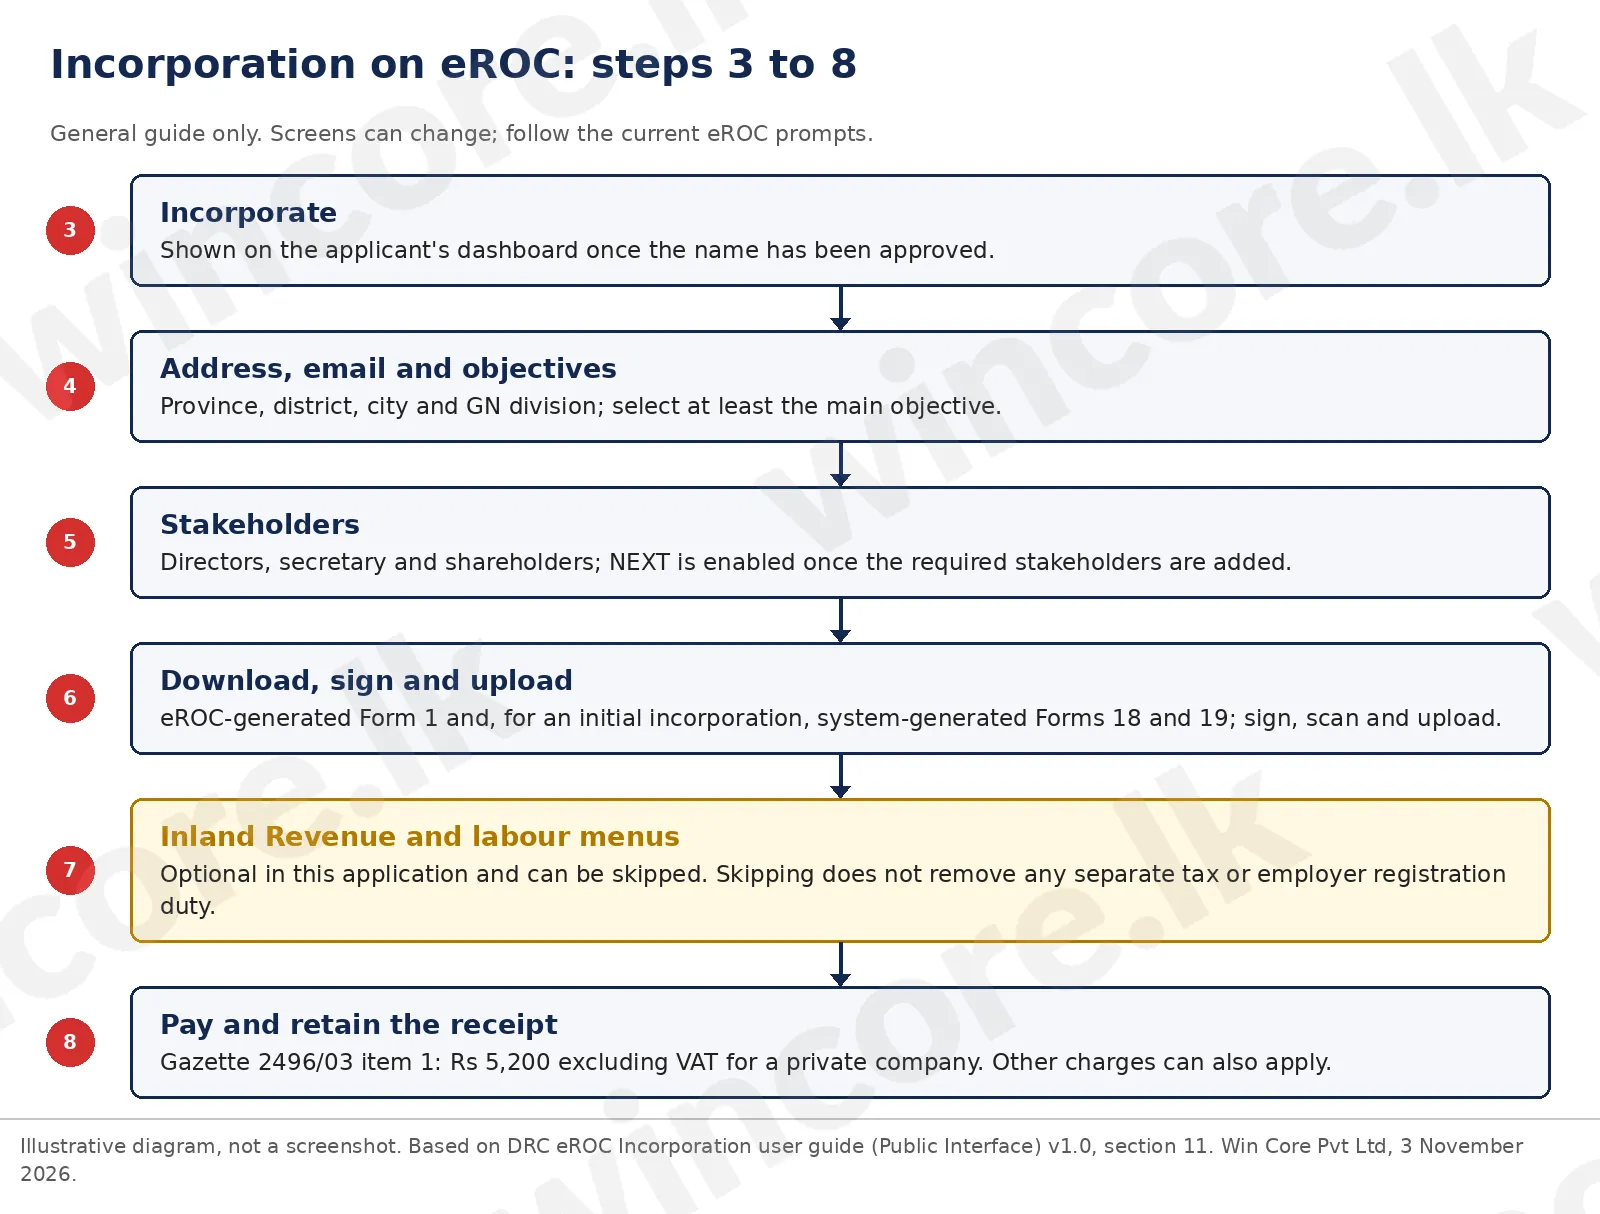
The incorporation application uses Form 1, director consent Form 18 and secretary consent Form 19. The articles and details of initial shareholders, directors and secretary belong in the incorporation record. BO 1 provides beneficial ownership details at incorporation and BO 5 identifies the authorised person. The authorised person is a natural person resident in Sri Lanka, responsible for safeguarding the beneficial ownership register and making it available to specified authorities. [1] [2] [3] [5]
The company must register with the Commissioner General of Inland Revenue no later than 30 days after incorporation or registration. This deadline uses calendar days. The company registration guide sets out the steps; the table separates government charges by transaction. [6]
Every company must have a secretary. Section 222 links prescribed secretary qualifications to a company's turnover or stated capital. Check the applicable qualification and registration rules when appointing a secretary. Keep a copy of the secretary's consent and the company's own appointment records. [1]
An annual meeting and Form 15 have separate rules
Subject to the first meeting rule and the written resolution route, the board calls an AGM in each calendar year, no later than six months after the balance sheet date and no later than 15 months after the previous AGM. A company need not hold its first AGM in its incorporation calendar year, but must hold that meeting within 18 months of incorporation. The written resolution route applies if everything required at the AGM is done by resolution under section 144, subject to the articles and statutory signature thresholds. Section 135 requires 15 working days' written AGM notice; shorter notice is valid if all shareholders entitled to attend and vote agree. [1]
Section 131 requires the return at least once in every year except the incorporation year. It says the return is to be completed within 30 working days from the AGM and a copy signed by a director and the secretary forwarded to the Registrar forthwith. BO 4 accompanies the annual return. On our reading, the annual return duty remains if a valid written resolution replaces the meeting, but the timing trigger in that case is unresolved. The same timing question arises when the first AGM has not yet been held. The 2014 replacement of section 132 also refers to a certificate under the earlier income tax law; its present operation is unresolved. [1] [2] [3] [12]
Keep the share register, directors and secretaries register, beneficial ownership register, accounting records, minutes and the other records required by section 116. A private company may dispense with an interests register by unanimous shareholder resolution under section 30. Records kept elsewhere and their movements can require separate notices. [1] [2]
Each event in the filing map has its own trigger
"WD" means working days. References are to the Companies Act unless another instrument is named. A dash means no amount or single deadline is stated here, not that a filing is free or optional. [1] [2] [3] [4] [5]
The fees in this table are the Gazette 2496/03 amounts as at 4 November 2026, excluding VAT; future rates may change. Item 7 sets Rs 2,600 for documents within its wording, subject to its exclusions. "Item 7*" means that general item may apply on our reading; the Gazette does not identify the individual form by number. A separate BO fee schedule has mismatches between some form numbers and descriptions, and does not list BO 8 separately. Check the applicable BO charge before payment. [3] [4] [10]
| Event or question | Form or action | Deadline and source | Gazette 2496/03 fee, excluding VAT | Guide |
|---|---|---|---|---|
| Choose a name | Name approval | Before incorporation, section 4 | Rs 2,600 approval | Name reservation; name check |
| Incorporate | Forms 1, 18 and 19; articles; BO 1 and BO 5 | At application or incorporation, section 4 and BO regulations 2 and 4 | Rs 5,200 private company registration; other charges may apply | Registration steps; first 90 days; registration costs |
| Initial capital | Share register and subscription records | Section 50; follow articles | - | Share capital |
| Company tax registration | Company TIN registration | Within 30 calendar days of incorporation, Inland Revenue Act section 102(1A) | - | First tax registration |
| First and later AGMs | Meeting, or qualifying written resolution | Section 133: first within 18 months; later limits above; section 144 exception | - | First AGM |
| Annual return | Form 15 and private company declarations | Once each year except incorporation year; complete within 30 WD of AGM and forward forthwith; timing without an AGM is unresolved, sections 131 and 132 | Rs 7,900 | Form 15; late returns |
| Annual BO information | BO 4 | With Form 15, section 130A(8), BO regulation 3 | BO schedule: see note | Annual BO 4 guide |
| Keep records | Share, officers, BO and other registers | Ongoing, sections 116, 123, 130A and 223 | - | Statutory registers; BO regulations |
| Record location changes | Form 14; BO 6 if the BO register moves | General records: 10 WD under section 116(4); BO 6 under BO regulation 5 | Item 7*; BO schedule: see note | Form 14; BO 6 |
| Accounting records kept elsewhere | Form 16 where applicable | Notify the Registrar within 10 WD of first keeping or moving records elsewhere, section 116(4); overseas location requires permission under section 149 | Item 7* | Form 16 |
| Change balance sheet date | Form 17 and applicable approval | Section 171; notice takes effect on receipt, with prior approval required in the case described in section 171(3) | Item 7* | Form 17; financial year end |
| Prepare financial statements and appoint auditor | Statements and auditor appointment | Financial statements: six months after balance sheet date, or Registrar extension, section 150; auditor appointment: sections 154 and 159 | - | Private company audit; filing financial statements |
| Annual report | Board report to shareholders | Six months after balance sheet date; send at least 15 WD before AGM, sections 166 to 168, subject to their provisos | - | Private company audit |
| Change auditor | Appointment and cessation documents; notice if applicable | Sections 154, 160 and 161; 20 WD notice to a qualified outgoing auditor in the replacement case under section 160 | - | Change auditor |
| Appoint or remove director | Form 20; Form 18 for an appointment | Appointment: 20 WD under section 223(3); notify a removal under section 223 and follow section 206 procedures | Item 7* | Appoint a director; remove a director |
| Director details or death | Form 20 | 20 WD after company first becomes aware of death or particulars change, section 223(3) | Item 7* | Change director details; sole director; resident director |
| Appoint or change secretary | Form 20; Form 19 for an appointment | 20 WD after appointment or resignation, section 223(3) | Item 7* | Choose a secretary; change secretary; outgoing secretary |
| Secretary registration | Secretary registration application | Qualification rules depend on circumstances, sections 221 to 222 and 2023 regulations | Individual registration Rs 6,600 | Secretary registration |
| Move registered office | Form 13 | Effective five WD after Registrar receives notice, or later specified date, section 114 | Item 7* | Registered office |
| Change name | Form 3; prior approval and special resolution | Notice within 10 WD of change, section 8; public notice within 20 WD, section 9(2) | Name approval Rs 2,600; item 7* for document | Change company name |
| Change articles | Form 39 and text of resolution and alterations | Within 10 WD, section 15(2) | Item 7* | Change articles; Form 39 |
| Other special resolution | Form 39 where required | Deadline depends on the specific statutory action | Item 7* | Board resolutions |
| Issue shares | Form 6 and BO 2 | 20 WD after issue, sections 51(4), 130A(1) and BO regulation 2(2) | Item 7*; BO schedule: see note | Issue shares; Form 6 |
| Transfer shares | Transfer instrument, register update, BO 3 | BO 3 within 20 WD of transfer, section 130A(1) and BO regulation 2(2) | BO schedule: see note | Private company share transfer |
| Shareholder dies | Legal representative's evidence and register update; BO form if a relevant change occurs | Sections 73 to 74 and 130A; the outcome depends on the transmission and articles | - | Death of a shareholder |
| Call on shares paid | Form 7 | 10 WD after call or obligation is performed, section 55 | Item 7* | Form 7 |
| Reduce stated capital | Form 8, and resolution | Section 59: public notice at least 60 days before resolution; notice of reduction within 10 WD; section 59(4) exception | Item 7* | Form 8 |
| Company acquires or redeems shares | Form 9 | Immediately after acquisition or redemption, section 63(4) | Item 7* | Form 9; redeemable preference shares |
| Register a qualifying charge | Form 10 and instrument | Instrument must be registered within 21 WD of execution in Sri Lanka, or within three months of execution outside Sri Lanka, section 102(3) | Rs 9,900 registration | Register a charge |
| Issue a secured debenture series | Form 10A and prescribed particulars | Deliver particulars within 15 WD of execution of the charge deed, or of a series debenture if there is no deed; further issues have separate particulars under section 102(7) | Rs 9,900 registration | Debenture series |
| Satisfy or release a charge | Form 12A and evidence | Section 107 permits the Registrar to record satisfaction when satisfied; no fixed period is stated in that section | Item 7* | Satisfaction of charge |
| BO particulars change | BO 8; section 130A notice where applicable | BO regulation 7: 14 WD after change; section 130A(7): 14 WD after receipt of details | BO schedule: see note | Change of beneficial owner |
| Authorised person changes | BO 5 | Subsequent change must be notified, section 130C(2) and BO regulation 4 | BO schedule: see note | Change authorised person |
| Existing company BO details | BO 7 where regulation 6 applies | Section 130H; check DRC notice for the extension | BO schedule: see note | BO system; ownership test; nominee ownership |
| View company or BO information | File search, certified copy or BO search | On request; public BO details limited by section 130D | File inspection Rs 1,300; company document certification Rs 1,300; BO fees separate | eROC file search; certified copies; verify a copy; BO search |
| Apply for strike-off | Strike-off application and evidence | Section 394 procedure; Registrar's Gazette notice gives three months in the case described in section 394(3) | - | Strike-off; closing routes |
| Restore a struck-off company | Court application and certified order | Apply before expiry of five years from the relevant Gazette notice, section 394(6), subject to the court's decision | - | Restoration after strike-off |
| Liquidation | See the 2026 Act | Section 1 of the 2026 Act sets the transition described below | - | Closing routes |
| Related events beyond the ordinary annual cycle | Amalgamation proposal, prior approval or court order | Specific transaction and order govern | - | Amalgamation; prior approval; court order filing |
| Using eROC | User account, company connection, payment, receipt or resubmission | Portal process, not an additional statutory deadline | - | User registration; connect a company; payment receipt; resubmission |
| Other registrations and entity types | Separate procedures, only if relevant | Not a general private company filing | - | Auditor registration; public contracts registration; prospectus registration; overseas company filings; guarantee company registration; society registration; trusts amendment bill |
| Company law and ownership context | Read alongside the specific transaction | Application depends on the event | - | 2025 company law changes; fees order; buying a company; director duties; shareholders' agreements |
The Registrar, rather than the company, gives the incorporation public notice under section 5(1)(d) as substituted in 2019. Do not confuse that with the company's separate public notice of a later name change. [7]
The company must allot shares within 20 working days after receiving consideration. The period does not apply to shares fully paid from reserves and issued to all shareholders of the same class in proportion to their holdings. The Form 6 and BO 2 clocks run from the issue, a different event. For a share transfer, the company also needs to apply the articles and the statutory transfer provisions. [1] [2] [3]
Beneficial ownership records need updates between annual returns
Annual BO 4 does not replace BO 2, BO 3 or BO 8 when their separate triggers occur. A shareholder must provide the details specified in section 130A(1) to the company within 10 working days of share subscription or transfer. The company then has its own notice obligations. Keep evidence of the change and receipt dates together. [2] [3]
For BO 8, regulation 7 measures 14 working days from the change. Section 130A(7) measures its notice period from receipt of details. On our reading, the two clocks must be considered separately. Record both dates and work to the earlier applicable deadline as a precaution, not a separate legal requirement. [2] [3]
For companies covered by the existing company rule, section 130H set a six month period from commencement of the amendment on 30 March 2026, ending on 30 September 2026. For the Department of the Registrar of Companies notice about an extended submission deadline, check the notice and its application to the company. This existing company rule is separate from the incorporation filing. [2] [8] [9]
For delay from 22 October 2026, the rule as at 4 November 2026 charges Rs 1,000 per week for a prescribed BO form filed late, with part of a week treated as a full week. Section 514 separately allows the Registrar, if the statutory conditions are met, to accept a sum in composition of an offence; that sum is discretionary, not a fixed second weekly charge. [1] [10]
Closure and liquidation follow different routes
Strike-off is not automatic merely because trading has stopped. Section 394 sets a notice process and allows an eligible company, shareholder or creditor to apply to court for restoration in the circumstances and period stated in subsection (6). Court dissolution relief under section 393 is a different remedy with its own conditions. [1]
For liquidation, the Rescue, Rehabilitation and Insolvency (Corporate and Personal) Act, No. 12 of 2026 was certified on 17 June 2026. Under section 1, its remaining provisions commence on 17 December 2026 unless the period is extended by Gazette order. On commencement, section 477 repeals Companies Act Part XII except sections 393, 394 and 395, and section 469 changes parts of section 394. Section 478 preserves the former law for specified pending insolvency proceedings. Check for an extension and the applicable transition. [11]
Worked example: two annual return fees total Rs 15,800 before VAT
The hypothetical company has three local shareholders. In Year 1, it incorporates in Month 1, closes its books in Month 6 and holds its first AGM in Month 10. Section 131 excludes the incorporation calendar year. [1]
In Year 2, it has a balance sheet date in Month 6 and holds the next AGM in Month 10. It completes Form 15 within 30 working days of that AGM, forwards the signed return forthwith and delivers BO 4 with it. It repeats that sequence in Year 3. The example assumes neither an AGM waiver nor an additional transaction. [1] [2] [3]
Using the fee in force as at 4 November 2026 and assuming it stays unchanged, two returns at Rs 7,900 each are Rs 7,900 + Rs 7,900 = Rs 15,800 before VAT. BO charges, other government charges and professional fees are outside this calculation. [4]
What this means for you
Put the incorporation date, balance sheet date and last AGM on a calendar. List changes to shares, people, addresses and charges with their trigger dates. Keep each signed form and acknowledgement with its resolution or evidence. Use the table to find the relevant rule and any exception.
Checklist: documents needed
- Certificate of incorporation, articles and company number
- AGM notices, minutes or qualifying written resolutions
- Signed annual return, BO submission and acknowledgements
- Share, directors, secretary and beneficial ownership registers
- Evidence and dates for share, officer, address and charge changes
FAQ
Does a private company file Form 15 in its incorporation year?
No. Section 131(3) excludes the incorporation calendar year. A first AGM may still be held in that year. From the following calendar year, consider the annual duty and AGM timing together. BO 4 accompanies an annual return when one is delivered. The dates of the first meeting and first return need not coincide. [1] [2] [3]
Is a beneficial ownership return needed after every share transfer?
BO 3 is required within 20 working days of a transfer under regulation 2(2). This is separate from BO 4, which accompanies the annual return. Keep the transfer documentation and share register. Record both the transfer date and when ownership details reach the company: the Act and regulations use event-specific clocks. The shareholder also has a separate obligation to provide details. [1] [2] [3]
Does a company stop filing if it has no trading income?
No general dormant-company exception to section 131 is stated in that section. A company still on the register should consider the annual return and meeting rules and applicable tax obligations. Strike-off is a separate section 394 process. Stopping trade alone does not dissolve a company or determine whether an application for removal will succeed. [1]
What is the deadline after a registered office move?
The change takes effect five working days after the Registrar receives the notice, or on the later date specified in it. Section 114 describes that effect; a board decision alone does not make the change effective. Form 13 is the DRC notice. A move of records may also trigger Form 14 or BO 6, with different applicable rules and deadlines. [1] [3] [5]
The short version
Start the company record at incorporation and keep the annual and event-driven dates separate. Form 15 and BO 4 belong together in the annual cycle. Share, officer, address and ownership changes can start other clocks. Keep the evidence with the filing.
Talk to us. For Annual Return Filing and Corporate Document Maintenance, see our company secretarial page or book a consultation at our contact page.
WinCore Pvt Ltd
This article is general information as at 4 November 2026 and is not tax, legal or accounting advice on your specific position.
References
- Parliament of Sri Lanka. Companies Act, No. 7 of 2007, sections 4, 8, 15, 30, 50 to 59, 63, 73 to 74, 102 to 108, 114, 116, 123, 131, 133, 135, 144, 148 to 150, 154, 159 to 161, 166 to 168, 171, 206, 221 to 223, 393 to 395, 514 and 529. https://www.parliament.lk/uploads/acts/gbills/english/3776.pdf . Primary. Accessed 4 November 2026.
- Parliament of Sri Lanka. Companies (Amendment) Act, No. 12 of 2025, sections 2, 4, 6 to 9 and Schedule, including inserted sections 130A, 130C and 130H. https://www.parliament.lk/uploads/acts/gbills/english/6389.pdf . Primary. Accessed 4 November 2026.
- Minister of Trade, Commerce, Food Security and Cooperative Development. Companies (Beneficial Ownership) Regulations, No. 1(I) of 2026, Gazette 2509/67, regulations 1 to 8 and Schedules I and II. https://drive.google.com/file/d/1v3jBw9yrmEX3U1g-dvD_q_jtAq5lL5hH/view . Primary, copy published by the DRC. Accessed 4 November 2026.
- Minister of Trade, Commerce, Food Security and Cooperative Development. Companies (Fees) Orders, Gazette 2496/03 of 6 July 2026, Schedule items 1, 5 to 10 and 12. https://drc.gov.lk/en/wp-content/uploads/2026/07/2496-03_E.pdf . Primary. Accessed 4 November 2026.
- Department of the Registrar of Companies. eROC Process B public interface guide, version 1.3, Forms 3, 6 to 17, 20 and 39; Incorporation public interface guide, version 1.0, forms shown at Figure 1.38. https://erocapiv2.drc.gov.lk/pdf/3.6.1%28a%29Incorporation_Frontend.pdf . Primary. Accessed 4 November 2026.
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act, No. 11 of 2026, sections 1 and 23, inserting Inland Revenue Act section 102(1A). https://www.parliament.lk/uploads/acts/gbills/english/6420.pdf . Primary. Accessed 4 November 2026.
- Parliament of Sri Lanka. Companies (Amendment) Act, No. 13 of 2019, sections 2 to 3. https://www.parliament.lk/uploads/acts/gbills/english/6119.pdf . Primary. Accessed 4 November 2026.
- Minister of Trade, Commerce, Food Security and Cooperative Development. Companies (Amendment) Act operation order, Gazette 2480/47 of 21 March 2026. Primary. Supplied Gazette. Accessed 4 November 2026.
- Department of the Registrar of Companies. Extension of Deadline for Submission of Beneficial Ownership Information, notice of 30 September 2026. https://drc.gov.lk/en/?p=4955 . Primary, official notice.
- Acting Minister of Trade, Commerce, Food Security and Cooperative Development. Companies (Beneficial Ownership) Regulations, No. 1(II) of 2026, Gazette 2511/47, regulations 1 to 4 and Schedule I. https://drive.google.com/file/d/1zQMPo8yAMzOb6PH4rzVxxEcoLN_S6Kc2/view . Primary, copy published by the DRC. Accessed 4 November 2026.
- Parliament of Sri Lanka. Rescue, Rehabilitation and Insolvency (Corporate and Personal) Act, No. 12 of 2026, sections 1, 469, 477 and 478. https://www.parliament.lk/uploads/acts/gbills/english/6419.pdf . Primary. Accessed 4 November 2026.
- Parliament of Sri Lanka. Companies (Amendment) Act, No. 13 of 2014, section 2, substituting section 132. https://www.parliament.lk/uploads/acts/gbills/english/5946.pdf . Primary. Accessed 4 November 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
Treat Form 15 as a live governance filing: the 30-working-day clock from the AGM, the BO 4 that goes with it, the fee, and the controls that keep it on time.
The October 2026 BO regulations replaced the March set, and from 22 October a late form costs Rs 1,000 a week. What a late BO 7 filing now costs.
Registering a private limited company in Sri Lanka in 2026: structure, name approval, the eROC filing with BO 1 and BO 5, the TIN and the first year.