
IRD Tax Calendar 2026 changes: what the printed calendar gets wrong
The IRD's printed 2026 calendar predates Act No. 11. One line is obsolete, one statement is missing, and two November dates differ in kind.
On this page
Last verified against the primary sources on 21 October 2026.
The IRD tax calendar 2026 changes that matter come from one fact: the IRD's printed calendar was created on 9 January 2026, and the Inland Revenue (Amendment) Act, No. 11 of 2026 was certified on 3 June 2026. So the calendar still shows a Statement of Estimated Tax on 15 August 2026, which the IRD says "has been discontinued", and it has no line for the quarterly AIT statements under section 86(8), the next of which falls on 30 October 2026. The routine 15th and 20th dates still match the Acts. This is the update; for the full year view, see our tax compliance calendar 2026.
A due date can come from two places. The statute fixes it, or the IRD sets or reads one in by notice or circular. The first binds whatever any calendar says. The second is the IRD's stated practice, and the IRD can move it again. A good tax calendar keeps the two apart. The IRD's own 2026 calendar does not try to, and it was printed before the biggest income tax amendment of the year.
Think of the calendar as a printed railway timetable. It is the most convenient thing to carry, and on most days the trains do run on time. But the timetable is not the track. When the track is relaid mid-year, the printed sheet is wrong until someone reprints it.
Take a hypothetical fire safety equipment servicing firm that runs payroll and is registered for VAT. Its accountant pins the IRD calendar to the wall in January. By October, is every line on it still right? Not quite. We go through it below.
The IRD calendar is a guide made on 9 January 2026, before Act No. 11
The "TAX CALENDAR - 2026 (Last Dates for Making Payments & Filing Returns)" is a six-page PDF published by the IRD and linked from its Tax Calendar page [1] [2]. Its file properties show it was created on 9 January 2026. It lists, month by month, the day, the period code, the description and the tax type code for income tax, APIT, WHT/AIT, VAT, VAT on financial services, SSCL, stamp duty and betting and gaming.
It is a guide. It cites no sections, and it has no legal force of its own. It matters to anyone who files or pays to the IRD: employers (APIT), withholding agents (WHT/AIT), VAT and SSCL registrants, banks paying VAT on financial services, and every income tax payer. Our payroll services team works to the APIT and WHT lines.
It covers calendar 2026, from the January payments for December 2025 to the November 2026 VAT return due 31 December 2026 [1]. Note the date it was made. The Inland Revenue (Amendment) Act, No. 11 of 2026 was certified on 3 June 2026, five months later [4].
The 15th and 20th dates still match the Acts
| Calendar entry | Day | Statutory source |
|---|---|---|
| APIT and WHT/AIT payment | 15th | IRA s.86(1): "within fifteen days after the end of each calendar month" [3] |
| VAT payment | 20th | VAT Act s.26(1): "not later than the twentieth day of the month following the end of the taxable period" [8] |
| VAT return | Month end | VAT Act s.21(1)(a)(iii): "not later than the last day of the month after the expiry of each taxable period" [8] |
| SSCL payment | 20th | SSCL Act s.17, monthly amounts by the twentieth day of the following month [9] |
| SSCL return | 20th after the quarter | SSCL Act s.8(1): "on or before the twentieth day of the month after the end of each relevant quarter" [9] |
| AIT/WHT and APIT annual statements | 30 April | IRA s.86(2): "within thirty days after the end of each year ending on the thirty first day of March" [3] |
| Income tax instalments | 15 Aug, 15 Nov, 15 Feb, 15 May | IRA s.90(2) [3] |
| Final payment of income tax | 30 September | IRA s.82(2)(c)(ii): "six months after the end of the year of assessment" [3] |
| Income tax return | 30 November | IRA s.93(1): "not later than eight months after the end of each year of assessment" [3] |
We checked these against the Acts. The stamp duty compounded payment on the 15th after each quarter matches section 7(1) of the Stamp Duty (Special Provisions) Act No. 12 of 2006 ("within fifteen days from the end of the relevant quarter"); see our piece on the Stamp Duty Act No. 12 of 2006. We did not check the betting and gaming or VAT on financial services interim estimate dates against their statutes, so treat those as IRD dates only.
IRD tax calendar 2026 changes: what is now wrong or missing
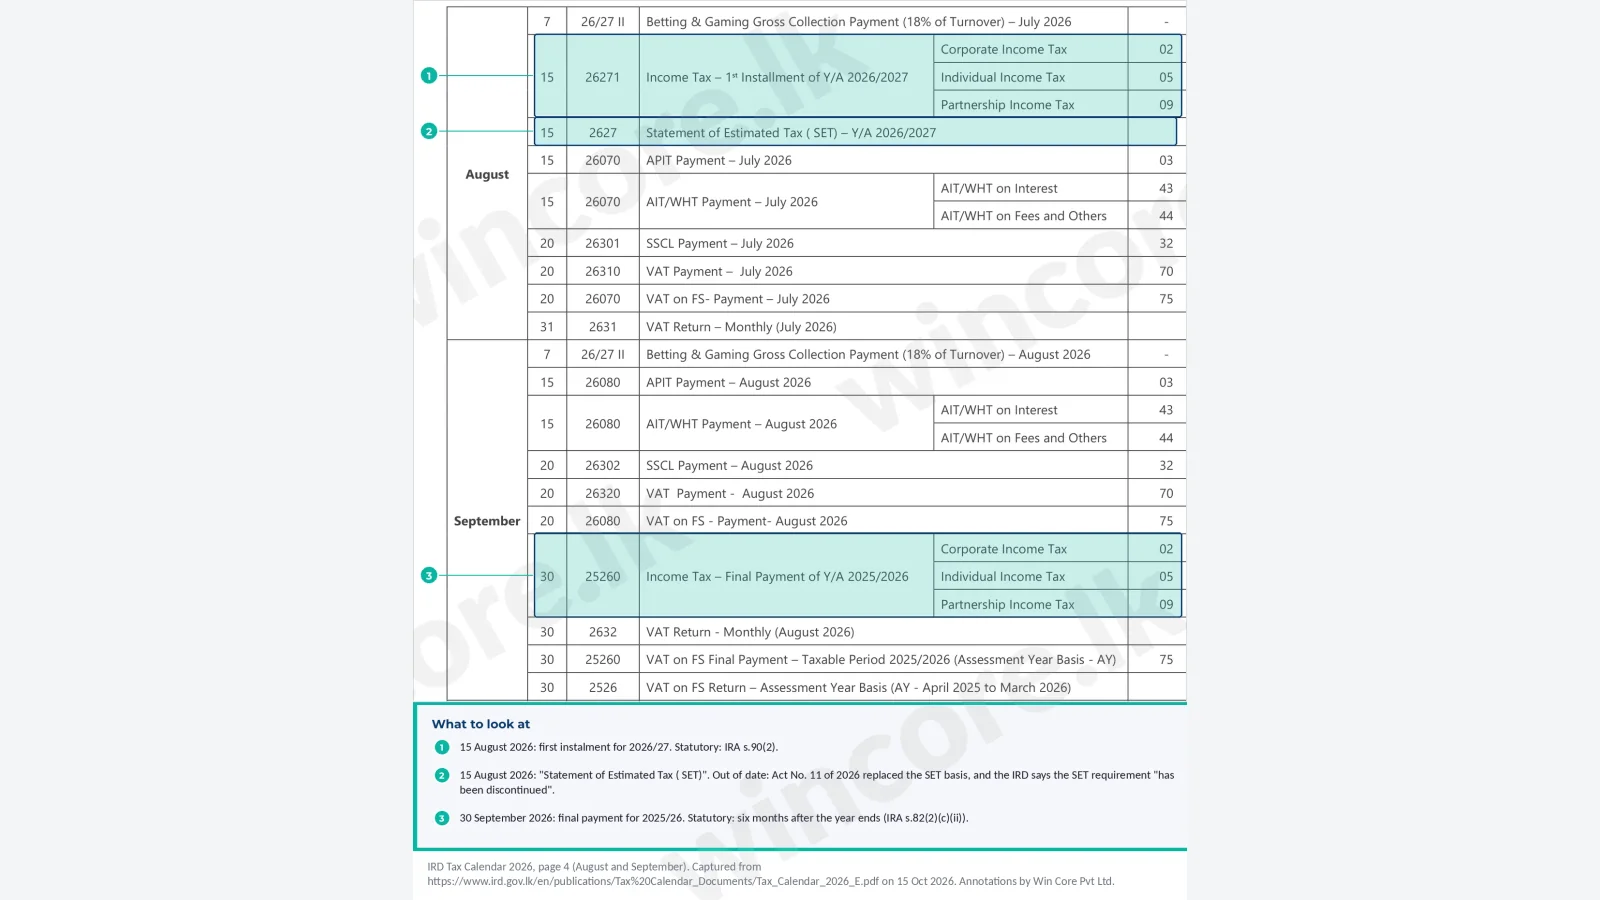
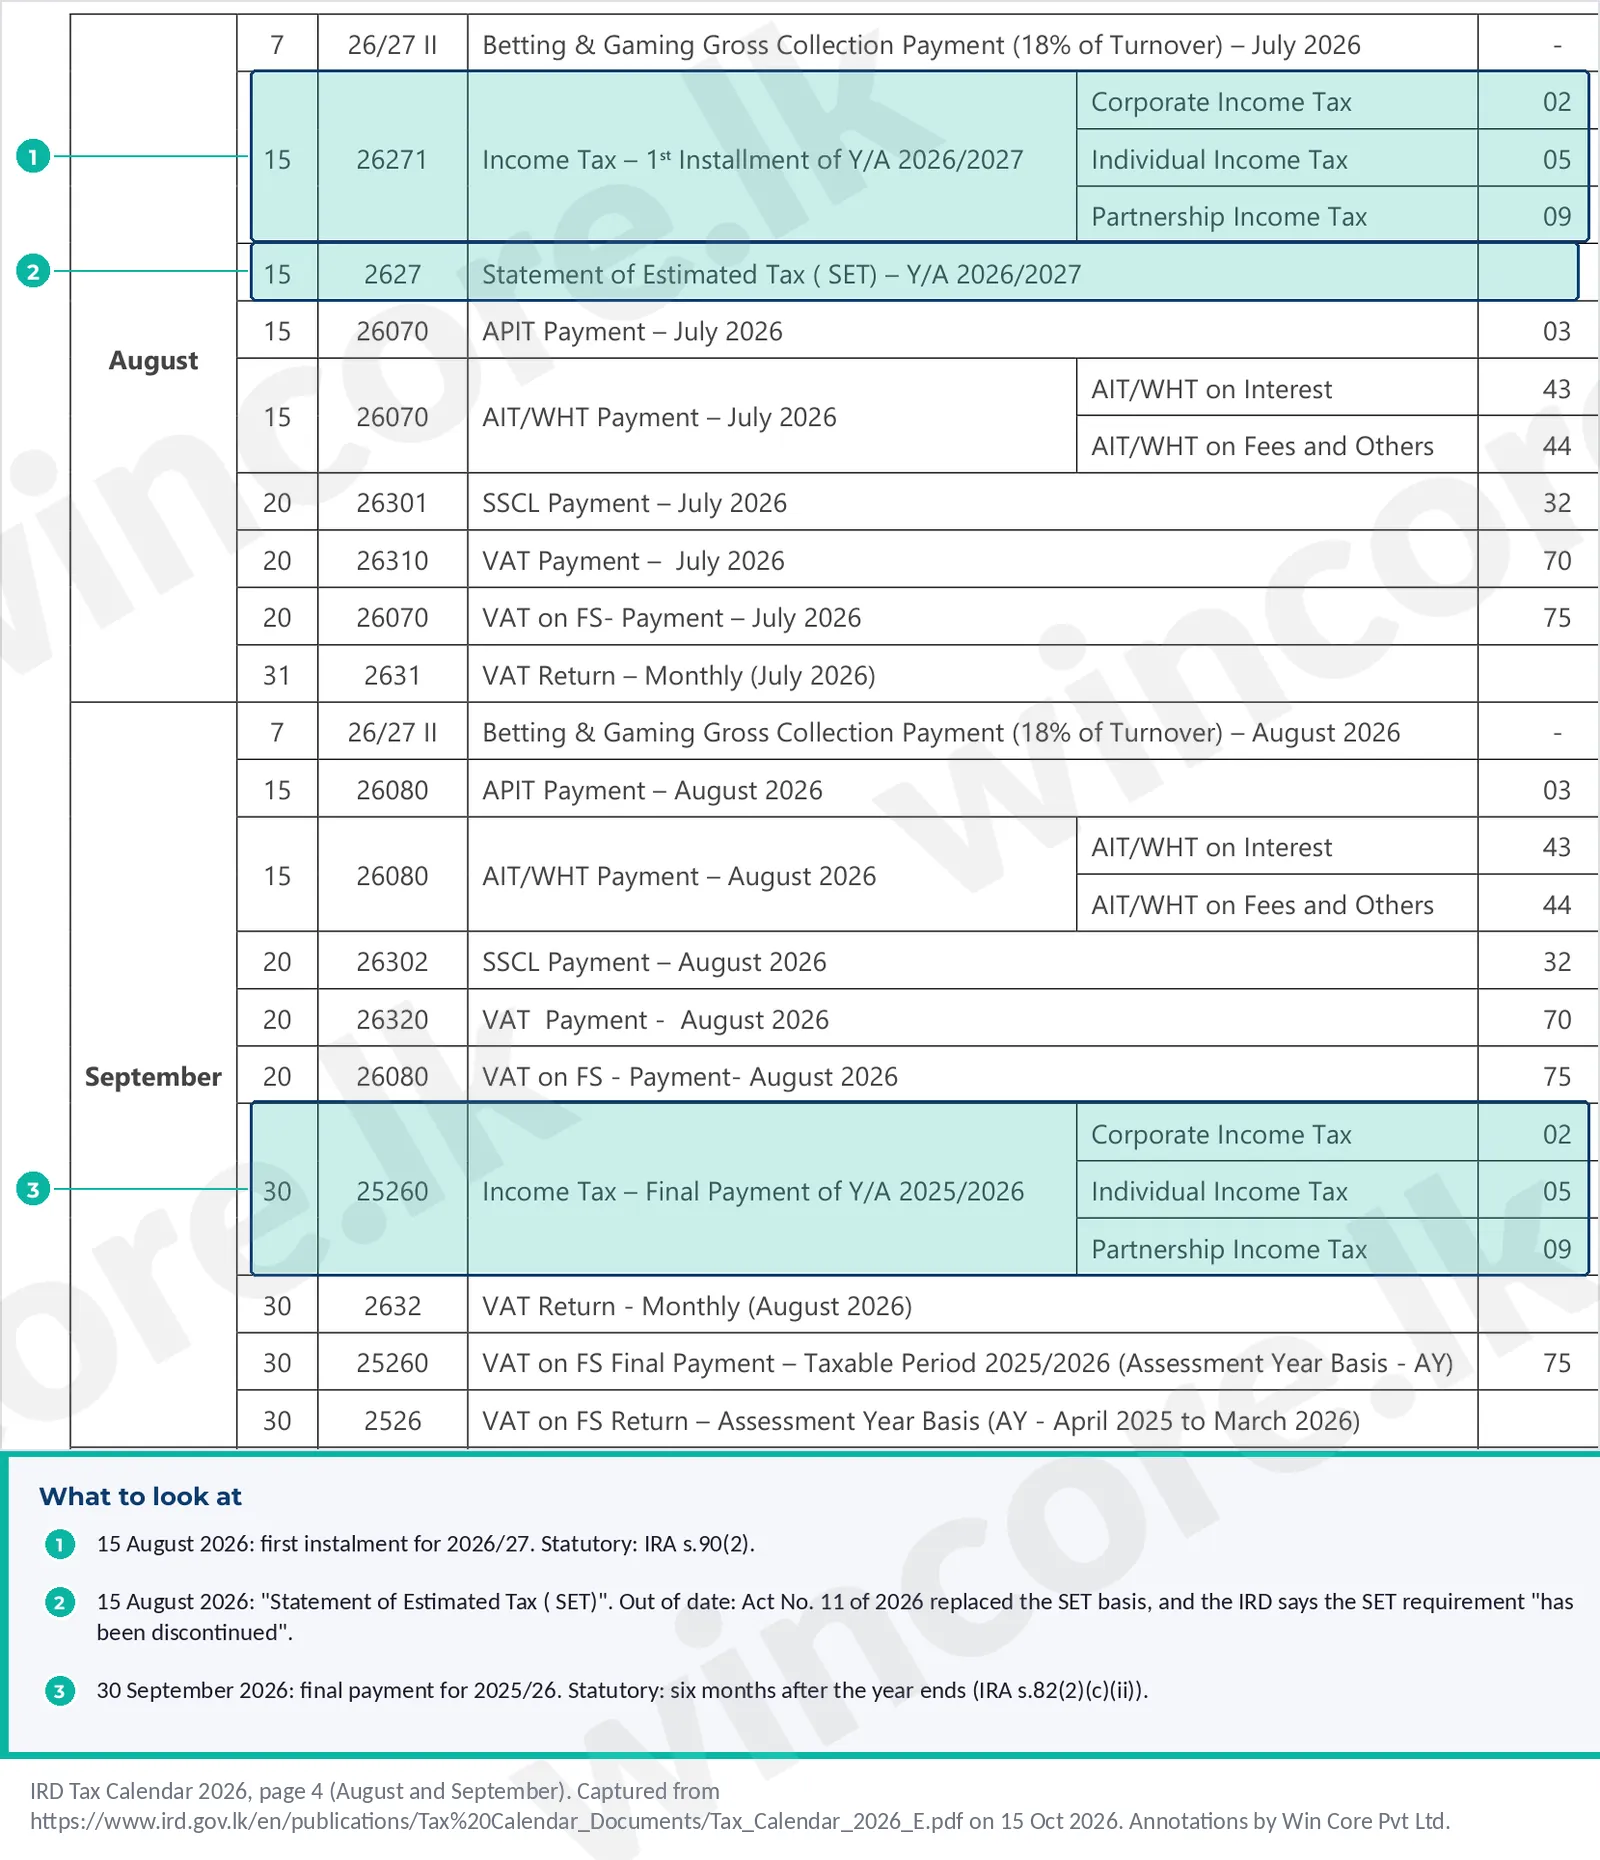
The Statement of Estimated Tax. The calendar shows "Statement of Estimated Tax ( SET) - Y/A 2026/2027" on 15 August 2026 [1]. Act No. 11 rewrote the instalment formula so that it starts from last year's tax [4], and the IRD's notice says "The requirement to file a statement of estimated tax (SET) payable has been discontinued" [5]. That line is out of date. Our guide to the SET form being abolished and our Regulation Desk piece on Circular SEC/2026/E/06 cover the new basis.
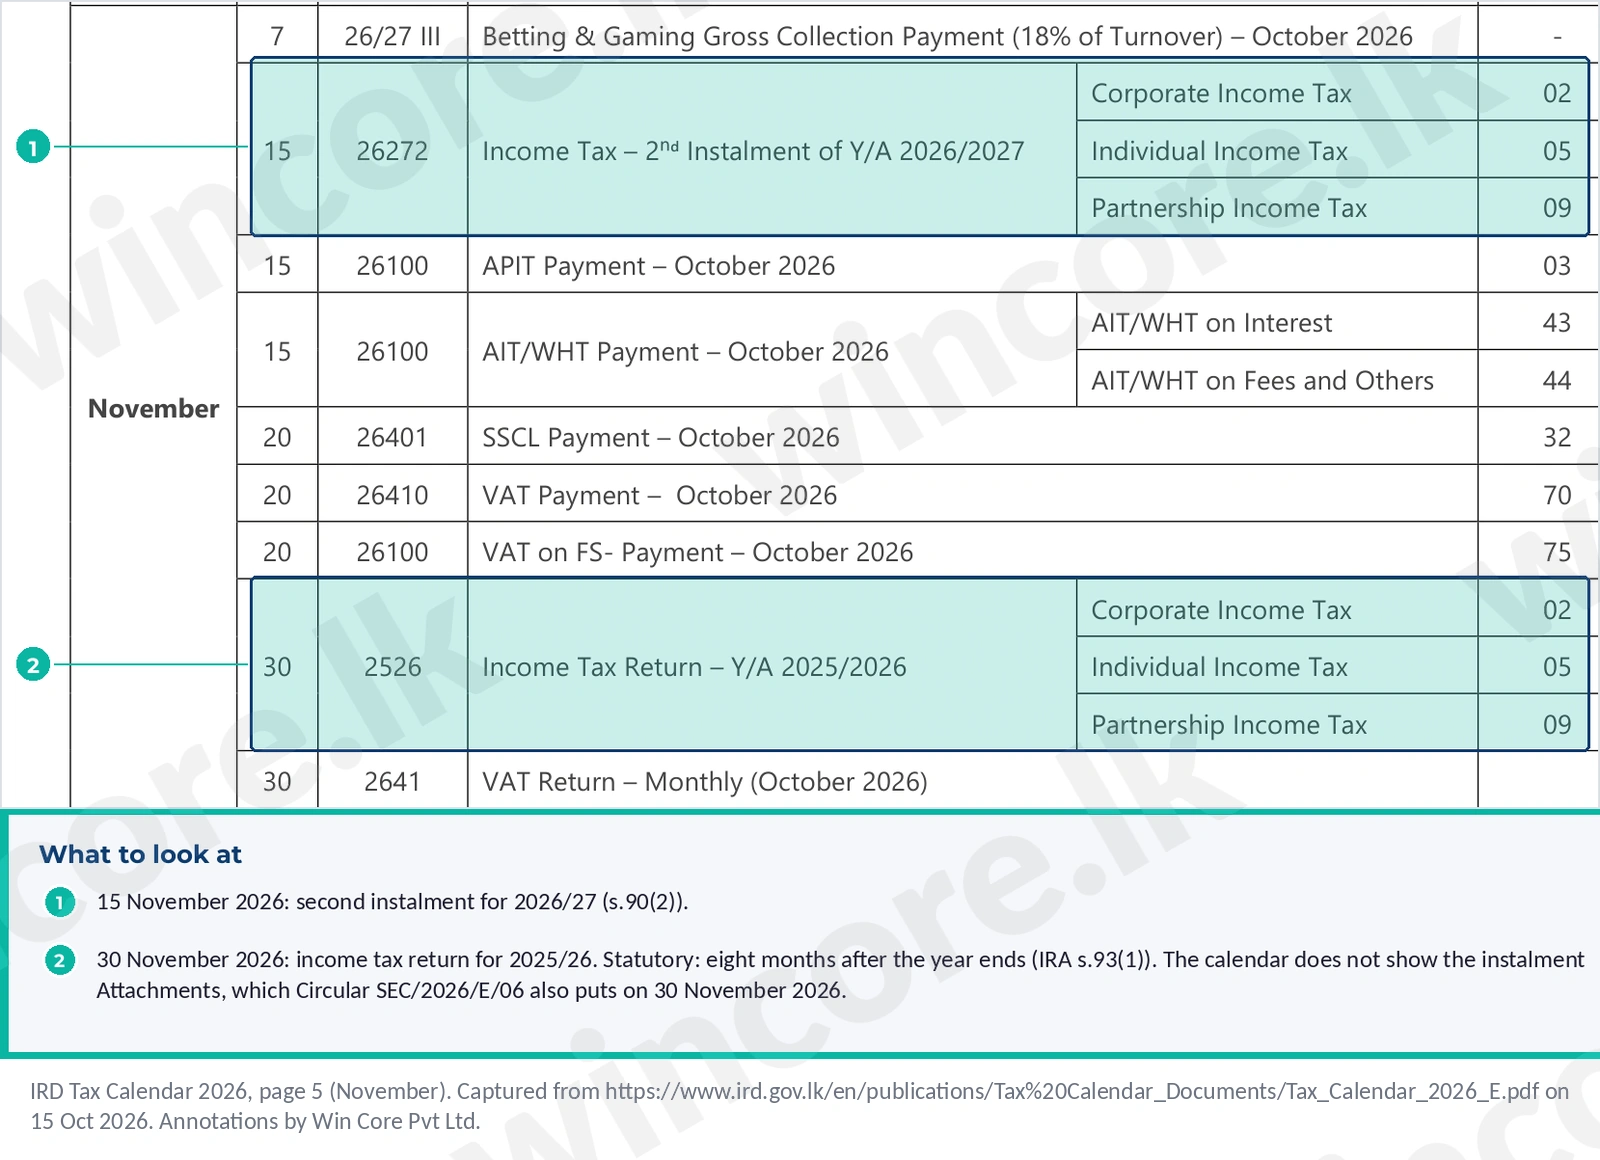
The instalment Attachments. Under the re-revised Circular SEC/2026/E/06, taxpayers using an alternative basis file Attachment 1 or 2 by 30 November 2026 [6]. That date is not in the calendar, and it is administrative: the circular set it, after earlier versions said 31 July and then 15 August.
AIT quarterly statements. Section 86(8) requires a quarterly statement of AIT deducted "within thirty days after the end of each quarter, ending on the thirtieth day of June, thirtieth day of September and thirty first day of December" [3]. That puts the next one on 30 October 2026. The calendar has no line for it; it lists only the monthly AIT/WHT payments and the 30 April annual statement. Act No. 11 confirms the statement still exists: its new section 86(9) lets the Commissioner-General specify "the procedures, formats and forms for filing statements required under subsections (2) and (8)" [4]. Our guide to the WHT annual statement and certificate covers the yearly side.
The interest write-off. Section 42 of Act No. 11 writes off section 157 interest up to the year of assessment ending 31 March 2025, on condition that "the full amount of tax and any applicable penalties" are paid "prior to the expiration of a period of six months from the date on which the provisions referred to in subsection (2) of section 1 come into operation" [4]. The IRD's notice gives the last day as 2 December 2026 [7]. The calendar predates both. Our Regulation Desk piece on Act No. 11 of 2026 covers it.
From 1 July 2026. The VAT (Amendment) Act No. 14 of 2026 moves financial services VAT to 20.5 percent and starts VAT on digital services from non-resident providers; the SSCL amendments drop the registration threshold to Rs 9 million a quarter or Rs 36 million over four quarters. The calendar's dates still apply to filing and payment, but the obligations behind some lines changed. See our Regulation Desk pieces on VAT Amendment Act No. 14 of 2026 and the SSCL amendments, and our guide to SSCL registration at Rs 9 million.
30 November 2026 is two deadlines, and only one is statutory
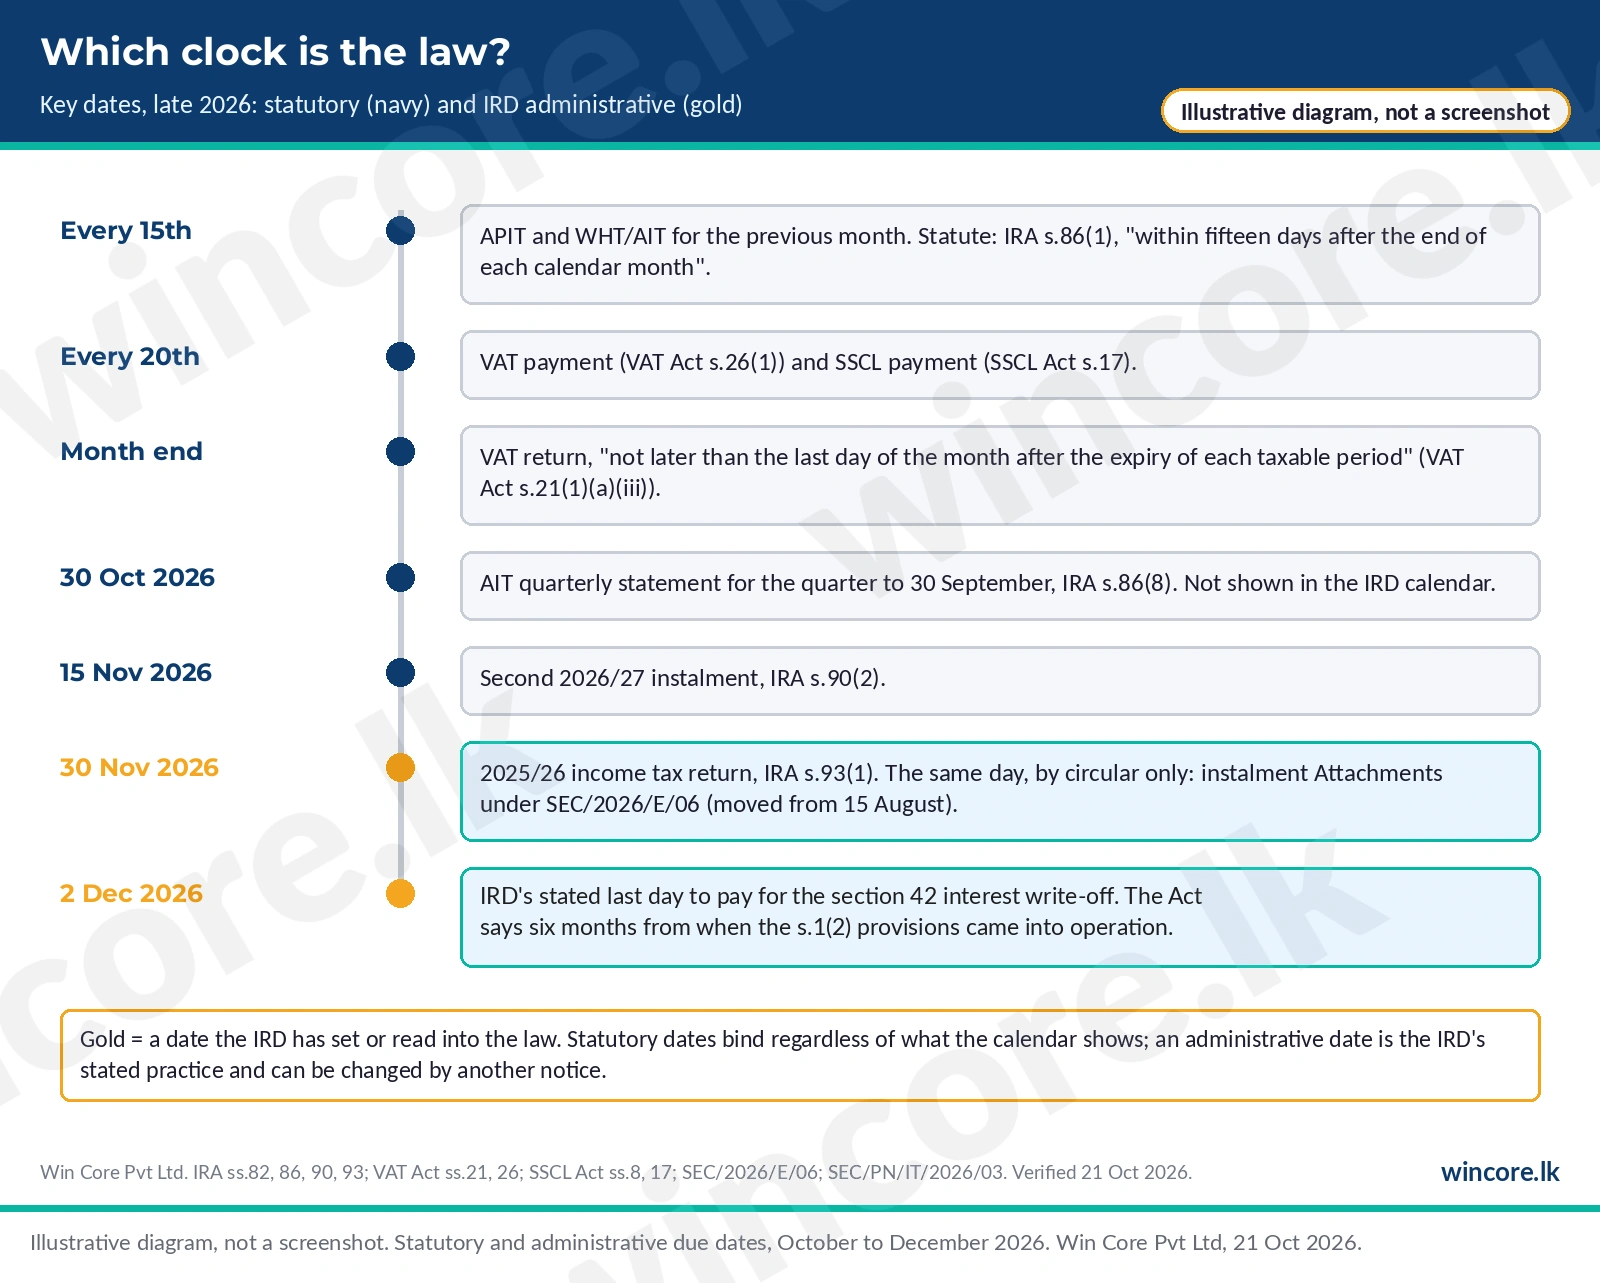
The 2025/26 return on 30 November 2026 is statutory. The Attachments on the same day are administrative. They share a date, but only one of them can be extended by a fresh notice. The 2 December 2026 date is the IRD's count of a statutory six-month window that runs from the date the section 1(2) provisions came into operation. On our reading, if the IRD's count is right it adds nothing, and if it is generous, the Act still governs, so pay before 2 December and do not test the margin.
Each default has its own penalty section, so quote the right one
| Default | Section | Consequence |
|---|---|---|
| Tax due not paid within fourteen days of the due date, or by the due date in a notice of assessment if later | IRA s.179(1) | "twenty per cent of the amount of tax due but not paid", charged once |
| Income tax instalment not paid within 14 days of its due date | IRA s.179(2) | "ten per cent of the amount of tax due but not paid", instead of the 20 percent |
| Any tax paid late | IRA s.157(1), s.159(1) | Interest from the due date at "one and one-half per cent per month or part month" |
| Return filed late | IRA s.178(1), (2) | Greater of 5 percent of tax owing plus 1 percent a month, or Rs 50,000 plus Rs 10,000 a month; capped at Rs 400,000 |
| Annual statement (s.86), return (s.93) or registration (s.102) still outstanding 30 days after a written notice | IRA s.185A (Act No. 11) | Offence: fine up to Rs 400,000, up to six months, or both |
VAT and SSCL defaults have their own penalty sections; our pieces on those Acts map them [8] [9]. To estimate the late payment cost, use our penalty calculator, and check its result against the section for your specific default.
A weekend due date does not move, on our reading
The calendar prints 15 August 2026, which was a Saturday, and 15 November 2026, a Sunday. We found no provision in the Inland Revenue Act that moves a due date falling on a weekend or holiday, and the calendar does not say either way; this stays an open point below. Online payment runs every day, so on our reading the safe course is to treat the printed date as standing. Which brings us back to the timetable: when the printed time looks odd, check the track, then catch the earlier train.
What to change in your diary now
- Strike the SET line for 15 August 2026 and diarise the instalment Attachments for 30 November 2026, if you use an alternative basis.
- Add 30 October 2026, 30 January 2027 and 30 July 2027 for AIT quarterly statements.
- Pay by the 15th and the 20th as before.
- File the 2025/26 return by 30 November 2026.
- Mark administrative dates in a different colour, and check for new notices before relying on them.
- Check older calendars against this list. Our income tax advisory services team can set this up.
Checklist: documents needed
- The IRD Tax Calendar 2026 PDF, with the 15 August SET line struck through
- Circular SEC/2026/E/06 (Re-Revised), if you use an alternative instalment basis
- Your AIT deduction records for July to September 2026, for the 30 October statement
- The 2025/26 return working papers and proof of the 30 September final payment
- IRD notice SEC/PN/IT/2026/03, if you have interest outstanding up to 2024/25
- Your VAT and SSCL filing frequency (monthly or quarterly), so the right return dates go in
Common misreadings
- "The calendar is the law." It is a guide; the dates come from the Acts.
- "The SET is still due on 15 August." Discontinued [5].
- "30 November is one deadline." It is two: a statutory return and an administrative Attachment.
- "A Sunday due date moves to Monday." We found no such rule.
- "The interest write-off date is in the Act." The Act sets a six-month window; 2 December 2026 is the IRD's date.
Hypothetical example
Back to the fire safety servicing firm, on 15 October 2026. It paid September APIT and WHT today (s.86(1)). VAT and SSCL for September are due on 20 October, and so is its SSCL return for July to September. Its September VAT return is due 31 October. It deducts AIT on rent, so the quarterly AIT statement is due 30 October, though the calendar is silent. Its second 2026/27 instalment is due 15 November. Its 2025/26 return is due 30 November; it uses Method 1 for instalments, so it files no Attachment. Had it relied on the calendar, it would have missed one statement and wasted time on a SET it no longer files.
What this means for you
Keep using the IRD calendar for the routine 15th and 20th dates, which match the Acts. Do not use it for anything Act No. 11 changed. Separate the dates that bind from the dates the IRD has chosen, and recheck the second kind against the latest notice.
FAQ
Is the IRD Tax Calendar 2026 up to date?
Not fully. The PDF was created on 9 January 2026, five months before the Inland Revenue (Amendment) Act No. 11 of 2026 was certified on 3 June 2026 [1] [4]. Its monthly 15th and 20th dates still match the Acts, but it shows a discontinued SET line on 15 August and has no line for quarterly AIT statements.
Do I still file a Statement of Estimated Tax in 2026?
No. The IRD's notice on Act No. 11 says "The requirement to file a statement of estimated tax (SET) payable has been discontinued" [5]. Instalments for 2026/27 are now worked out from the previous year's tax under the amended section 90(3), with an alternative basis available under Circular SEC/2026/E/06.
When is the 2025/26 income tax return due in Sri Lanka?
It is due on 30 November 2026. Section 93(1) of the Inland Revenue Act requires the return "not later than eight months after the end of each year of assessment" [3], and the year ended on 31 March 2026. The final payment of the tax was due earlier, on 30 September 2026.
When is the AIT quarterly statement due?
The next one is due on 30 October 2026, for the quarter to 30 September. Section 86(8) requires it within thirty days after the quarters ending 30 June, 30 September and 31 December [3]. The year to 31 March is covered by the annual statement due 30 April, so the calendar's silence does not remove the duty.
Is the 30 November 2026 instalment Attachment date set by law?
No. It comes from Circular SEC/2026/E/06 (Re-Revised) [6], which moved it from earlier dates of 31 July and then 15 August. Only taxpayers using an alternative instalment basis file it. Because it is an administrative date, the IRD can move it again by notice, so check before relying on it.
Open points
- Weekend due dates. We found no rule; the IRD has not said either way in the calendar.
- AIT quarterly statements. Why the calendar omits them is not stated.
- Interest write-off count. Section 42(2) counts six months from the date the section 1(2) provisions came into operation; we did not read section 1(2) and its date table for this piece. The IRD's notice says the last day is 2 December 2026.
- Unchecked lines. Betting and gaming and VAT on financial services estimate dates are reported from the calendar only.
- Betting and gaming rate. The calendar moves from 15 percent of turnover (December 2025) to 18 percent (January 2026 onward). We did not check the instrument behind the change for this piece.
Last verified
We checked the calendar and the Acts on 15 October 2026, and re-read the calendar and Act No. 11 of 2026 on 21 October 2026. This is ordinary diary discipline, and a reprinted IRD calendar could make half of it unnecessary.
The short version
- The 15th (APIT, WHT) and 20th (VAT, SSCL) dates are statutory and unchanged.
- The SET line for 15 August 2026 is out of date.
- 30 November 2026: return (statutory) and Attachments (administrative).
- Add AIT quarterly statements on 30 October.
- 2 December 2026 is the IRD's date for the interest write-off.
Carry the timetable, but check the track.
Talk to us. If you would like a filing calendar built from the statutes for your business, book a consultation at our contact page.
WinCore Pvt Ltd
This article is general information on the law as at 21 October 2026 and is not advice on your specific position.
References
- Inland Revenue Department. Tax Calendar - 2026 (Last Dates for Making Payments & Filing Returns) (PDF created 9 January 2026), pp.1 to 5. https://www.ird.gov.lk/en/publications/Tax%20Calendar_Documents/Tax_Calendar_2026_E.pdf . Primary. Accessed 21 October 2026.
- Inland Revenue Department. Tax Calendar web page. https://www.ird.gov.lk/en/publications/SitePages/Tax%20Calendar.aspx?menuid=1405 . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Inland Revenue Act, No. 24 of 2017, consolidated with amendments to 2025, ss.82(2), 86(1), (2) and (8), 90(2), 93(1), 157, 159, 178 and 179. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary. Accessed 15 October 2026.
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act, No. 11 of 2026 (certified 3 June 2026), ss.16, 31 (new s.185A), 42 and the new s.86(9). https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 21 October 2026.
- Inland Revenue Department. Notice to the Taxpayers: Amendments to the Inland Revenue Act, No. 24 of 2017, SEC/PN/IT/2026/02 (8 June 2026), item 11. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/794/SEC_PN_IT_2026-02_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Circular on Calculating Quarterly Income Tax Instalments, SEC/2026/E/06 (Re-Revised Circular) (12 August 2026), p.11. https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2026_E_06_ReRiv_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Notice to the Taxpayers: Interest Relief for Underpayments and Late Payments, SEC/PN/IT/2026/03 (8 June 2026). https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/789/SEC_PN_IT_2026-03.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Value Added Tax Act, No. 14 of 2002, consolidated to 2025, ss.21(1)(a) and 26(1). https://www.ird.gov.lk/en/publications/Value%20Added%20Tax_Acts/VAT_Act_No_14%5BE%5D_2002_%28Consolidation_2025%29.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Social Security Contribution Levy Act, No. 25 of 2022, consolidated to 2026, ss.8(1) and 17. https://www.ird.gov.lk/en/publications/Acts_SSCL/SSCL_Cons_Act_-_2026_Changes.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Notice to Taxpayers: Income Tax Final payment for the Year of Assessment 2025/2026 due on or before September 30, 2026. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/813/IT_28092026_E.pdf . Primary. Accessed 15 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.

Sri Lanka tax compliance calendar for 2026 with APIT, VAT, income tax, and statutory filing checkpoints for finance and payroll teams.

The SET filing requirement is gone from Y/A 2026/27. Quarterly instalments now follow a formula based on the previous year's tax. Here is how it works.
WHT reporting breaks when certificates and annual statements are treated as year-end admin. Build a monthly evidence workflow that files cleanly.