
SSCL amendment 2026: Acts No. 24 of 2025 and No. 10 of 2026
Fuel and vehicle exemptions, a bank exemption that bites later than it looks, and a lower threshold: the two SSCL Acts read clause by clause.
On this page
Last verified against the primary sources on 21 October 2026.
The SSCL amendment 2026 is two Acts. Act No. 24 of 2025, certified on 17 December 2025, exempted all sales of petrol, diesel and kerosene from 1 July 2025, narrowed a power machinery exemption from 18 February 2025, and exempted container terminal services and financial services taxed at 20.5 percent VAT. Act No. 10 of 2026, certified on 9 April 2026, moved the levy on motor vehicles from the showroom to the port from 1 May 2026 and cut the registration threshold to Rs 9 million a quarter or Rs 36 million over four quarters from 1 July 2026. The rate is still 2.5 percent, VAT is still outside the base, and the levy is still paid monthly by the 20th [1] [2] [3] [4].
The rate is unchanged: 2.5 percent of liable turnover, VAT excluded
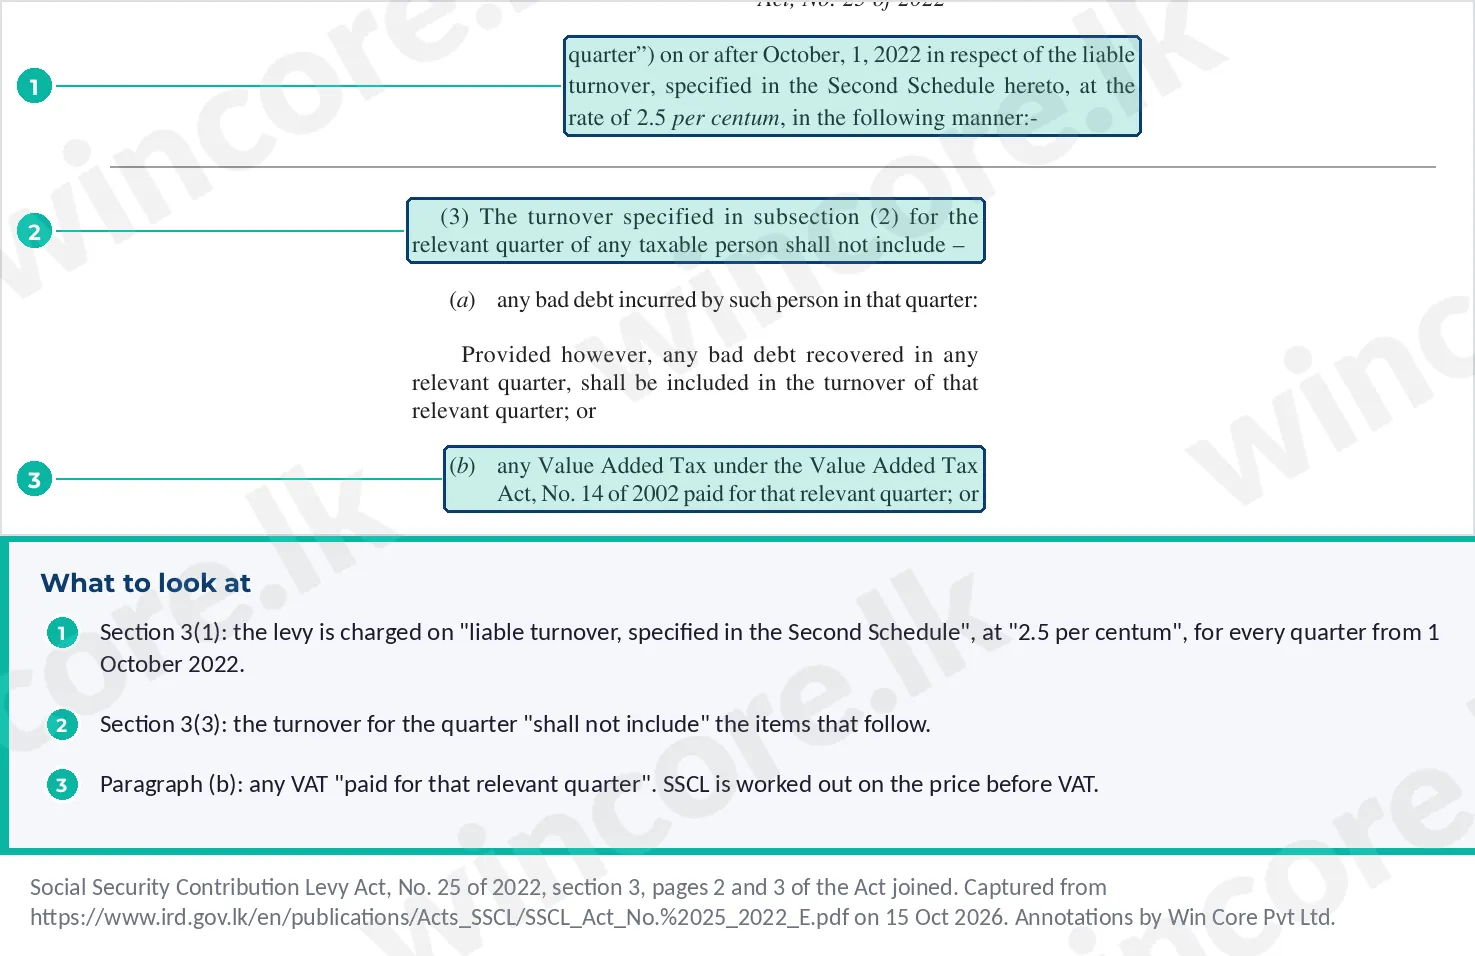
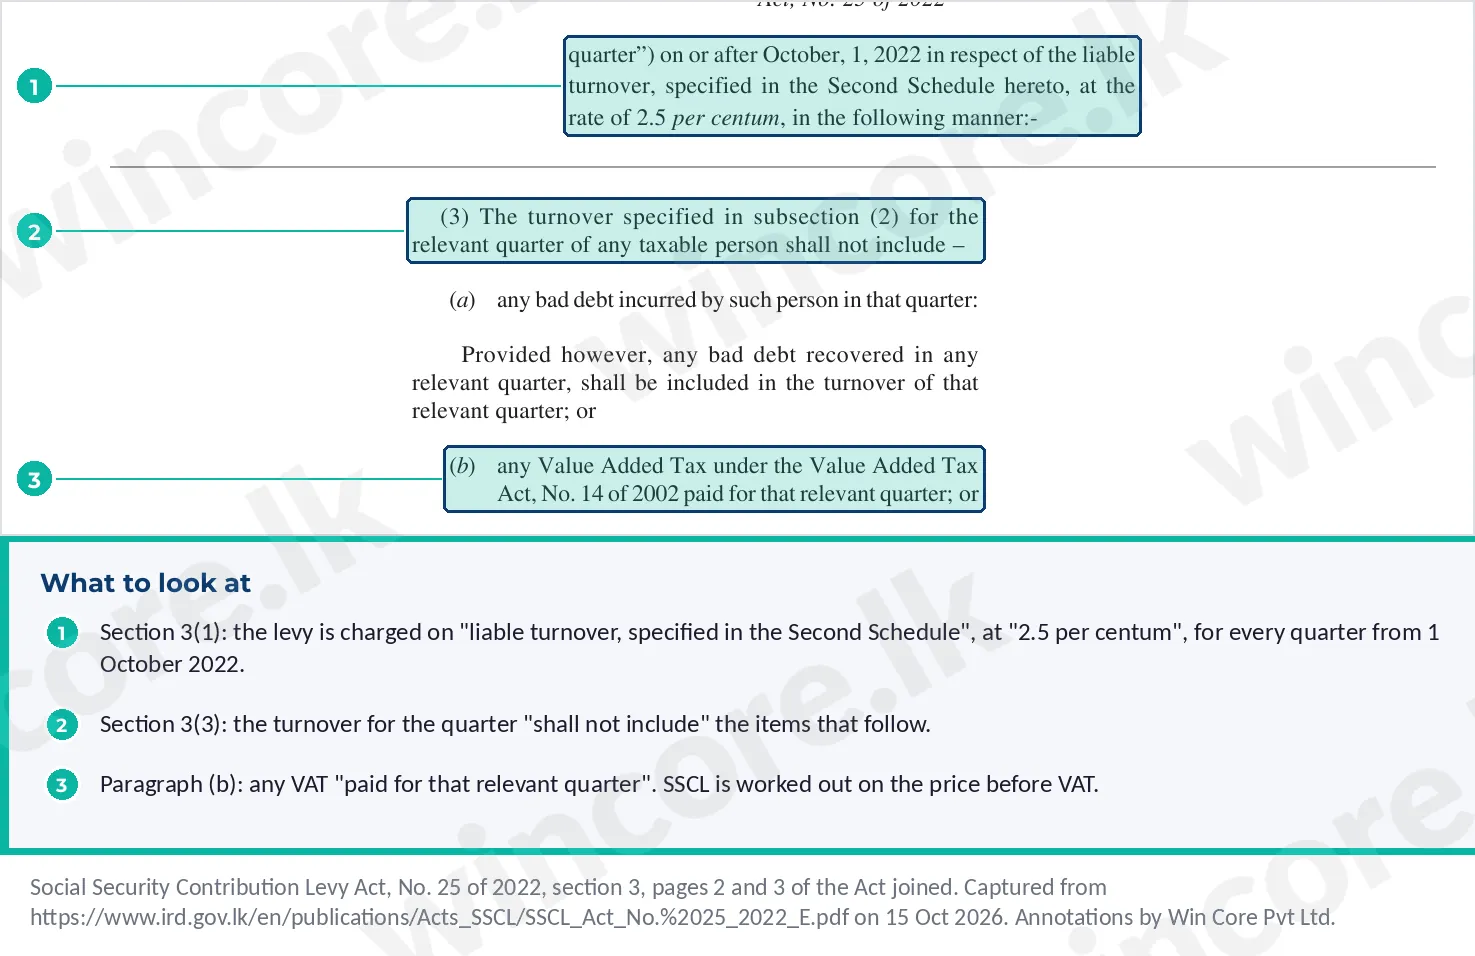
The Social Security Contribution Levy Act, No. 25 of 2022 has applied since 1 October 2022. It covers four kinds of taxable person: importers, manufacturers, service providers, and wholesalers or retailers (section 2) [1]. Section 3(1) charges the levy on "liable turnover, specified in the Second Schedule hereto, at the rate of 2.5 per centum" [1].
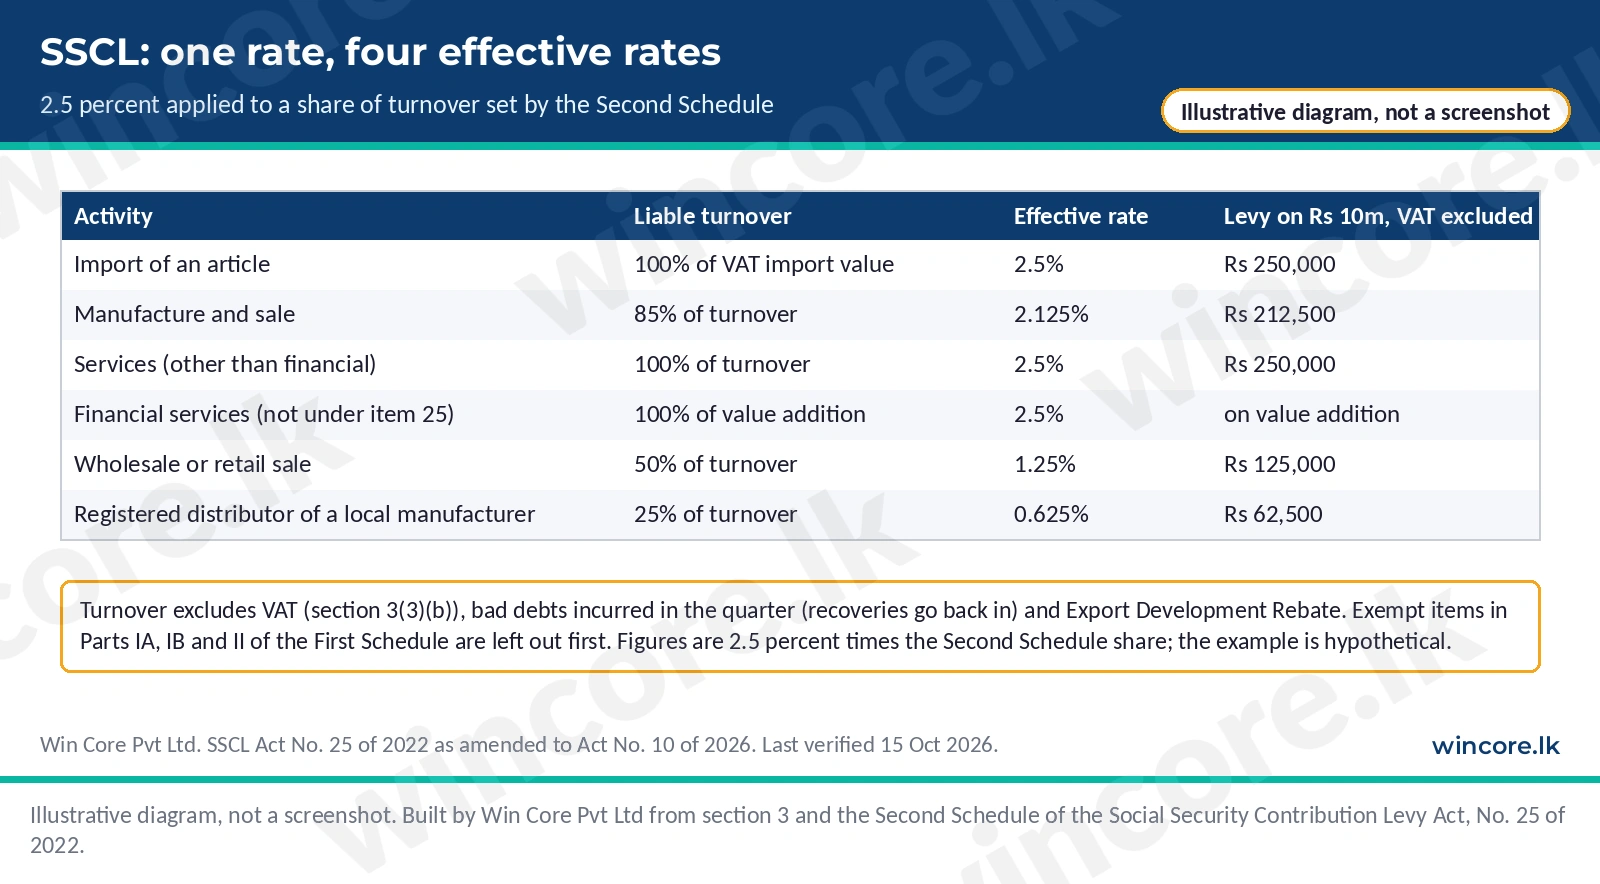
Section 3(3) sets the filters. Turnover "shall not include" (a) any bad debt incurred in the quarter, with recovered bad debts added back; (b) "any Value Added Tax under the Value Added Tax Act, No. 14 of 2002 paid for that relevant quarter"; and (c) any Export Development Rebate for an approved international event [1]. Exempt articles and services in Parts IA, IB and II of the First Schedule are also outside the definition of turnover in section 3(2) [1].
Section 16 puts SSCL on an accrual basis, so in practice VAT comes out invoice by invoice [2]; on our reading "paid for that relevant quarter" means the VAT that falls due for the quarter, and we have not found an IRD statement on the point. Why that VAT is never input tax is in our piece on SSCL on a supplier invoice.
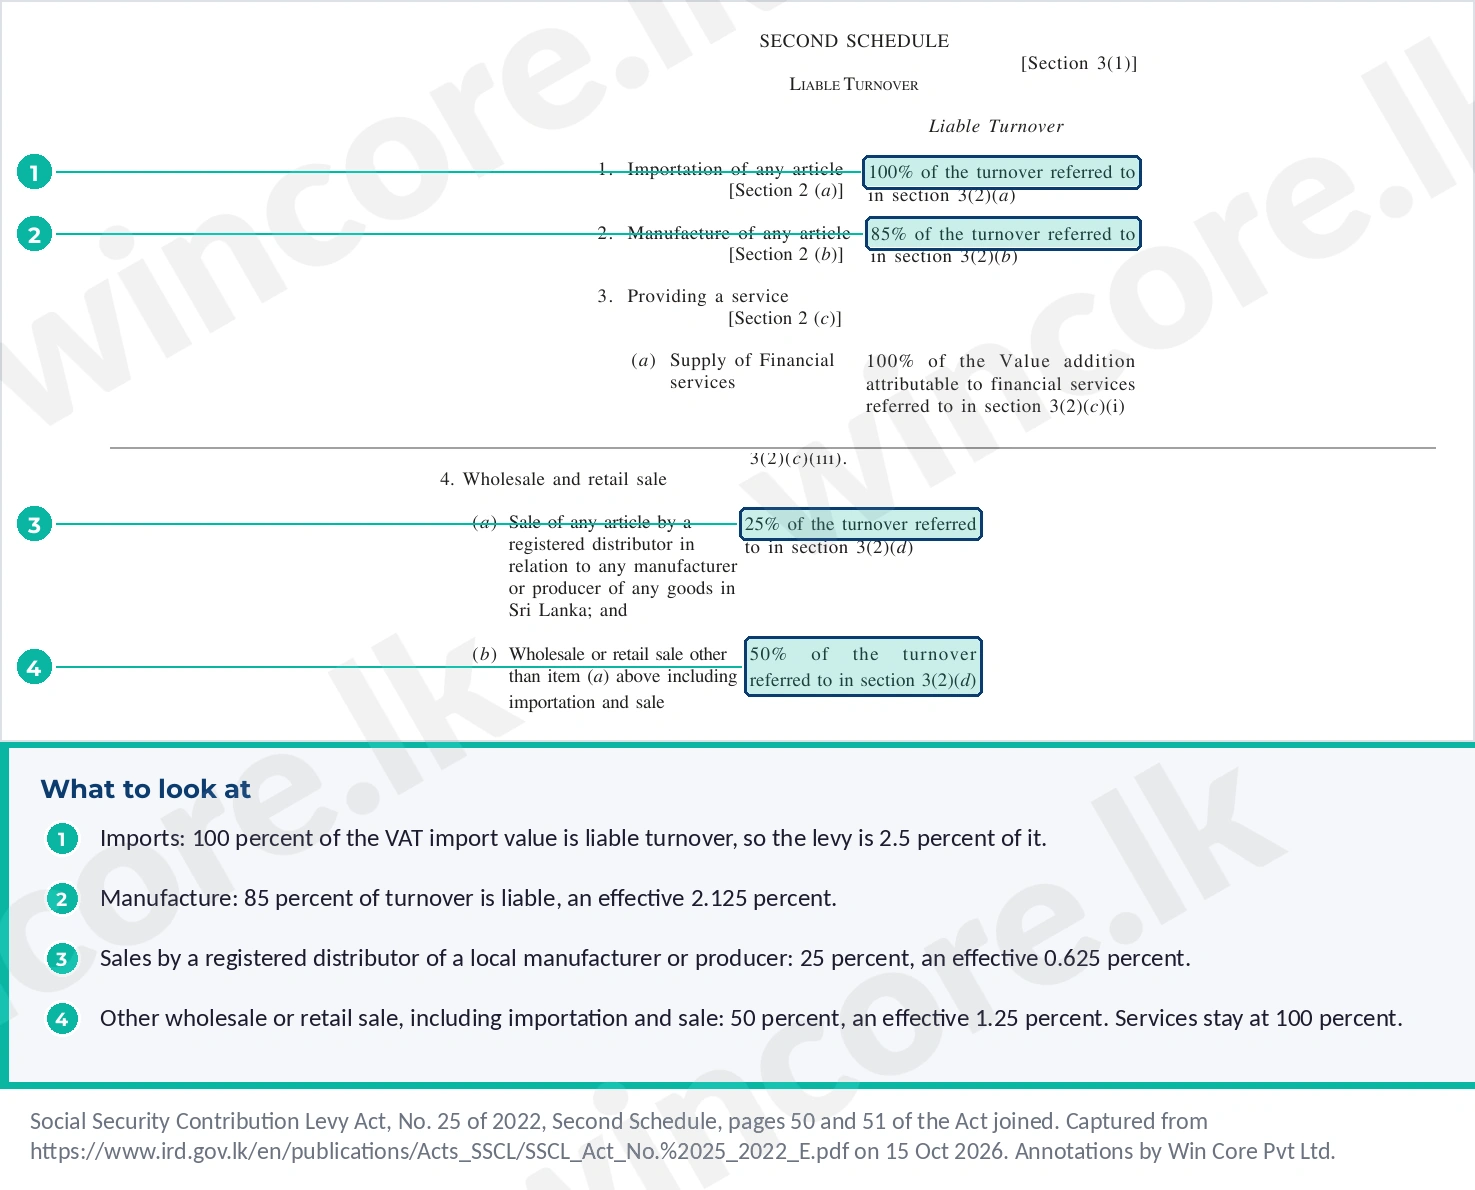
The Second Schedule then sets the share of turnover that is liable: 100 percent for imports, manufacture at 85 percent, services at 100 percent (financial services on value addition), and wholesale or retail sales at 50 percent, or 25 percent for a registered distributor of a local manufacturer or producer [1]. Neither amending Act touched these percentages.
Act No. 24 of 2025 changed four exemptions on three dates
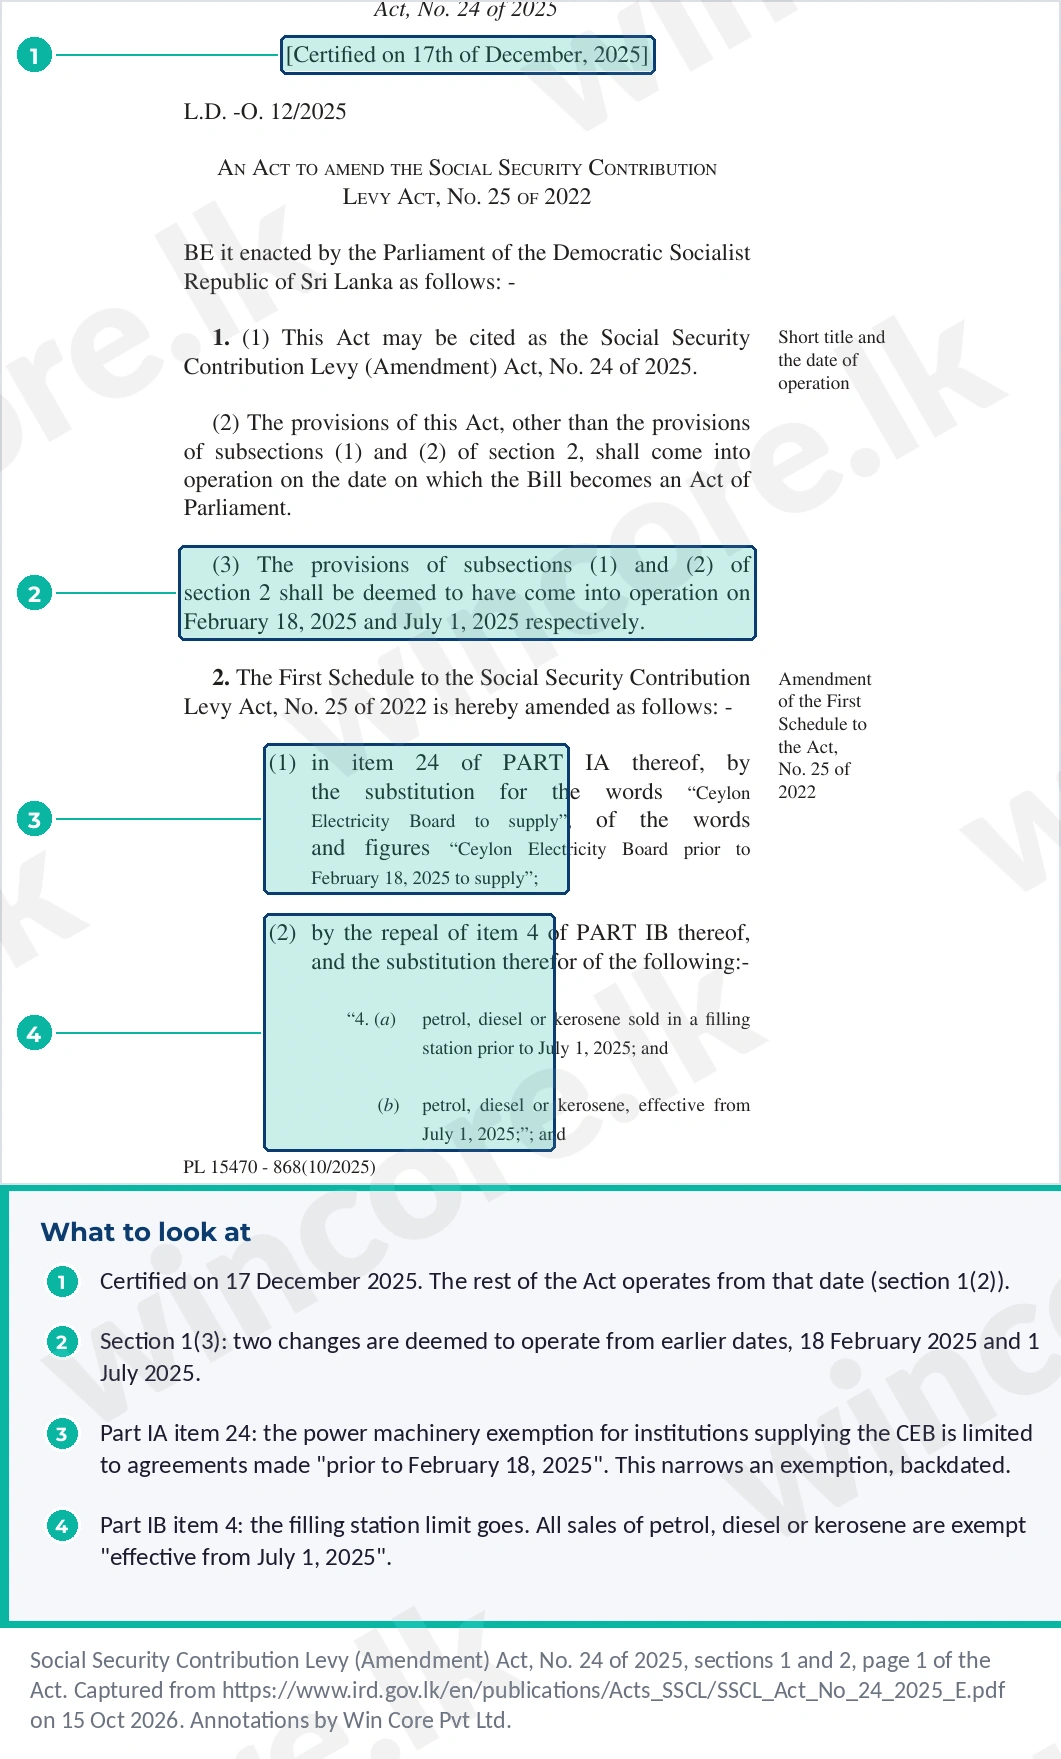
Act No. 24 of 2025 was certified on 17 December 2025 and published on 26 December 2025 [3]. Section 1(2) brings it into operation when the Bill becomes an Act, which under Article 80(1) of the Constitution is the date of the Speaker's certificate [3] [9]. Section 1(3) deems two of its changes to have operated earlier: section 2(1) from 18 February 2025 and section 2(2) from 1 July 2025 [3].
- Power machinery, narrowed from 18 February 2025. Part IA item 24 exempts machinery for generating electricity by the Ceylon Electricity Board or an institution supplying it. The Act limits the second group to institutions with an agreement with the Board "prior to February 18, 2025" [3]. This is the only change in either Act that takes an exemption away with backdated effect.
- Fuel, widened from 1 July 2025. Part IB item 4 used to cover petrol, diesel or kerosene "sold in a filling station". It now reads: "(a) petrol, diesel or kerosene sold in a filling station prior to July 1, 2025; and (b) petrol, diesel or kerosene, effective from July 1, 2025" [3]. Every wholesale or retail sale of the three fuels is exempt from that date. Import and manufacture of petroleum products other than lubricants were already exempt under Part IA item 10 [2].
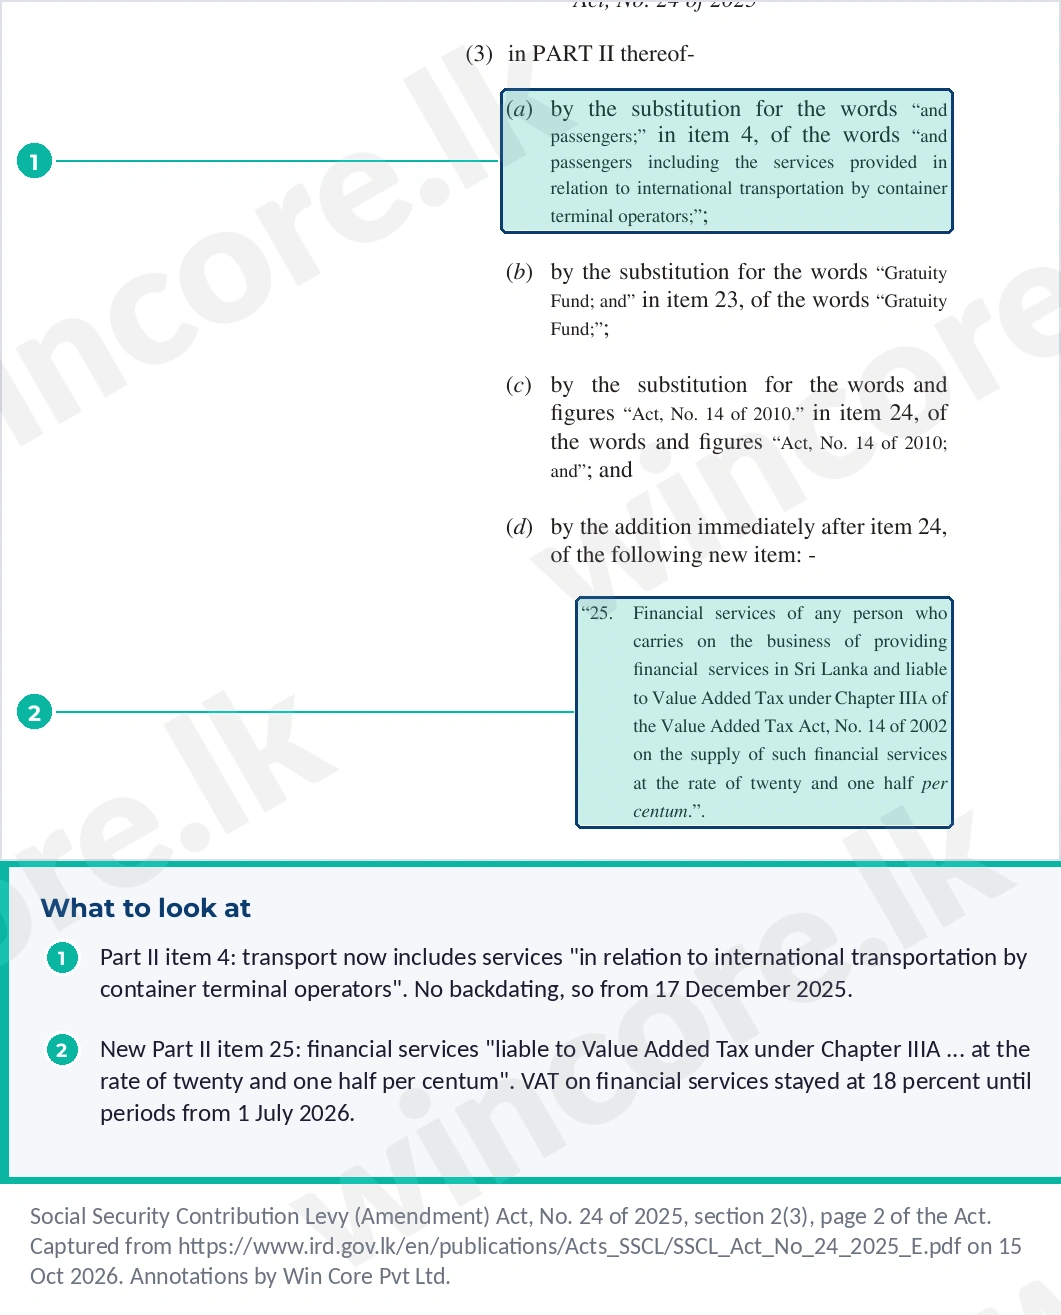
- Container terminals, from 17 December 2025. Part II item 4, transport of goods and passengers, now includes "the services provided in relation to international transportation by container terminal operators" [3]. The IRD notice gives 17 December 2025 [5].
- Financial services at 20.5 percent. New Part II item 25 exempts the financial services of a person "liable to Value Added Tax under Chapter IIIA ... at the rate of twenty and one half per centum" [3].
Did banks stop paying SSCL on 17 December 2025? On our reading, no. Item 25 took effect that day, but VAT on financial services stayed at 18 percent for periods ending by 30 June 2026 and became 20.5 percent only from 1 July 2026, under section 7 of the VAT Amendment Act No. 14 of 2026 [8]. Until then the exemption had nothing to bite on. The IRD notice of 16 January 2026 describes item 25 without giving a date [5].
SSCL amendment 2026: a lower threshold and a new vehicle rule
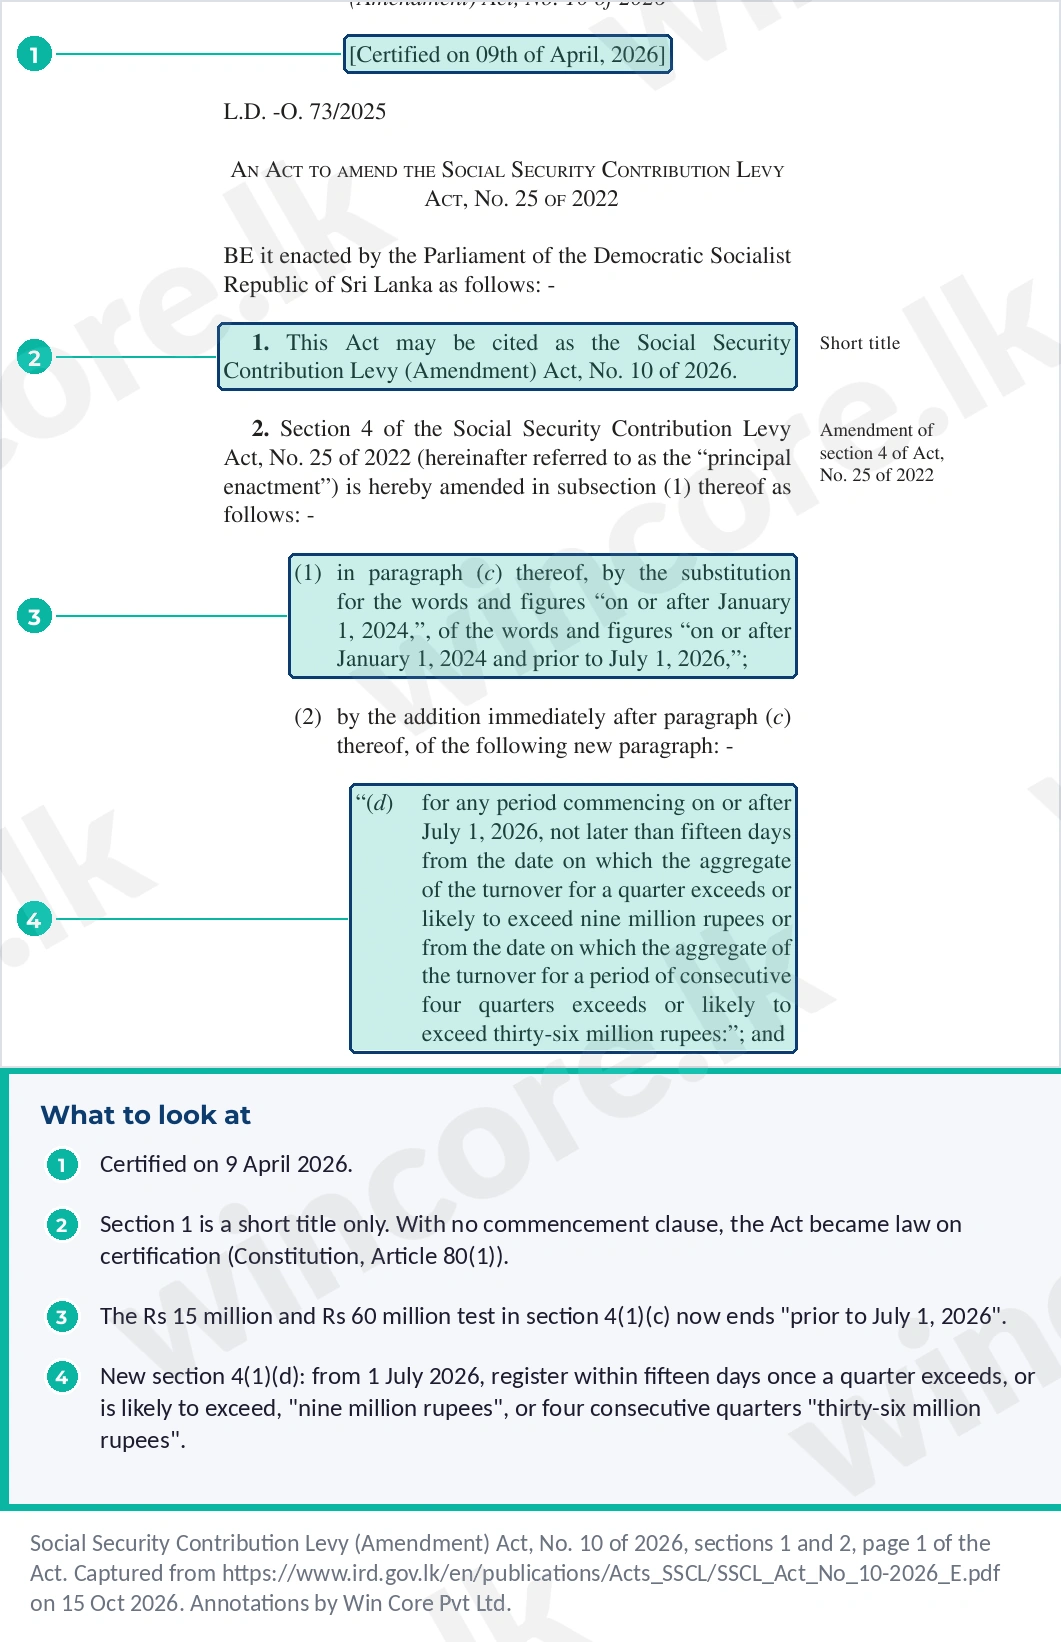
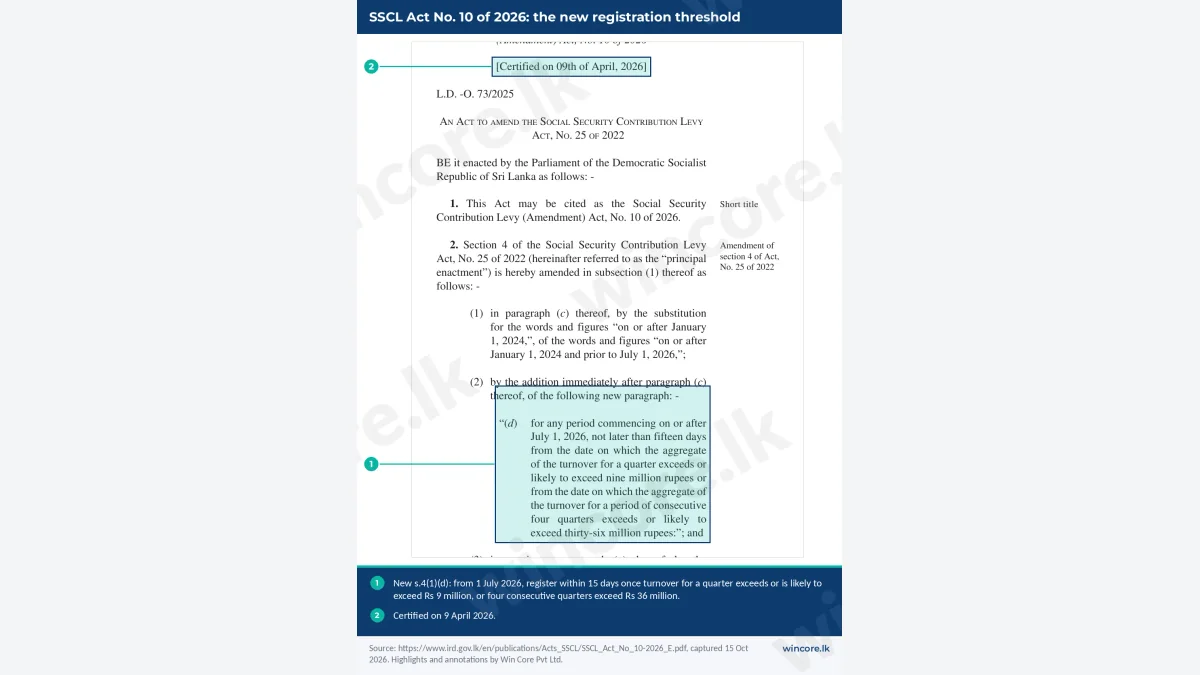
Act No. 10 of 2026 was certified on 9 April 2026 and published on 10 April 2026 [4]. With no commencement clause (section 1 is a short title only), it became law on certification under Article 80(1) [9]; the operative dates are in its clauses.
The threshold. Section 4(1)(c), the Rs 15 million a quarter or Rs 60 million over four quarters test, now ends "prior to July 1, 2026". New section 4(1)(d) applies "for any period commencing on or after July 1, 2026": register within fifteen days of the date turnover for a quarter "exceeds or likely to exceed nine million rupees", or turnover for four consecutive quarters exceeds or is likely to exceed "thirty-six million rupees" [4]. A person who only imports is outside section 4, because Customs collects their levy at the border under section 19 [2]. The test, the form and the fifteen days are in our guide to SSCL registration at Rs 9 million.
The threshold tests "turnover" as section 3(2) defines it, not liable turnover. A retailer with Rs 9.5 million of non-exempt sales in a quarter must register, even though only half of that is liable turnover. Exempt sales stay out of the count because they are outside the definition [1].
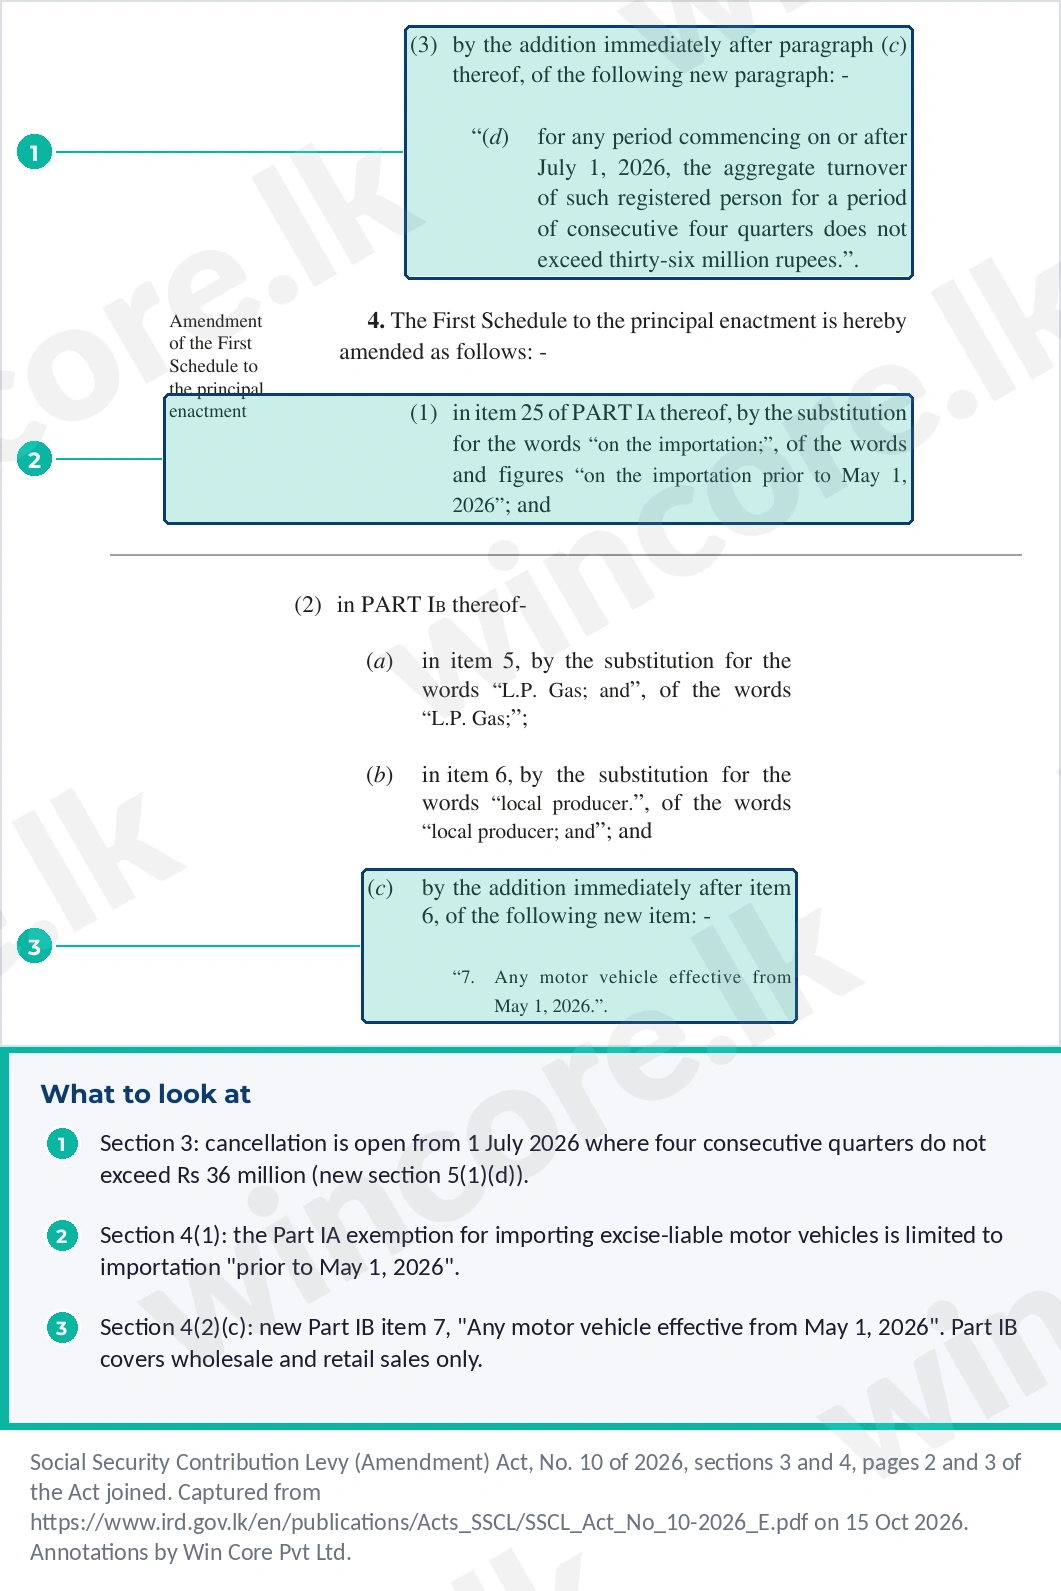
Cancellation. Section 3 adds section 5(1)(d): from 1 July 2026, a registered person whose turnover for four consecutive quarters "does not exceed thirty-six million rupees" may apply to cancel, after twelve months of registration [4] [2].
Motor vehicles. Section 4 limits the Part IA item 25 exemption for imported vehicles liable to excise duty to "the importation prior to May 1, 2026", and adds Part IB item 7: "Any motor vehicle effective from May 1, 2026" [4]. The IRD reads this as SSCL "at the point of importation from May 1, 2026" and a new exemption for "the wholesale and retail sale of any motor vehicles" [6].
Six exemption items changed, and no others
We read both amending Acts in full. Between them they change six First Schedule items; their other edits, to Part IB items 5 and 6 and Part II items 23 and 24, only move the word "and" [3] [4]:
| Item | Change | Operates from | Source |
|---|---|---|---|
| Part IA 24 | Power machinery exemption limited to CEB agreements before 18 Feb 2025 | 18 Feb 2025 (deemed) | Act 24/2025, s.1(3), s.2(1) |
| Part IB 4 | All sales of petrol, diesel, kerosene exempt | 1 Jul 2025 (deemed) | Act 24/2025, s.1(3), s.2(2) |
| Part II 4 | Container terminal services for international transport exempt | 17 Dec 2025 | Act 24/2025, s.1(2), s.2(3)(a) |
| Part II 25 | Financial services liable to VAT at 20.5 percent exempt | 17 Dec 2025 in law; bites from 1 Jul 2026 on our reading | Act 24/2025, s.2(3)(d); VAT Act 14/2026, s.7 |
| Part IA 25 | Vehicle import exemption ends | 1 May 2026 | Act 10/2026, s.4(1) |
| Part IB 7 | Wholesale and retail sale of any motor vehicle exempt | 1 May 2026 | Act 10/2026, s.4(2)(c) |
Our piece on SSCL at 2.56 percent on rent relies on Part II items 11 and 16, the VAT exclusion and the Rs 9 million test; nothing in either Act cuts across it.
The IRD web page is out of date
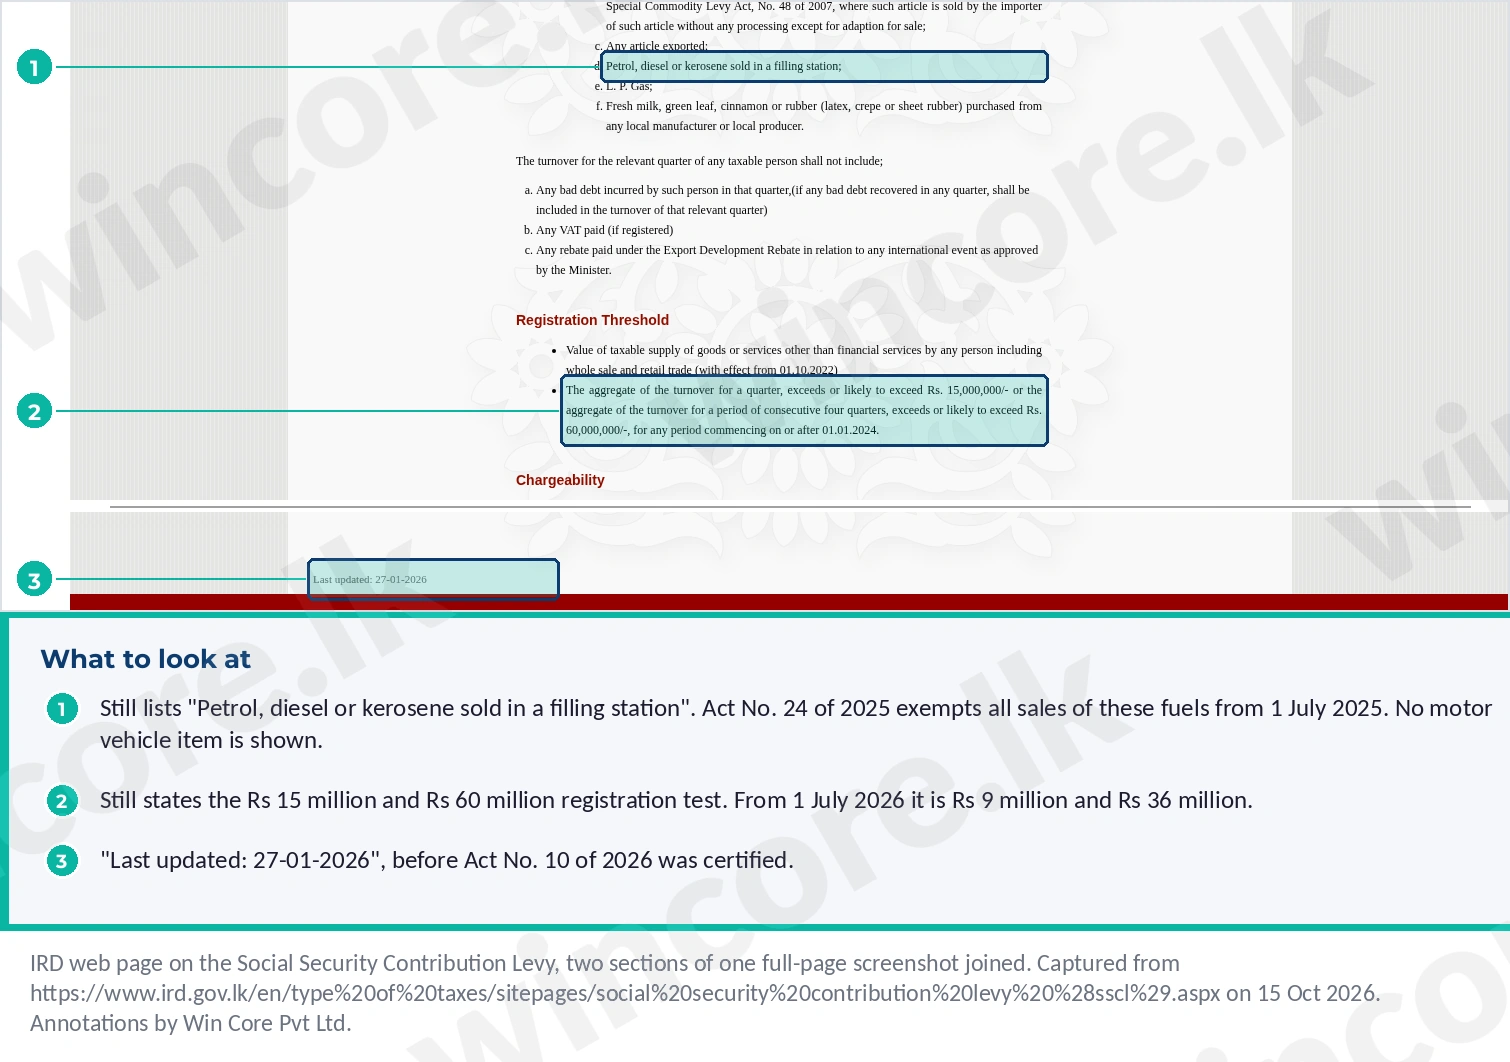
The IRD's SSCL page, "Last updated: 27-01-2026", still shows the Rs 15 million test, the filling station limit on fuel and no vehicle item [7]. Use the Acts.
No penalty changed: which section applies to which default
Neither amending Act changed a penalty.
| Default | Duty | Consequence |
|---|---|---|
| Levy not paid by the 20th (month by month, under s.17(1)) | s.17(2): "in default" | s.18(1): 10 percent of the amount in default, plus 2 percent a month if unpaid before the last day of the following month, capped at 100 percent; may be waived or reduced for special circumstances |
| Not registering | s.4(1) | s.46(a): fine up to Rs 25,000, or up to six months' imprisonment, or both |
| Return late, missing or not in the specified form | s.8(1) to (3) | s.8(8): administrative penalty up to Rs 50,000; s.46(c) offence for failing to furnish |
| False return or omission that evades levy | s.45 | On summary trial: twice the levy evaded, plus a sum up to Rs 25,000 or up to six months' imprisonment, or both |
A car imported in May bears SSCL at the port: a worked example
A hypothetical car importer with its own showroom imports a car liable to excise duty, with a VAT import value of Rs 10 million on 10 May 2026 and sells it in its showroom in June for Rs 13 million, VAT excluded.
- At the port, Part IA item 25 no longer applies, so Customs collects 2.5 percent of Rs 10 million, Rs 250,000, under section 19 [2] [4].
- In the showroom, the sale is exempt under Part IB item 7, so it adds nothing to the dealer's SSCL turnover [4].
- Had it imported and sold the same car before May 2026, the import was exempt and the sale bore 2.5 percent of 50 percent of Rs 13 million, Rs 162,500.
A car imported in April 2026 and sold in June 2026 escapes both: exempt at the port under the old item 25 and exempt in the showroom under item 7. That is our reading of the text, and the IRD notice does not address it [6]. Our VAT calculator strips VAT from a VAT inclusive price before you apply the 2.5 percent.
Open points we keep open
- The backdated narrowing. Part IA item 24 was narrowed from 18 February 2025 by an Act certified ten months later. Article 80(3) of the Constitution bars any challenge to a certified Act's validity. On our reading, Article 13(6) bars retroactive penalties for offences, not retroactive tax [9]. How levy will be collected on machinery already cleared exempt, and whether section 18 penalties run from the original dates, is not addressed in the IRD notice we have seen [5].
- Item 25 between December 2025 and June 2026. Our reading is that it had no effect before 1 July 2026. The IRD has not said so in terms.
- Vehicles in stock on 1 May 2026. On the text they bear no SSCL at either point.
- Cancellation cross-references. Section 5(2) and (3) still refer only to "paragraphs (a) and (b) of subsection (1)", not to the newer (c) and (d) [2]. We expect the IRD to apply (d), but the text was not updated.
- Below the threshold. Section 3 charges "every taxable person", while the duties to file and pay fall on registered persons. The IRD says a person who crosses the line "must pay SSCL for the liable turnover from that quarter onwards" [6]. The Act does not set out how the levy is collected from someone who never crosses the threshold.
What this means for you
- Re-test registration against Rs 9 million a quarter using turnover before the Second Schedule share, excluding VAT and exempt items. Register within fifteen days of the date the quarter crosses, or is likely to cross, the line. Our tax services team handles SSCL registration and returns.
- Banks and finance companies: check whether SSCL was stopped before 1 July 2026 on the strength of item 25.
- Power producers that signed with the CEB on or after 18 February 2025: review machinery imported or bought since then. The exemption was withdrawn retrospectively.
- Fuel distributors and container terminal operators: levy paid on turnover since made exempt is carried forward under section 36; ask for the returns to be altered under section 9(1)(c).
- Vehicle importers and dealers: split stock by import date around 1 May 2026, and note that a dealer whose remaining turnover is below Rs 36 million over four quarters may be able to cancel.
Checklist: documents needed
- Quarterly turnover workings since 1 July 2026, VAT and exempt items excluded, against Rs 9 million and Rs 36 million
- Monthly SSCL payment receipts, each by the 20th
- Sales of petrol, diesel or kerosene since 1 July 2025, and container terminal income since 17 December 2025
- For power producers, the date of any CEB agreement and machinery bought since 18 February 2025
- Vehicle stock lists split by import date around 1 May 2026, with Customs entries
- Returns to be altered under section 9(1)(c), with the excess to be carried forward under section 36
When reviewing an older turnover-tax file, distinguish historical Nation Building Tax assessments from current SSCL obligations.
FAQ
What changed in the SSCL amendment 2026?
Two Acts changed six exemption items and the threshold. Act No. 24 of 2025 exempted all fuel sales from 1 July 2025, container terminals, and financial services taxed at 20.5 percent VAT, and narrowed a power machinery exemption from 18 February 2025. Act No. 10 of 2026 moved vehicles to the port from 1 May 2026 and set Rs 9 million a quarter from 1 July 2026 [3] [4].
Is VAT included in SSCL turnover?
No. Section 3(3)(b) says turnover "shall not include" any VAT "paid for that relevant quarter", so the levy is worked out on the price before VAT. Bad debts incurred in the quarter and the Export Development Rebate are also left out, and exempt items in the First Schedule never enter turnover. Neither amending Act changed these exclusions [1] [2].
Is SSCL still 2.5 percent, and when is it paid?
Yes. Section 3(1) still charges 2.5 percent of liable turnover, and the Second Schedule share still varies by activity, from 100 percent for imports and services to 25 percent for a registered distributor. The levy is paid monthly: each month's amount is due by the 20th of the following month under section 17(1), and the return is quarterly [1] [2].
Do banks still pay SSCL on financial services?
Not on financial services liable to VAT at 20.5 percent, which on our reading means taxable periods from 1 July 2026. Item 25 of Part II has been law since 17 December 2025, but until 1 July 2026 the VAT rate on financial services was 18 percent, so the exemption had nothing to apply to. The IRD has not said so in terms [3] [8].
What happens to SSCL paid on turnover that became exempt backwards?
It is levy paid in excess. Section 36 treats it as an advance payment for the quarters that follow, so it is carried forward rather than lost. Fuel sellers since 1 July 2025 are the main case. Ask the Commissioner General in writing to alter the returns concerned under section 9(1)(c), and keep the workings that show the exempt turnover [2] [3].
Talk to us. If you would like us to check your SSCL registration, exemptions or past returns against the 2025 and 2026 amendments, book a consultation at our contact page.
WinCore Pvt Ltd
References
- Parliament of Sri Lanka. Social Security Contribution Levy Act, No. 25 of 2022, ss.2 and 3 and Second Schedule. https://www.ird.gov.lk/en/publications/Acts_SSCL/SSCL_Act_No.%2025_2022_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Social Security Contribution Levy Act, No. 25 of 2022, consolidated up to 2026 (26 May 2026), ss.4, 5, 7 to 10, 15 to 19, 36, 45 to 48 and 53 and First Schedule. https://www.ird.gov.lk/en/publications/Acts_SSCL/SSCL_Cons_Act_-_2026_Changes.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Social Security Contribution Levy (Amendment) Act, No. 24 of 2025, ss.1 and 2. https://www.ird.gov.lk/en/publications/Acts_SSCL/SSCL_Act_No_24_2025_E.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Social Security Contribution Levy (Amendment) Act, No. 10 of 2026, ss.1 to 4. https://www.ird.gov.lk/en/publications/Acts_SSCL/SSCL_Act_No_10-2026_E.pdf . Primary. Accessed 21 October 2026.
- Inland Revenue Department. Notice to the Taxpayers: Amendments to the Social Security Contribution Levy Act, SEC/PN/SSCL/2026-01 (16 January 2026). https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/750/SEC_PN_SSCL_2026-01_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Notice to the Taxpayers: Implementation of Changes to SSCL Act, PN/SSCL/2026-04/1 (16 April 2026), items 1 and 2. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/780/PN_SSCL_2026-04_1_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Social Security Contribution Levy (SSCL) web page ("Last updated: 27-01-2026"; cited to show it is out of date). https://www.ird.gov.lk/en/type%20of%20taxes/sitepages/social%20security%20contribution%20levy%20%28sscl%29.aspx . Primary (outdated). Accessed 21 October 2026.
- Parliament of Sri Lanka. Value Added Tax (Amendment) Act, No. 14 of 2026, ss.7, 12 and 13. https://www.ird.gov.lk/en/publications/Value%20Added%20Tax_Acts/VAT_Act_No_14-2026_E.PDF . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. The Constitution of the Democratic Socialist Republic of Sri Lanka (Revised Edition 2023), Articles 13(6), 80(1) and 80(3). https://www.parliament.lk/files/pdf/constitution.pdf . Primary. Accessed 15 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
SSCL registration now starts at Rs 9 million a quarter or Rs 36 million a year from 1 July 2026. How to test, register and pay monthly.
The VAT registration tests are Rs 15 million a quarter or Rs 60 million over 12 months. How the tests run, the 15 day rule and who must register.
A Budget speech proposes and does not change the law. What the 12 November 2026 proposals could mean for companies and employers, and when they apply.