
TIN certificate from 1 November 2026, and TINs for new companies and every employee
From 1 November 2026 individuals need a TIN certificate for eight transactions. Who needs one, how to get it, and TINs for companies and staff.
On this page
Last verified against the primary sources on 28 October 2026.
Updated 28 October 2026: rechecked IRD Circular SEC/2026/E/07 and the IRD notices page; the certificate rule applies from 1 November 2026 and no later IRD notice changes it.
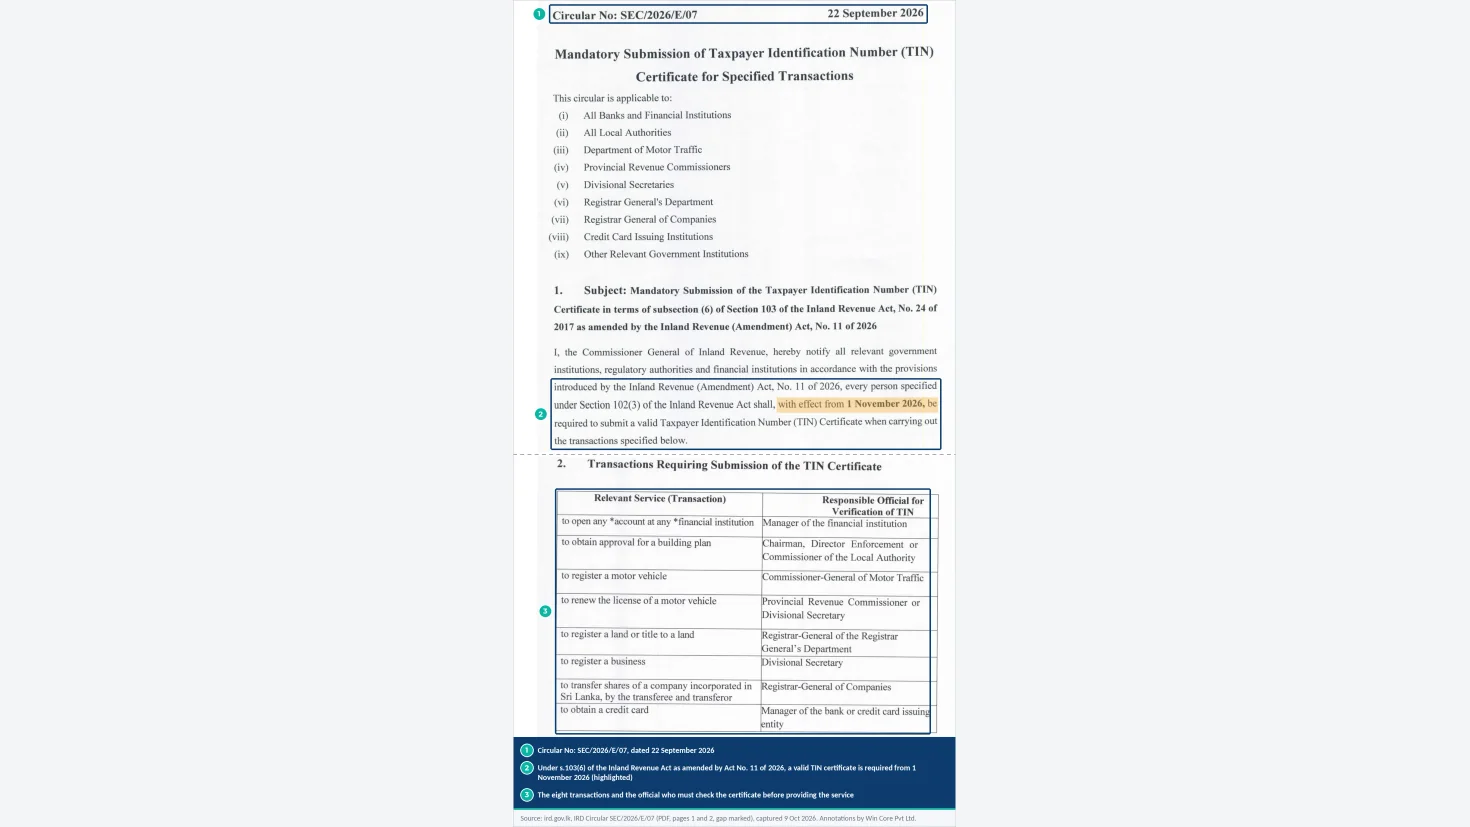
From 1 November 2026 the Taxpayer Identification Number (TIN) stops being something you quote on a tax return and becomes a ticket you show at a gate. The IRD has named eight gates: a bank or finance company opening an account, a local authority approving a building plan, the Commissioner-General of Motor Traffic registering a vehicle, the licensing office renewing a vehicle licence, the Registrar-General's Department registering land, the Divisional Secretary registering a business, the Registrar of Companies recording a share transfer, and a card issuer approving a credit card [1]. Each gate has a named gatekeeper, and each gatekeeper has been told not to let a resident adult through without a valid TIN certificate [1].
The framework is simple. Work out who needs a ticket, get the ticket before you reach the gate, and know which of three things the gatekeeper will accept. The difficulty is in the people around you who also need tickets: co-founders, directors, a shareholder selling out, and new employees.
A hypothetical case: a newly incorporated architecture practice plans to open its bank account, take a share transfer from a founder who is stepping back, and hire its first six staff, all in November. The company itself is exempt from the certificate rule, because the rule applies to individuals [1]. But the company still needs its own TIN within thirty days of incorporation [2]; both individuals on the share transfer need certificates [1]; and every employee whose APIT is deducted must appear with a TIN on the annual APIT statement, or that line is rejected [11]. Three different rules, one month. The steps below take them in order.
Step 1. Understand what changes on 1 November 2026
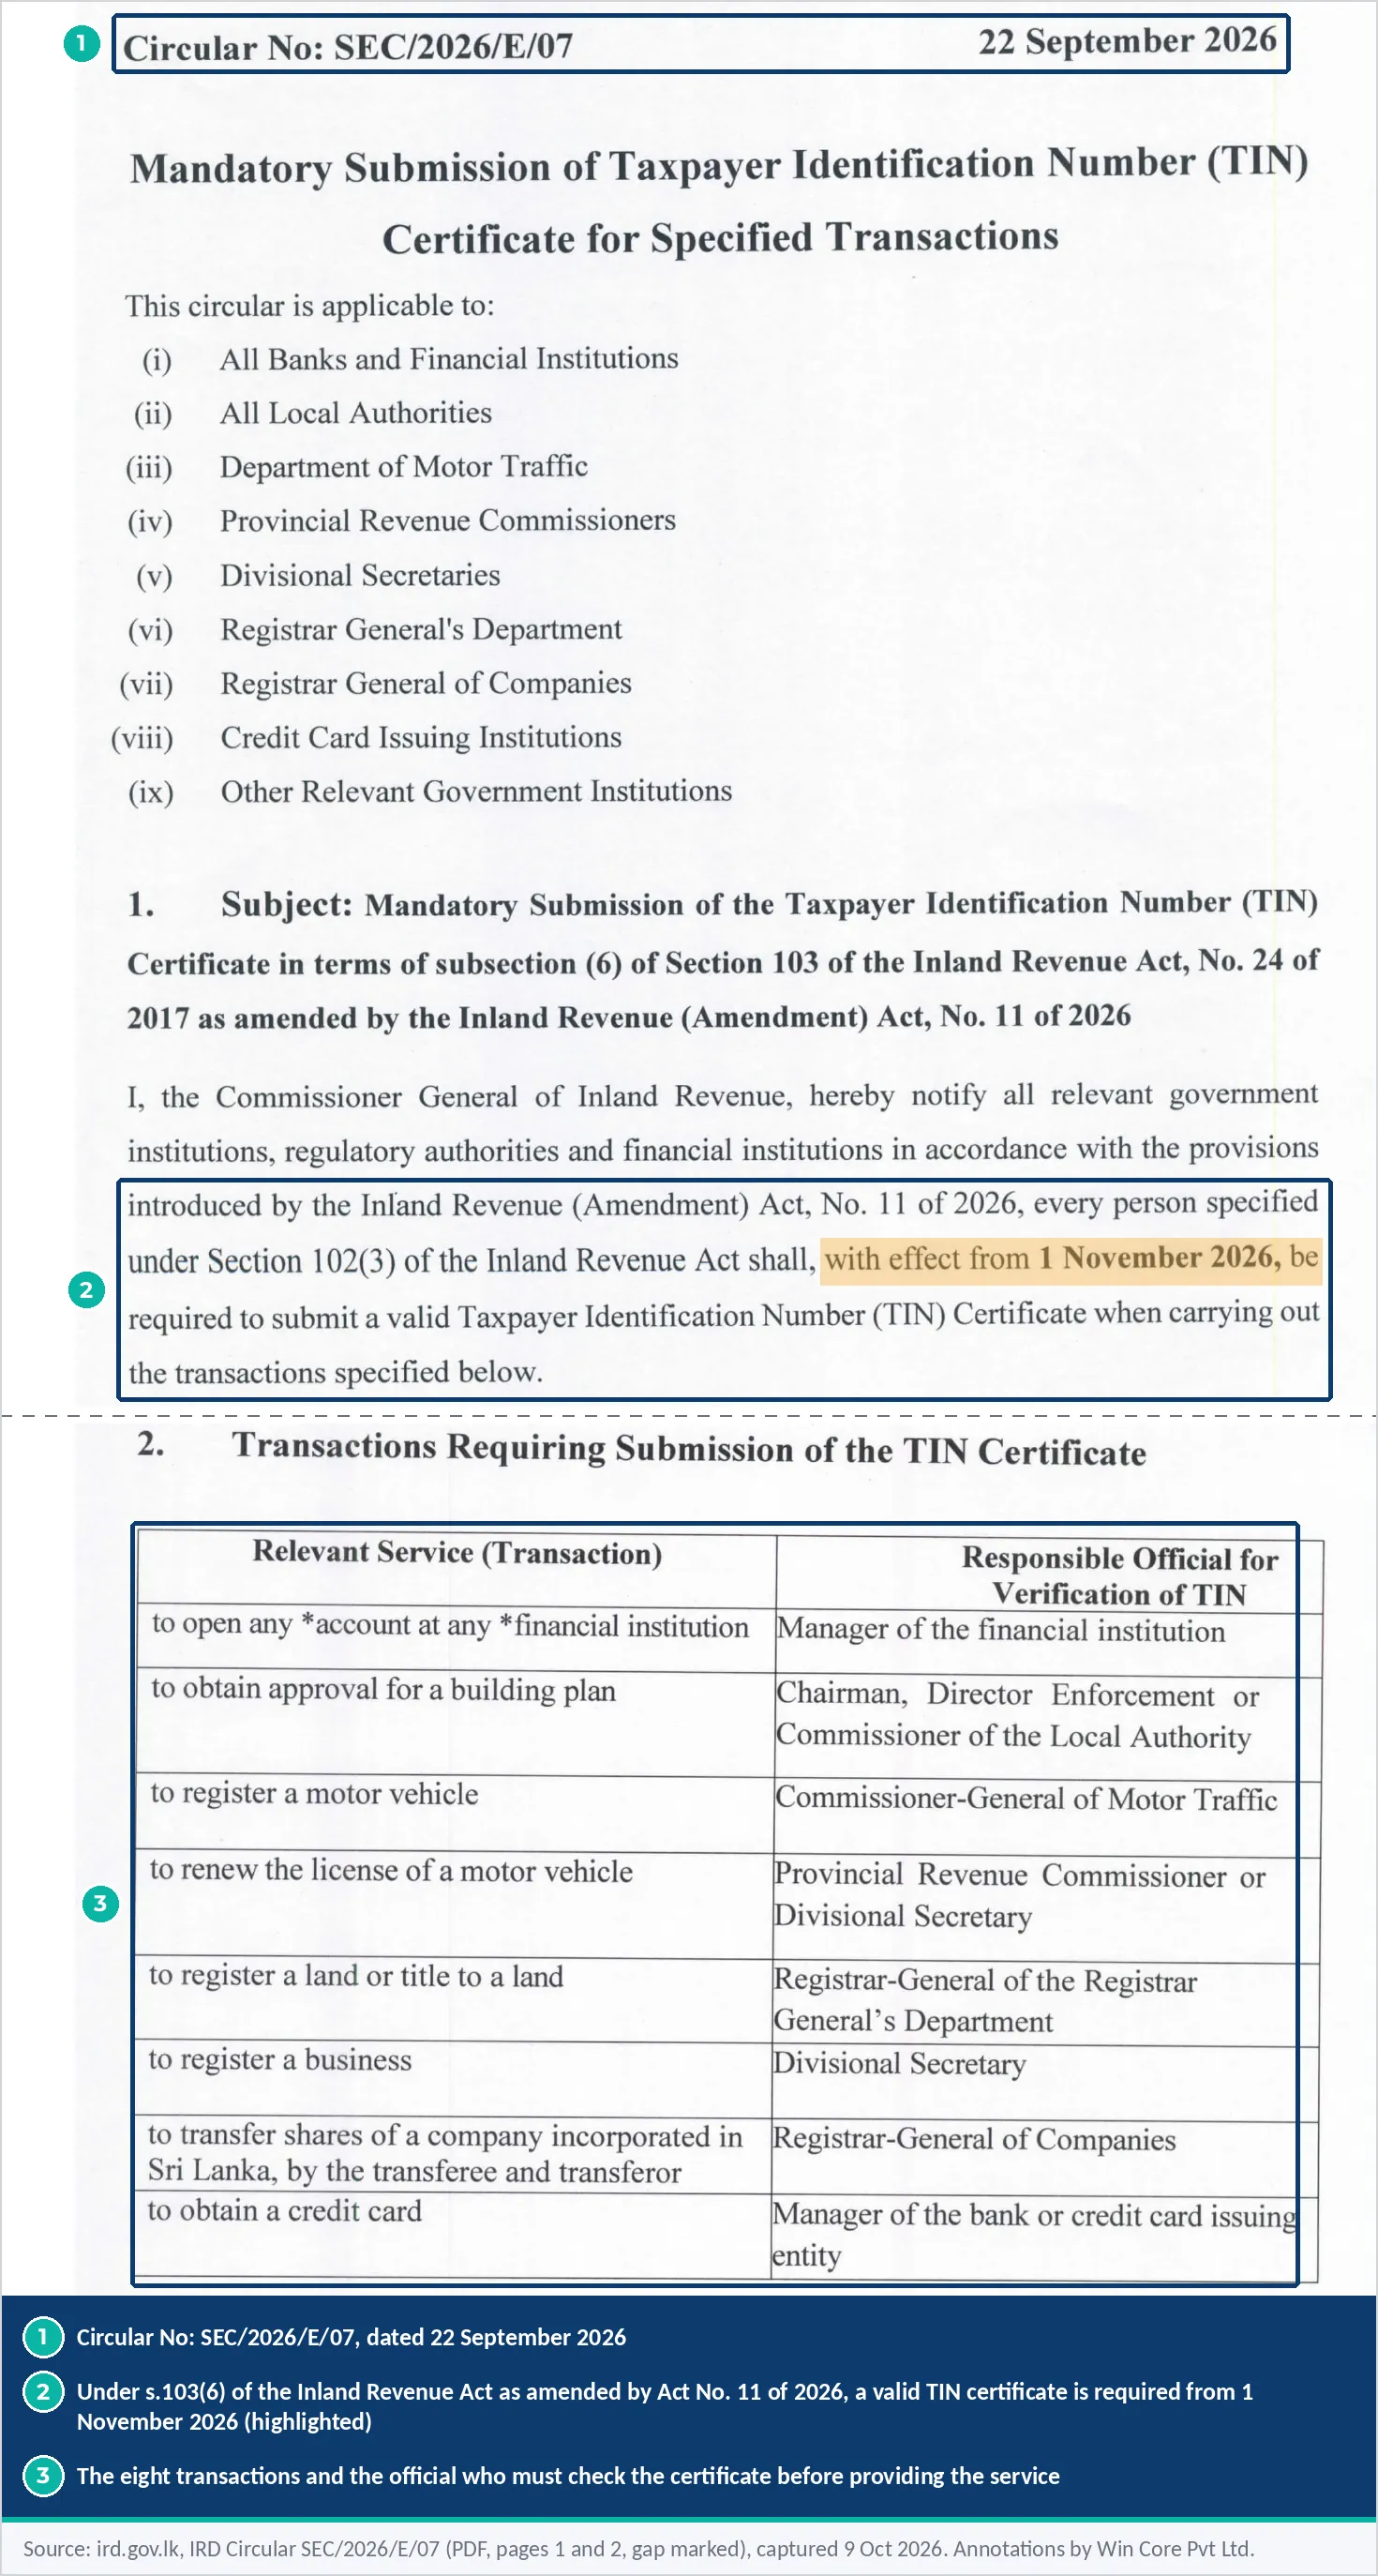
What to do. Under section 103(6) of the Inland Revenue Act, inserted by the Inland Revenue (Amendment) Act No. 11 of 2026, the Commissioner-General issues a TIN certificate to every person who has a TIN, and a person in a class specified under section 102(3) must produce it for the listed transactions [2]. Circular SEC/2026/E/07 of 22 September 2026 sets the start date: "The procedure shall take effect from 1 November 2026" [1].
The eight transactions are: opening any account at a financial institution (savings, current, term deposit or any other deposit account, with each joint holder treated separately); building plan approval; registering a motor vehicle; renewing a motor vehicle licence; registering land or title; registering a business; transferring shares in a Sri Lankan company, by both the transferee and the transferor; and obtaining a credit card [1]. The officials must ask for the certificate, verify it and keep a record [1].
Where. On ird.gov.lk under Publications, Circulars; the IRD's public notice SEC/PN/IT/2026/05 of 22 September 2026 repeats it for taxpayers [4].
What you need. Nothing yet. This step is about knowing which of your November plans pass through a gate.
What goes wrong. People read "TIN required" as a company rule. It is not: the circular exempts any entity other than an individual, including companies, partnerships, trusts and NGOs [1]. The second mistake is the date. The Act's own text says "with effect from April 1, 2026" [2], while the circular enforces from 1 November 2026 [1]. In practice the gatekeepers follow the circular, so plan for 1 November and do not assume anyone was checking before it.
How long. Ten minutes to read the circular.
Instrument: Inland Revenue Act No. 24 of 2017, s.103(6) to (8), inserted by Inland Revenue (Amendment) Act No. 11 of 2026; IRD Circular SEC/2026/E/07. Official link: Circular SEC/2026/E/07. Last verified: 9 Oct 2026.
Step 2. Work out who needs a ticket
What to do. Go through each person involved and ask two questions: are they a resident individual, and are they 18 or over? The circular states that obtaining a TIN is mandatory for resident individuals who were 18 or older on 31 December 2023, or who turn 18 on or after 1 January 2024, under Extraordinary Gazette 2334/21 of 31 May 2023 [1]. The Gazette itself, made under section 102(3), covers "resident persons" and, from 1 January 2024, every individual aged 18 or over [19]. The IRD's 2024 notice on that Gazette explains residence by reference to the 183-day test and says Sri Lankan non-residents are not required to register [10].
The certificate is not required from: anyone under 18; a non-resident individual; an individual whose registration was refused, with a refusal letter; persons with diplomatic privileges; and any entity other than an individual [1]. A non-citizen who has been in Sri Lanka for less than 183 days at the date of the transaction may be treated as non-resident. Any other individual claiming non-resident status must produce an IRD confirmation of residence status, requested by email to itp@ird.gov.lk [1].
Where. Your own records: NIC copies, passports and arrival dates.
What you need. A list of every director, shareholder, proprietor and employee who will be at a gate after 1 November.
What goes wrong. Non-citizens who have been here more than 183 days assume they are exempt. Under the circular they need the IRD's residence confirmation to claim it [1]. Leave time for that email.
How long. An hour for a small company, longer if residence status is unclear.
A brief aside, because it changes how people behave at the gate. Many people treat their TIN as if it were a PIN. The Act now says plainly that "a TIN shall not be a secret or confidential information" [2]. The PIN is the secret; the TIN is the ticket, and a ticket is meant to be shown. That is why the next step starts with simply finding out whether you already hold one.
Step 3. Check whether the person already has a TIN
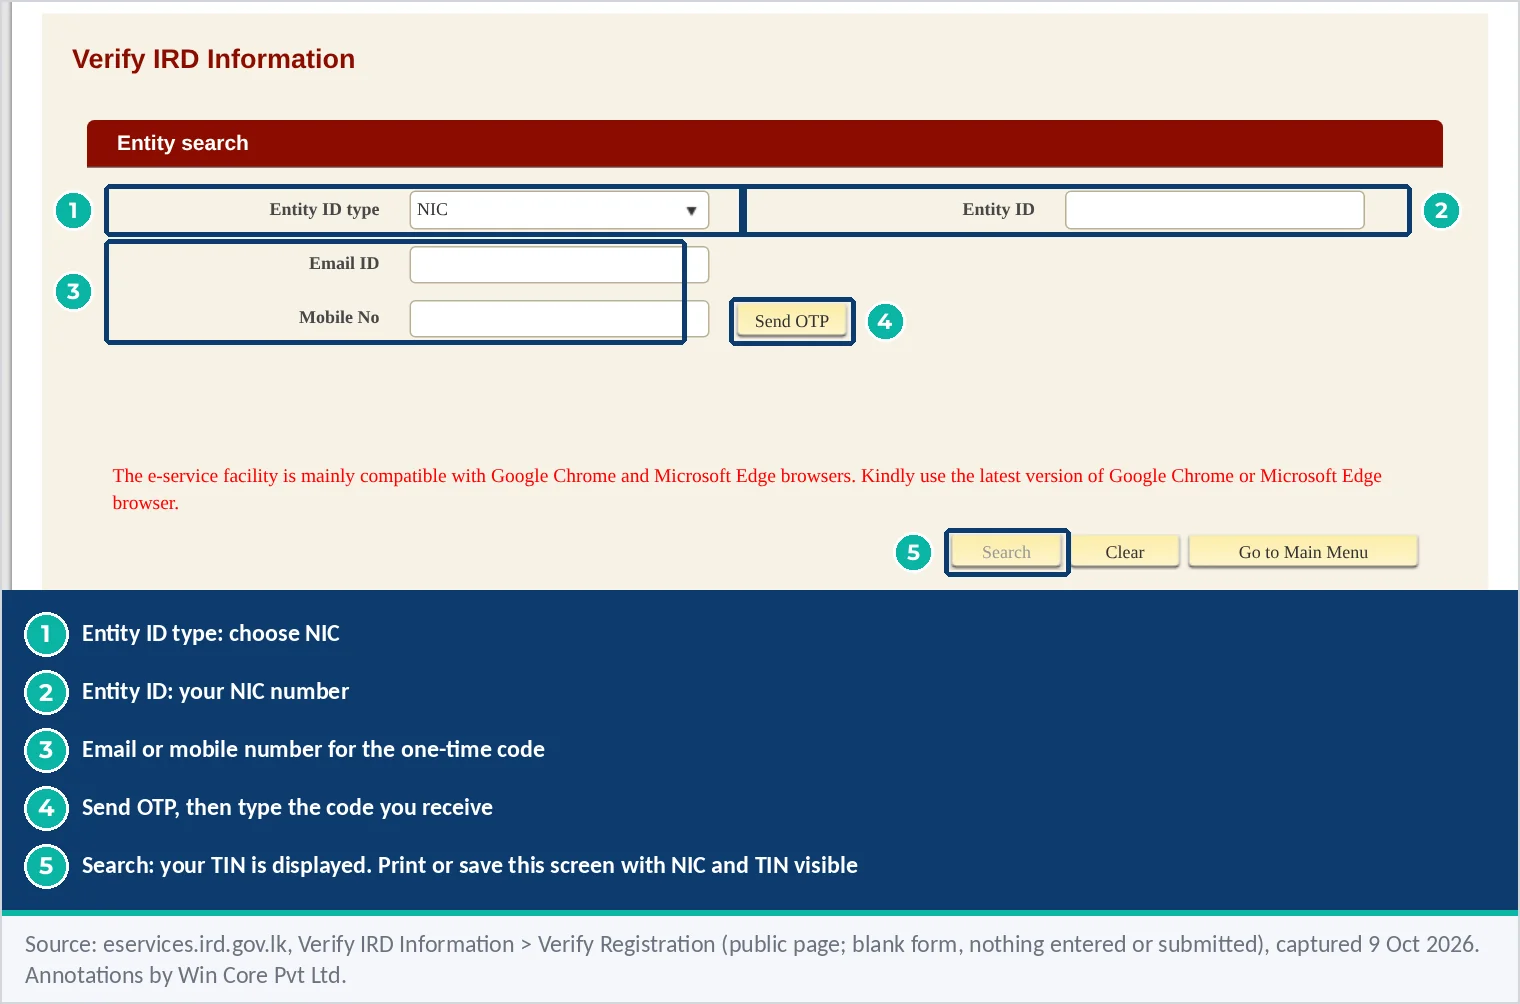
What to do. Many people already have a TIN without remembering it, and the IRD also registers people itself. The IRD's guide of 2 October 2026 sets out the route: ird.gov.lk, e-Services, Access to e-Services, Verify Authenticity of Registration, Verify Registration, then enter the NIC, a mobile number or email, request an OTP, enter it and search. The TIN is displayed [5].
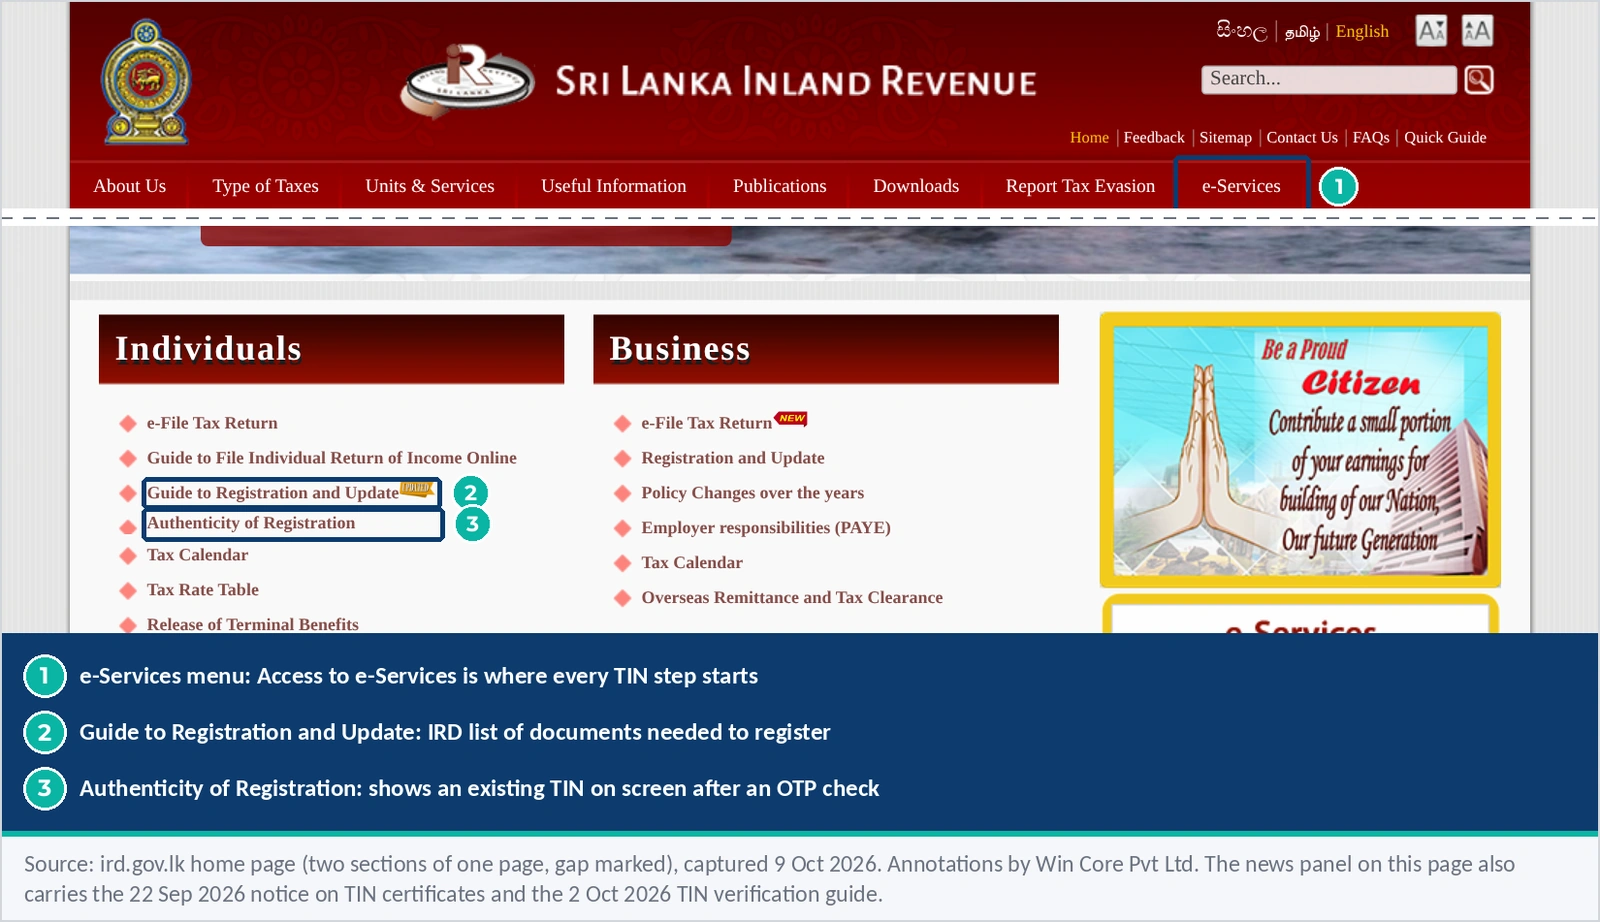
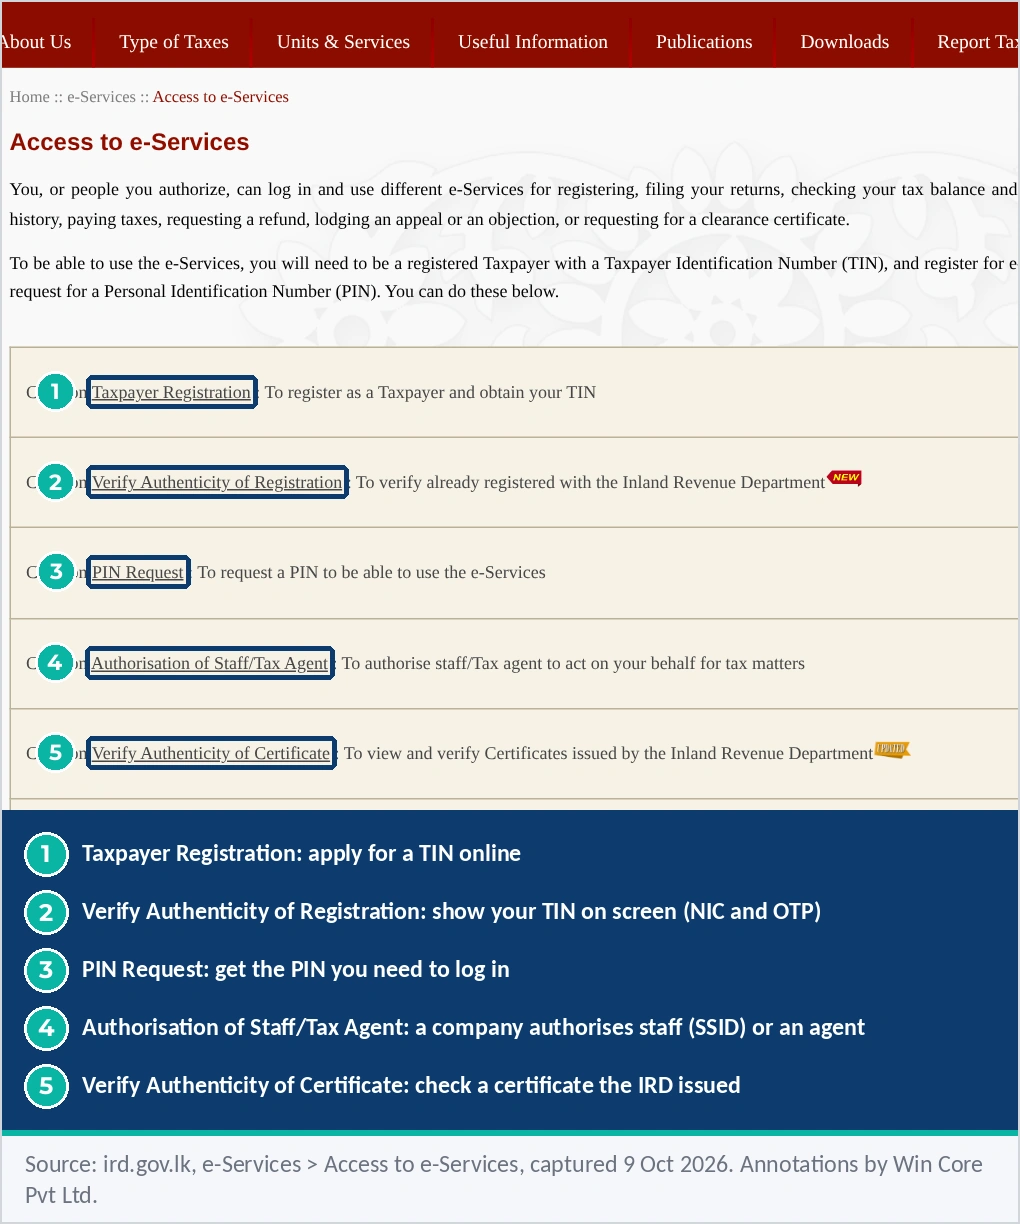
Where. Access to e-Services on ird.gov.lk [17], which leads to Verify IRD Information on eservices.ird.gov.lk [4].
What you need. The person's NIC, and a mobile number or email address that can receive the OTP [5].
What goes wrong. Running the check on someone else's NIC without them. The OTP goes to the person; ask them to run it and send you the result. If no TIN appears, go to Step 4.
How long. A few minutes once the OTP arrives.
Step 4. Apply for an individual TIN
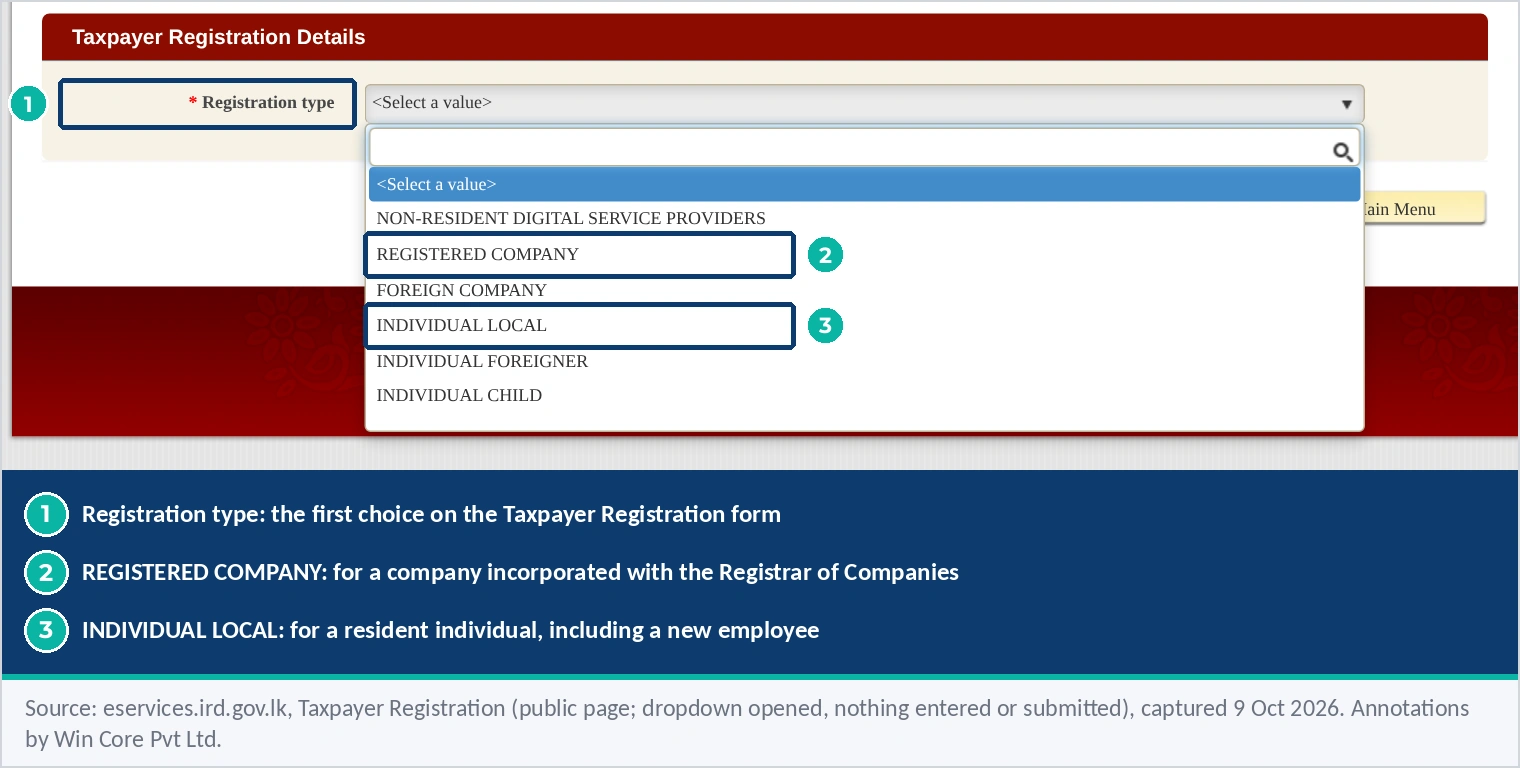
What to do. Register as a taxpayer online. The IRD's notice says anyone over 18 can obtain a TIN through the Taxpayer Registration link [4] [5]. Choose INDIVIDUAL LOCAL as the registration type for a resident Sri Lankan. The IRD's quick guide walks through each screen, from particulars and address to document upload and submission, after which an acknowledgement number is shown [7].
Where. e-Services, Access to e-Services, Taxpayer Registration [4]. Walk-in help is available at the Taxpayer Services Unit and the call centre on 1944 [7].
What you need. NIC (or passport for a foreign national); business registration certificate if a sole proprietorship is to be added; and proof of address, such as a utility bill, bank statement or Grama Niladhari certificate, if the address differs from the NIC [6].
What goes wrong. An address proof that does not match the address typed in, or the wrong registration type (the list also offers INDIVIDUAL FOREIGNER and INDIVIDUAL CHILD).
How long. Thirty minutes to complete the form. The IRD does not publish a processing time for TIN applications, so apply well before the transaction date.
Instrument: Inland Revenue Act No. 24 of 2017, ss.102 and 103; Extraordinary Gazette 2334/21 of 31 May 2023, Part B; IRD notice SEC/PN/IT/2026/05; IRD guide of 2 October 2026. Official link: IRD notice SEC/PN/IT/2026/05. Last verified: 9 Oct 2026.
Step 5. Register a new company within 30 days of incorporation
What to do. A company does not inherit a founder's TIN and does not need a TIN certificate for the eight transactions, but it must register with the IRD. Since 3 June 2026, new section 102(1A) says: "Every company incorporated or registered in Sri Lanka, shall register with the Commissioner-General not later than thirty days from the date of such incorporation or registration" [2]. Older guidance that allowed three months from incorporation no longer matches the Act. Failing to register as section 102 requires carries a penalty of up to Rs 50,000 [3], and new section 185A lets the Commissioner-General give a 30-day notice and then prosecute, with a fine of up to Rs 400,000, up to six months' imprisonment, or both [2].
Is the TIN automatic on incorporation? Not on the IRD's own guidance. The IRD tells companies to register through Taxpayer Registration, choosing REGISTERED COMPANY and adding each director by TIN, NIC or passport [6] [7]. What is automatic is the next step: once a company has its TIN, corporate income tax is registered automatically [6]. VAT, SSCL and APIT are separate registrations if they apply.
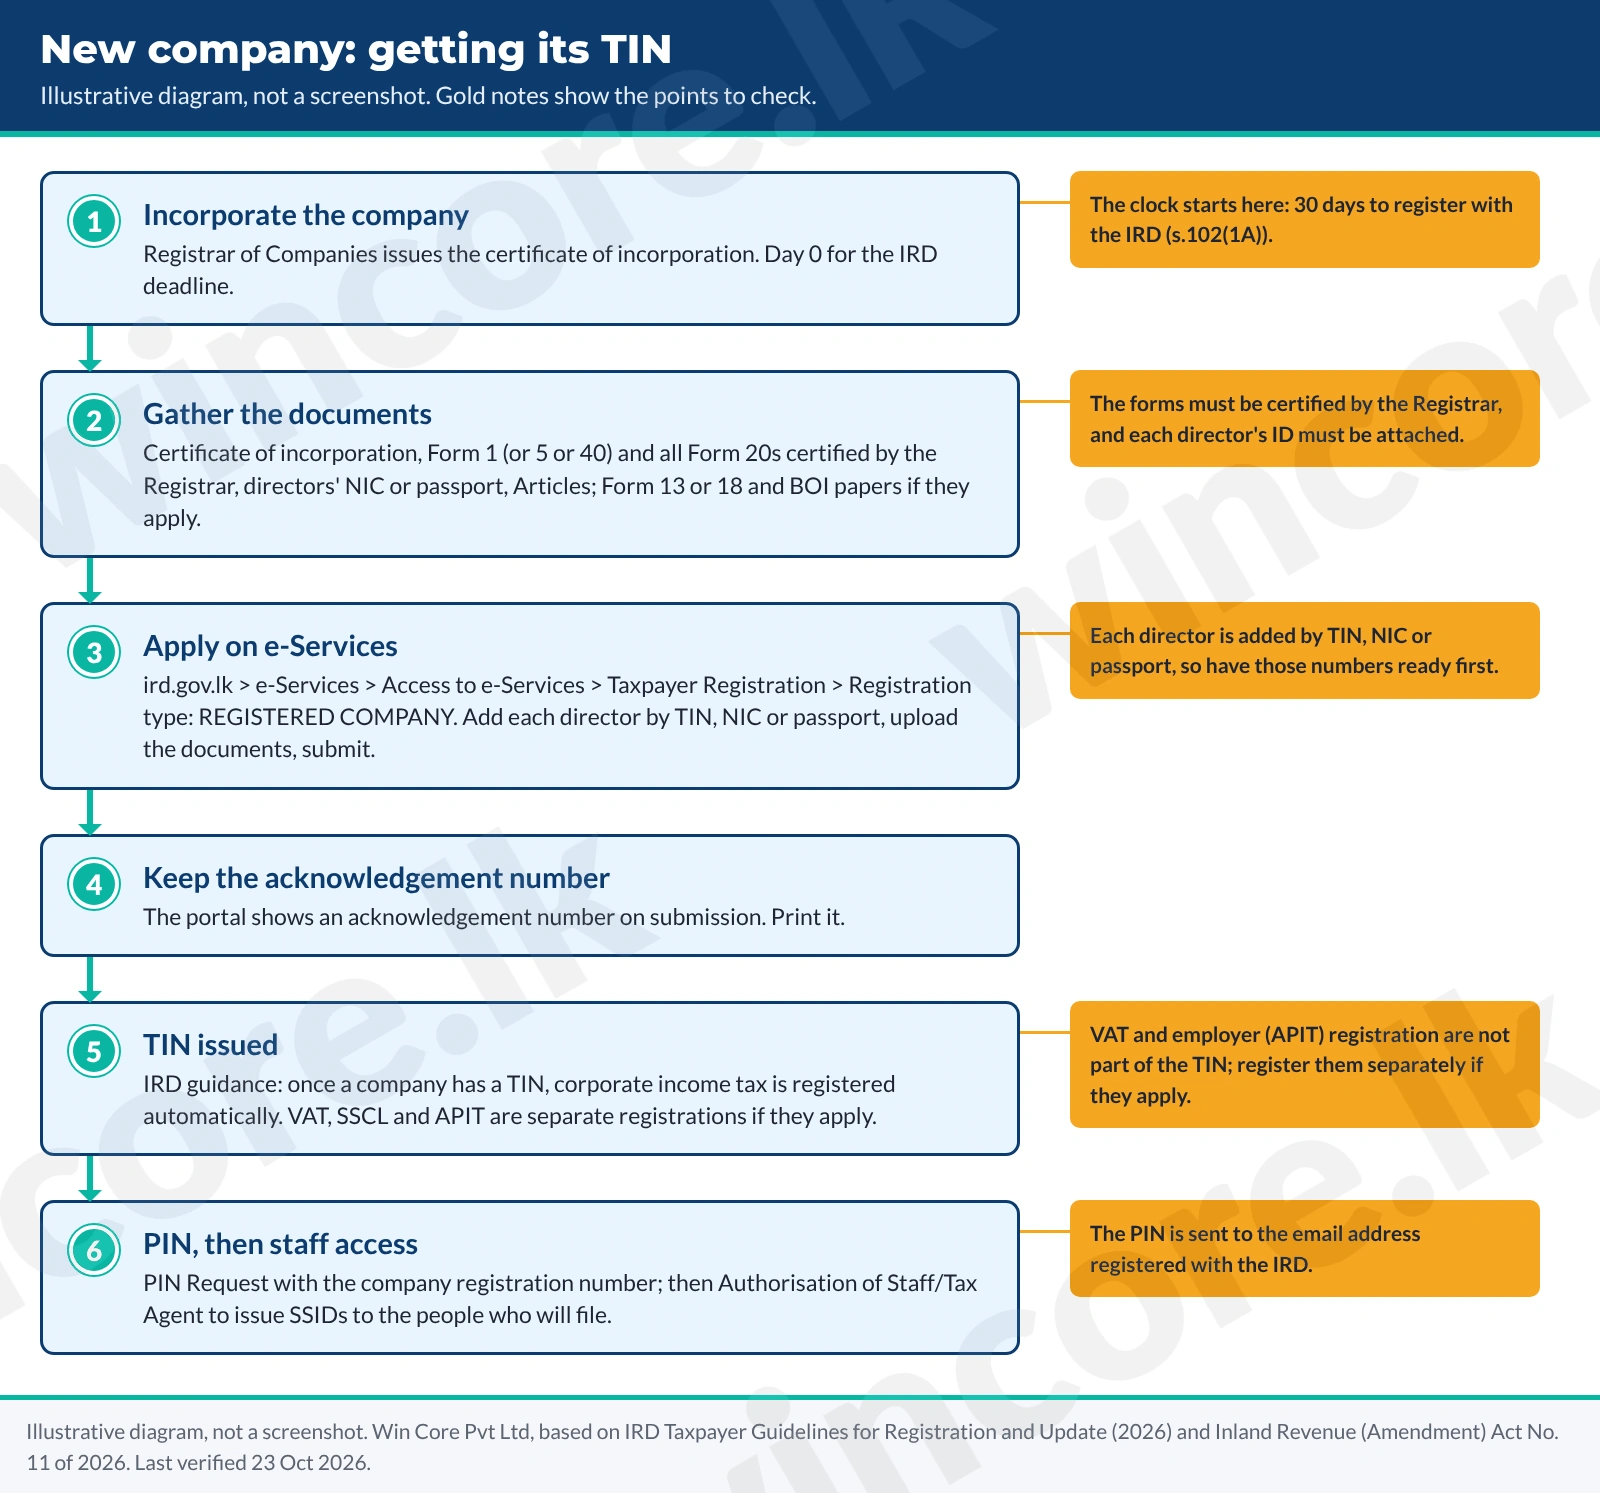
Where. e-Services, Taxpayer Registration, registration type REGISTERED COMPANY [7].
What you need. Certificate of incorporation; Form 1, 5 or 40 and all Form 20s, certified by the Registrar of Companies; NIC or passport of every director; Form 13 and Form 18 if they apply; Articles of Association; and the BOI certificate and agreement for a BOI company [6].
What goes wrong. Counting the 30 days from the first trading day instead of the date on the incorporation certificate. Uncertified copies of company forms. Directors without their own TIN, which holds up the company application at the "add director" screen. The incorporation forms, including beneficial ownership, come before this step.
How long. Half a day to assemble the pack if the Registrar's certified copies are in hand. The IRD processing time is not published.
Instrument: Inland Revenue Act No. 24 of 2017, s.102(1A) and s.185A, inserted by Act No. 11 of 2026; s.177. Official link: Inland Revenue (Amendment) Act No. 11 of 2026. Last verified: 9 Oct 2026.
Step 6. Set up access: PIN, and staff for a company
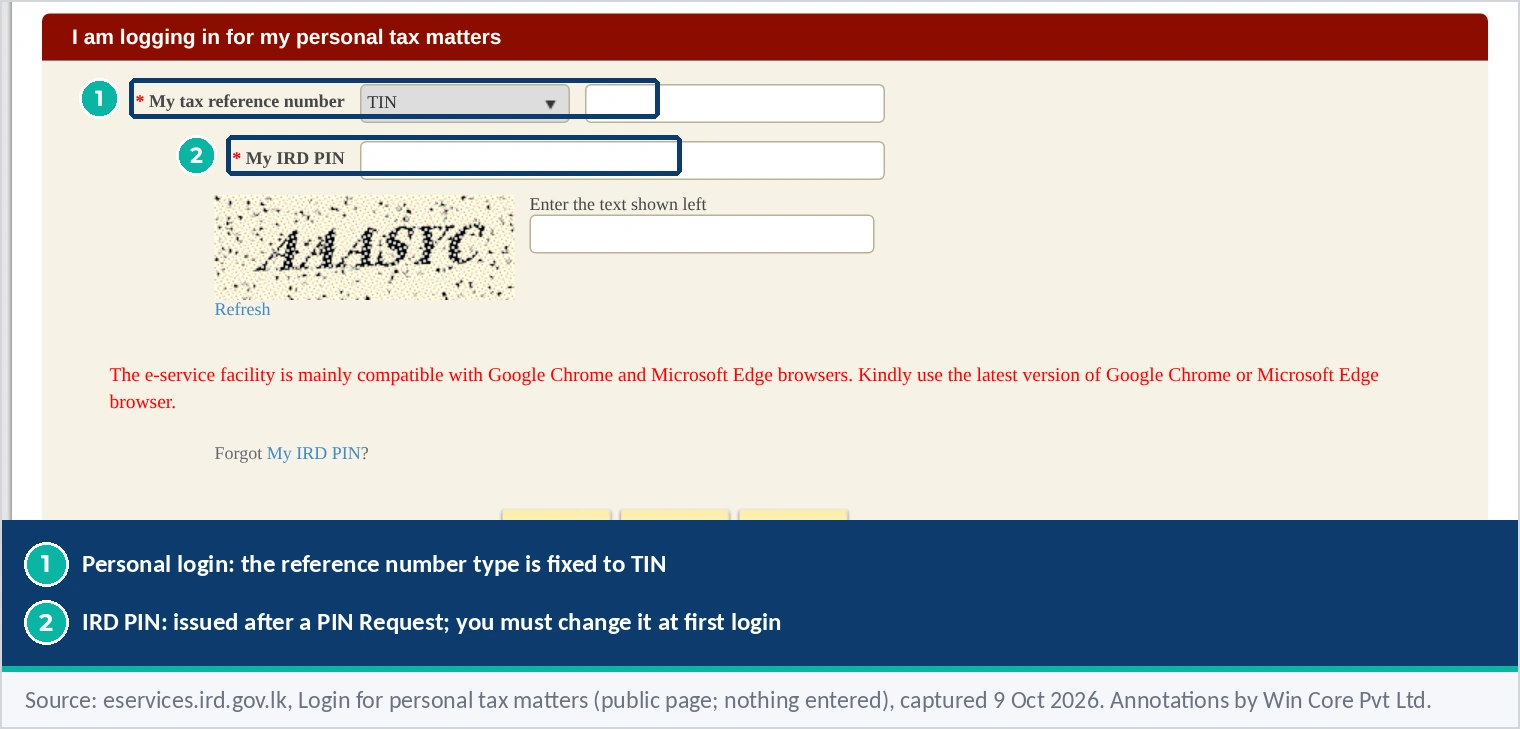
What to do. A TIN gets you registered; a PIN gets you in. Request a PIN through PIN Request. Individuals use their NIC or TIN; companies use the Registrar of Companies registration number [8]. The IRD's 2026 guide says the PIN is generated and sent to the registered email address immediately, with a postal option [6]. You are required to change it at first login [9]. For a company, staff and tax agents are then authorised through Authorisation of Staff/Tax Agent, and their staff IDs (SSIDs) arrive the following working day [6].
Where. e-Services, Access to e-Services, PIN Request; then the Authorisation of Staff/Tax Agent link (Figure 3).
What you need. NIC or TIN, or the company registration number. If a PIN is collected in person for a company, the IRD asks for a letter of authorisation [8].
What goes wrong. Making several PIN requests in a row, which the IRD's guide asks you to avoid [9].
How long. Minutes for an emailed PIN; the next working day for SSIDs [6].
Step 7. Employers: a TIN for every employee on the APIT statement
What to do. From the year of assessment 2025/2026 every employer registered for APIT must include each employee's TIN in Schedule 01 of the APIT Annual Statement, the list of employees whose APIT was deducted [11] [13]. The IRD's notice is blunt about the consequence: a record without a TIN "will be rejected by the RAMIS and such employee will not be able to get the credit on APIT deducted" [11]. The statement is filed electronically on or before 30 April [14], so the first statement under the rule, for 2025/2026, was due on 30 April 2026 [18]. For employees below the APIT threshold (Rs 150,000 a month), who go in Schedule 03, the guide asks for the TIN where the employee already has one [13]. They still fall under the general rule that resident adults must register [1].
If employees do not have TINs, the employer can ask the IRD to issue them. Notice SEC/PN/APIT/2026-02 says employers should send a formal request to the Commissioner, Forced Registration Unit, by email to inf@ird.gov.lk with employee details in the IRD's template [12]. The Forced Registration Unit is on the 11th floor of the IRD head office [16].
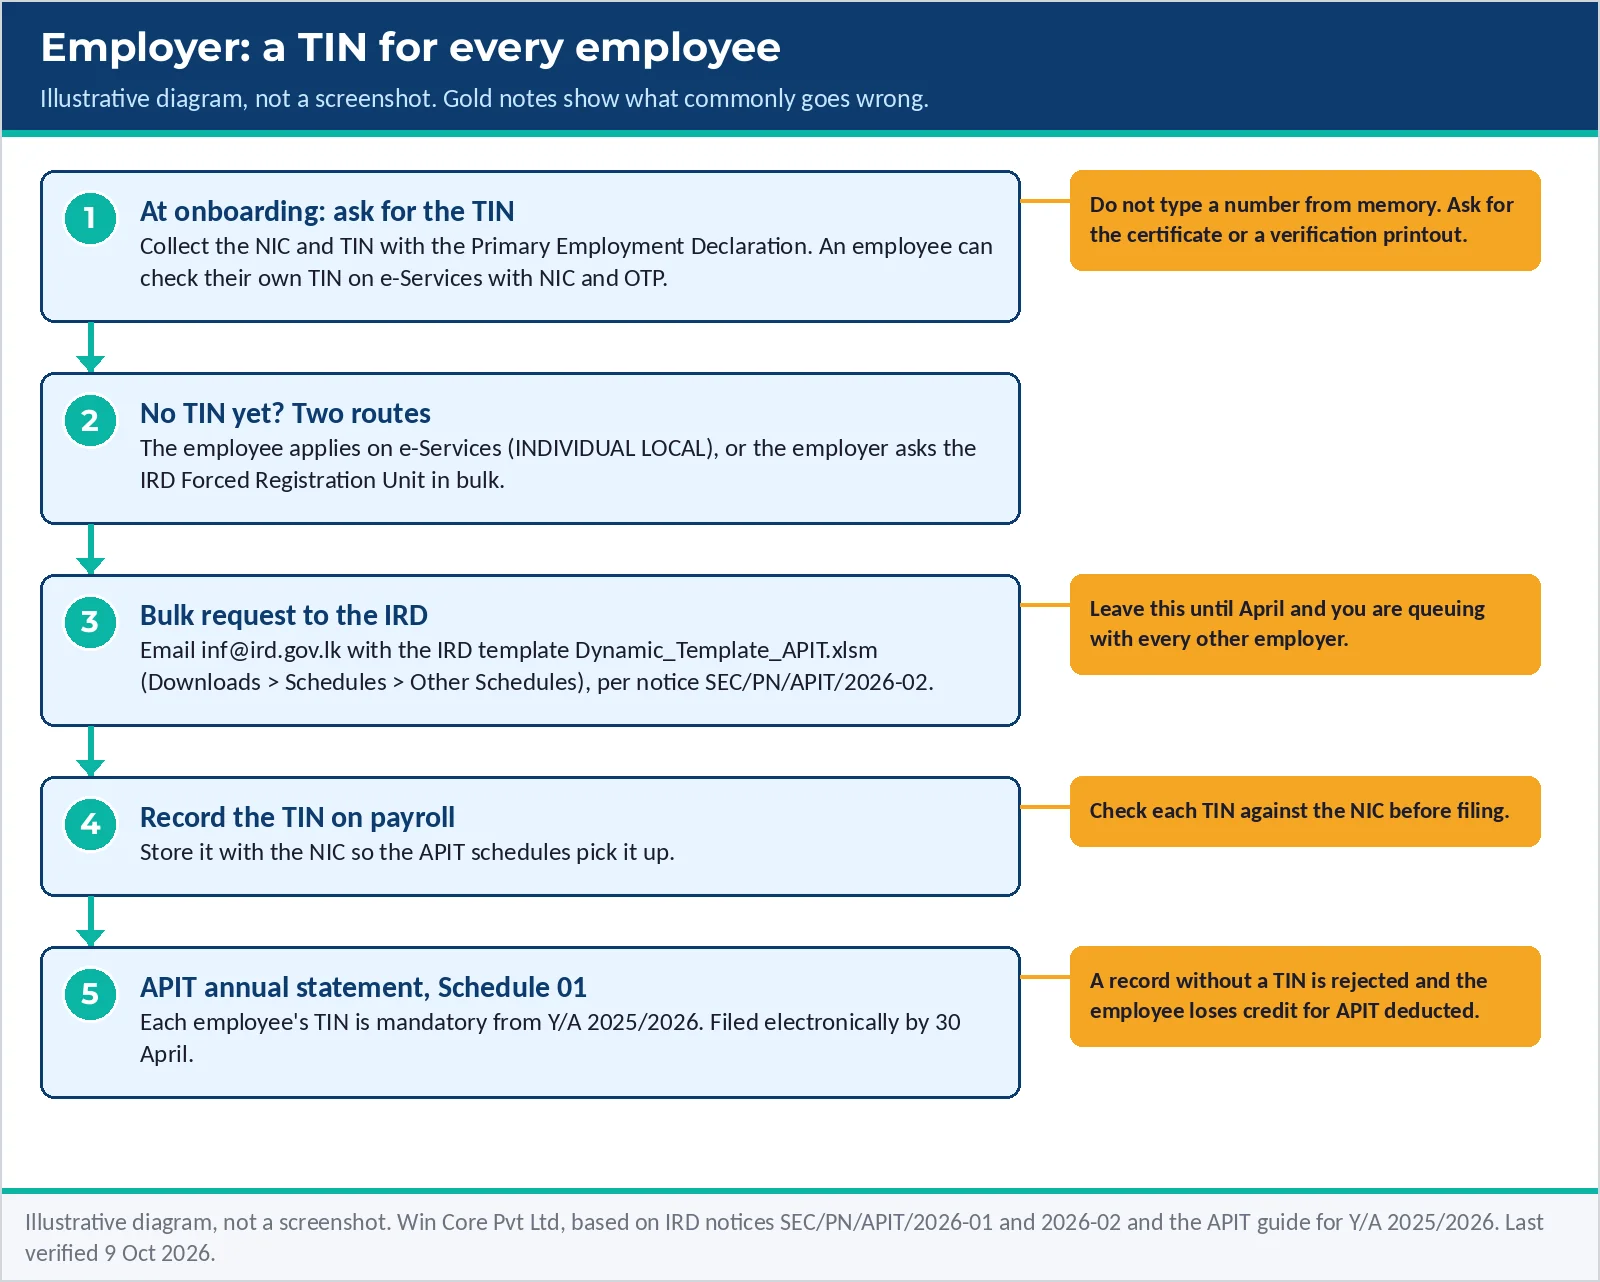
Where. The template is at www.ird.gov.lk, Downloads, Schedules, Other Schedules: Dynamic_Template_APIT.xlsm [12]. The Forced Registration Unit can be reached on 011 213 5171, 011 213 5179, 011 213 5174 and 011 213 5134 [12].
What you need. For each employee: full name, NIC, TIN if they have one, and a signed Primary Employment Declaration, which the IRD's APIT guideline says must be signed and dated by both employee and employer [15].
What goes wrong. Collecting TINs in April, when the statement is due. Copying a TIN from an old payslip without checking it against the NIC. Treating the Primary Employment Declaration as optional; without it the employer must apply Tax Table 07 instead of the primary employment tables [15]. For staff who join mid-year, our guide to APIT Table 05 for joiners and leavers covers the deduction itself, and our payroll service covers the rest of payroll set-up.
How long. Five minutes per employee at onboarding. The IRD does not publish a turnaround for bulk requests.
Instrument: Inland Revenue Act No. 24 of 2017, s.113(1B) (e-filing of the APIT statement); IRD notices SEC/PN/APIT/2026-01 and SEC/PN/APIT/2026-02; IRD Circular SEC/2025/E/01. Official link: Notice SEC/PN/APIT/2026-01 and Notice SEC/PN/APIT/2026-02. Last verified: 9 Oct 2026.
Step 8. Get the certificate, or the printout, and take it to the gate
What to do. Decide which of the three accepted forms you will carry. The circular accepts a photocopy of the TIN certificate; a printout of the e-Services verification screen showing the NIC number and TIN, as an alternative to the certificate; and soft copies of either [1]. The certificate itself is issued by the Commissioner-General on registration [1]. If you no longer have it, the verification printout from Step 3 is the fastest substitute: run the check, then print or save the screen with the NIC and TIN visible [1] [5].
Where. The verification screen (Figure 4). The IRD's specimen screen says that if you have not received the Taxpayer Registration Certificate, you may visit the IRD head office or the nearest metro or regional office [1]. The hotline is 1944 [1].
What you need. NIC, OTP access, and a printer or a PDF you can email.
What goes wrong. Showing up with the TIN number only, written on a slip. The circular asks for a certificate or the printout, and officials must verify it [1]. Producing a printout that crops off the NIC. For share transfers, remembering the buyer and forgetting the seller: both need one [1].
How long. Five minutes for the printout. A visit to an IRD office if you want the original certificate.
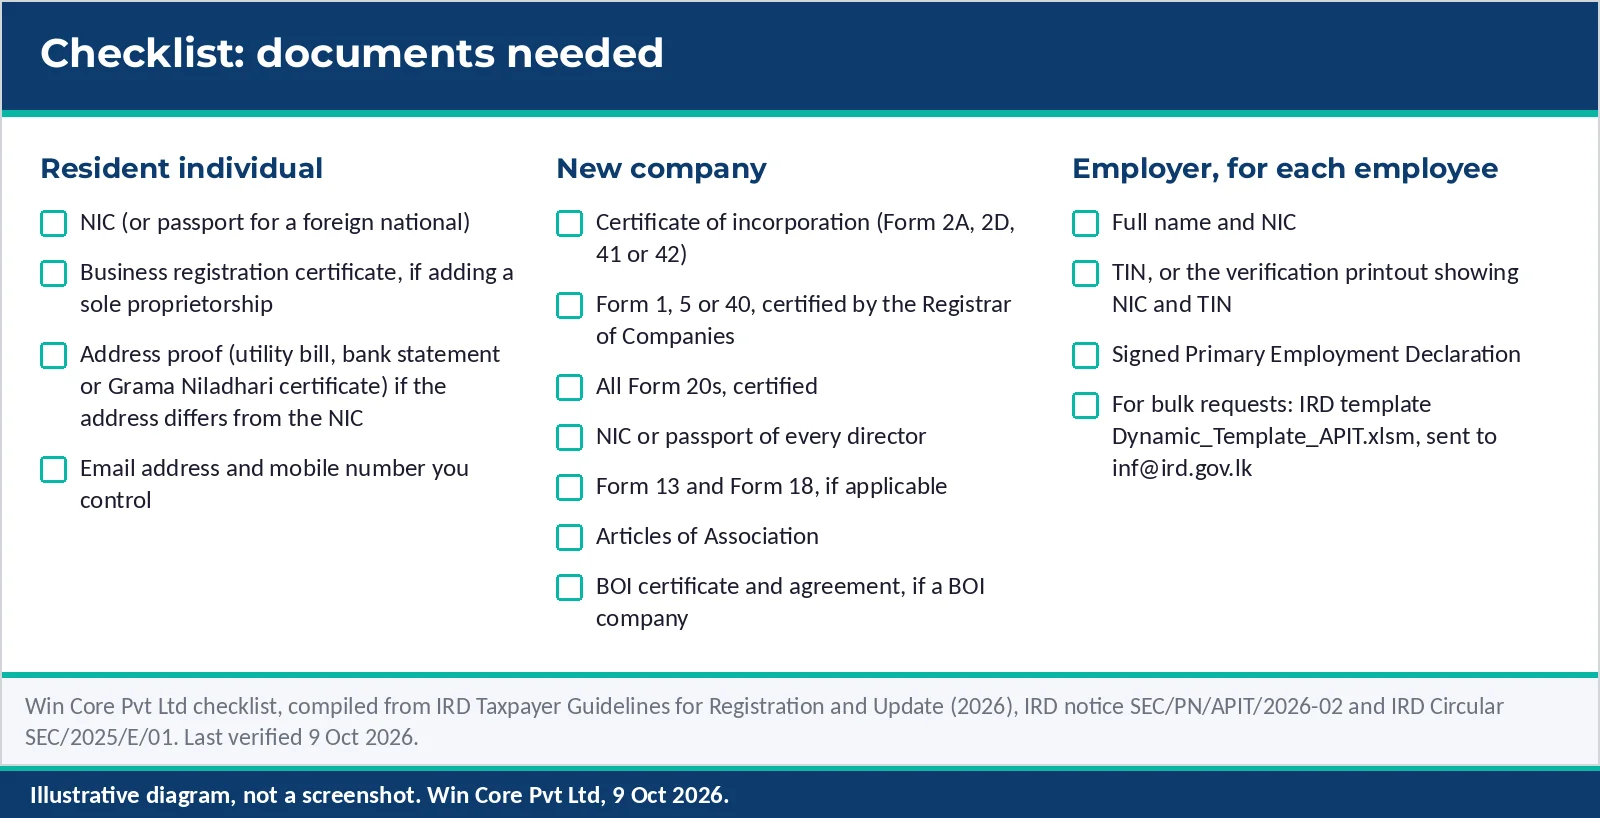
Checklist: documents needed
- Resident individual: NIC (or passport); BR certificate if adding a sole proprietorship; address proof if it differs from the NIC; an email and mobile you control
- New company: certificate of incorporation; Form 1, 5 or 40 and all Form 20s certified by the Registrar; NIC or passport of every director; Forms 13 and 18 if applicable; Articles of Association; BOI certificate and agreement if applicable
- Employer, per employee: name and NIC; TIN or verification printout; signed Primary Employment Declaration; for bulk requests, the IRD template sent to inf@ird.gov.lk
- For the gate after 1 November: TIN certificate photocopy, or the e-Services printout showing NIC and TIN, or a soft copy of either
For VAT and SSCL, the registrations that often follow a TIN, see VAT and SSCL registration thresholds in 2026, and for help with any of the registrations, our tax services page.
Related: TIN certificate circular SEC/2026/E/07: what changes on 1 November.
Frequently asked questions
I already have a TIN. Do I need to apply for a certificate?
The circular mentions no new application. A printout of the e-Services verification screen showing your NIC and TIN is accepted instead, and if you never received the certificate, the IRD directs you to its head office or a regional office [1].
Does our company need a TIN certificate to open its bank account?
The certificate rule exempts entities other than individuals [1]. The company still needs its own TIN, registered within 30 days of incorporation [2].
Is a company's TIN issued automatically when it is incorporated?
Not according to the IRD's registration guidance, which has companies apply through Taxpayer Registration [6] [7]. Once the TIN is issued, corporate income tax is registered automatically [6].
My employee says they are not liable to tax. Do they still need a TIN?
If they are a resident aged 18 or over, the Gazette cited in the circular makes registration mandatory [1]. On the APIT statement the TIN is mandatory in Schedule 01 for employees whose tax was deducted, and asked for in Schedule 03 where an employee below the threshold already has one [13].
Someone who has been in Sri Lanka eight months says they are non-resident. Are they exempt?
Probably not automatically. The circular's simple test covers a non-citizen here for less than 183 days. Anyone else claiming non-resident status needs an IRD confirmation of residence status, requested from itp@ird.gov.lk [1].
This guide reflects the circular, the Act and the IRD's notices as they stood on 9 October 2026. Gatekeepers sometimes ask for more than the circular says, especially in the first weeks of a new rule, so carry the certificate and the printout both.
Get the ticket before you reach the gate.
Talk to us. If you are incorporating, transferring shares or onboarding staff around 1 November and want the TINs in place first, book a consultation at our contact page.
WinCore Pvt Ltd
References
- Inland Revenue Department. Circular SEC/2026/E/07: Mandatory Submission of Taxpayer Identification Number (TIN) Certificate for Specified Transactions (22 September 2026), paras 1 to 4 and Attachment 1. Image-only PDF, read on 9 October 2026. https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2026_E_07_E.pdf . Primary. Accessed 9 October 2026.
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act No. 11 of 2026 (certified 3 June 2026), ss.1, 23, 24 (including new s.103(8)) and 31. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Inland Revenue Act No. 24 of 2017, consolidated text (amendments to 2025; "not a statutory consolidation"), ss.102, 103 and 177. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Public notice SEC/PN/IT/2026/05 (22 September 2026). https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/811/SEC_PN_IT_2026-05_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. TIN Verification through IRD e-Services (2 October 2026). https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/814/REG_02102026_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Taxpayer Guidelines for Registration and Update (2026). https://www.ird.gov.lk/en/Downloads/SiteAssets/TPR_Guidelines_2026_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. e-Services quick guide: TIN Registration (v0.11). https://www.ird.gov.lk/en/eServices/Lists/Registration/Attachments/1/TIN%20Registration%20v0%2011.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. e-Services quick guide: Obtaining a PIN (v0.12). https://www.ird.gov.lk/en/eServices/Lists/Registration/Attachments/2/Obtaining%20a%20PIN%20v0%2012.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. e-Services quick guide: PIN and user maintenance (v1.0). https://www.ird.gov.lk/en/eServices/Lists/Registration/Attachments/10/Quick_Guide_-_TIN-PIN_SSID-PW_Maintenance%20v1.0.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Notice on TIN registration under Gazette 2334/21 (5 February 2024). https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/565/PN_TIN_REG_2024-01_05022024_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Notice SEC/PN/APIT/2026-01 (24 February 2026). https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/764/SEC_PN_APIT_2026-01_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Notice SEC/PN/APIT/2026-02 (20 March 2026). https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/770/SEC_PN_APIT_2026-02_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Guide to the APIT Annual Statement, Y/A 2025/2026, "APIT Schedules". https://www.ird.gov.lk/en/Downloads/Other_PAYE_Doc/Asmt_APIT_Guide_2025_2026_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. APIT Annual Statement of Employers, Y/A 2025/2026 (Asmt_APIT_001). https://www.ird.gov.lk/en/Downloads/Other_PAYE_Doc/Asmt_APIT_001_2025_2026_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Circular SEC/2025/E/01: Guideline for employers on deducting APIT from employment income (25 March 2025). https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2025_E_01_E.pdf . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Forced Registration Unit web page ("Last updated: 24-03-2026"). https://www.ird.gov.lk/en/Unit%20and%20Services/sitepages/Information%20Branch.aspx?menuid=1310 . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Access to e-Services web page. https://www.ird.gov.lk/en/eServices/SitePages/Access%20To%20e-Services.aspx?menuid=1803 . Primary. Accessed 9 October 2026.
- Inland Revenue Department. Tax Calendar 2026, entry for 30 April 2026. https://www.ird.gov.lk/en/publications/Tax%20Calendar_Documents/Tax_Calendar_2026_E.pdf . Primary. Accessed 9 October 2026.
- Department of Government Printing. Extraordinary Gazette No. 2334/21 of 31 May 2023, notice under section 102(3) of the Inland Revenue Act, Parts A and B. https://documents.gov.lk/api/content-file-proxy?file=/extra-gazette-content/2334-21_E_1784564941.pdf (listed at https://documents.gov.lk/web/extra_gazettes). Primary. Accessed 9 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
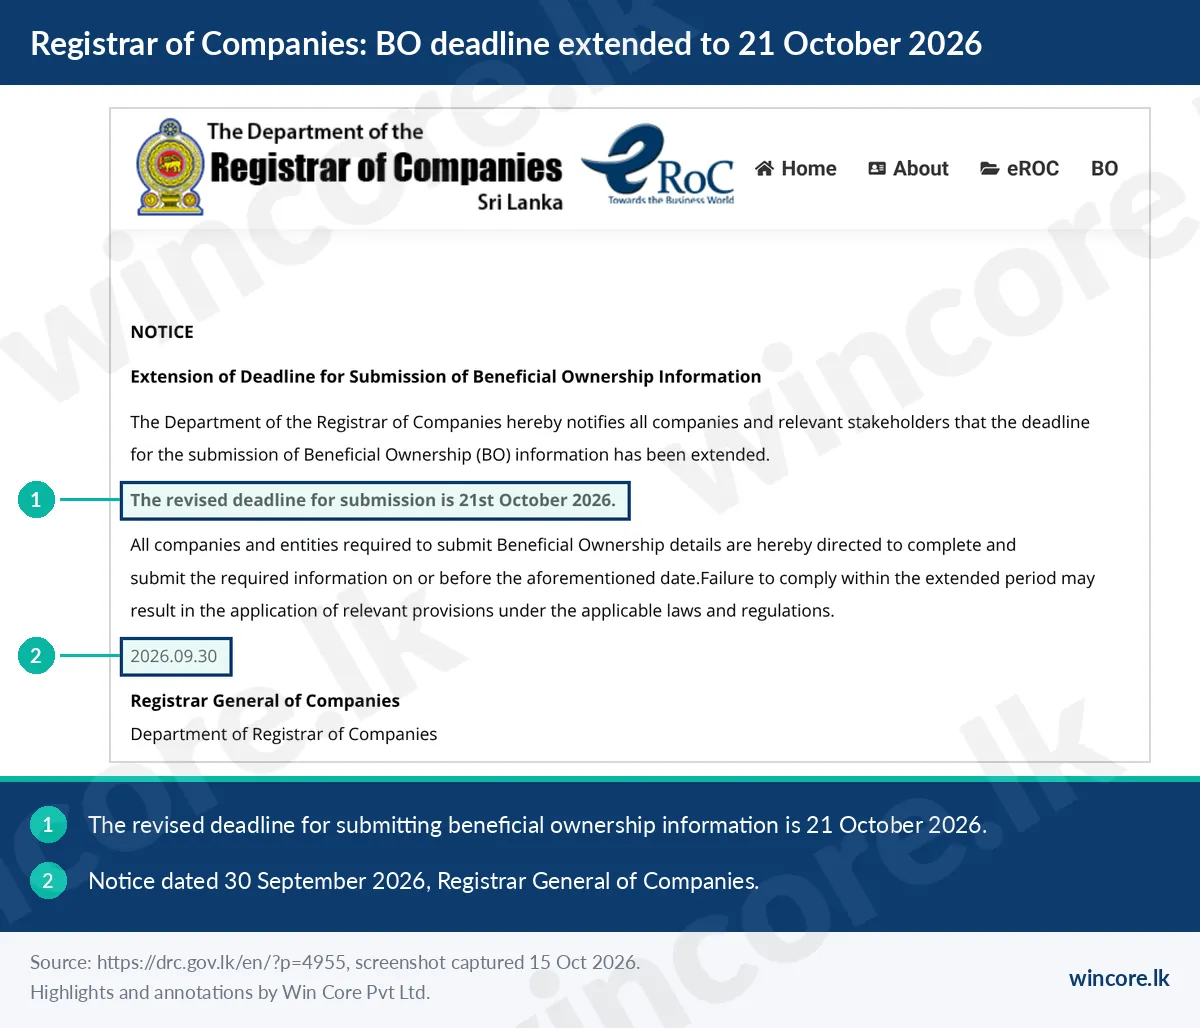
Who counts as a beneficial owner at 10 percent, the forms in the October 2026 regulations, and what existing companies face after the 21 October deadline.
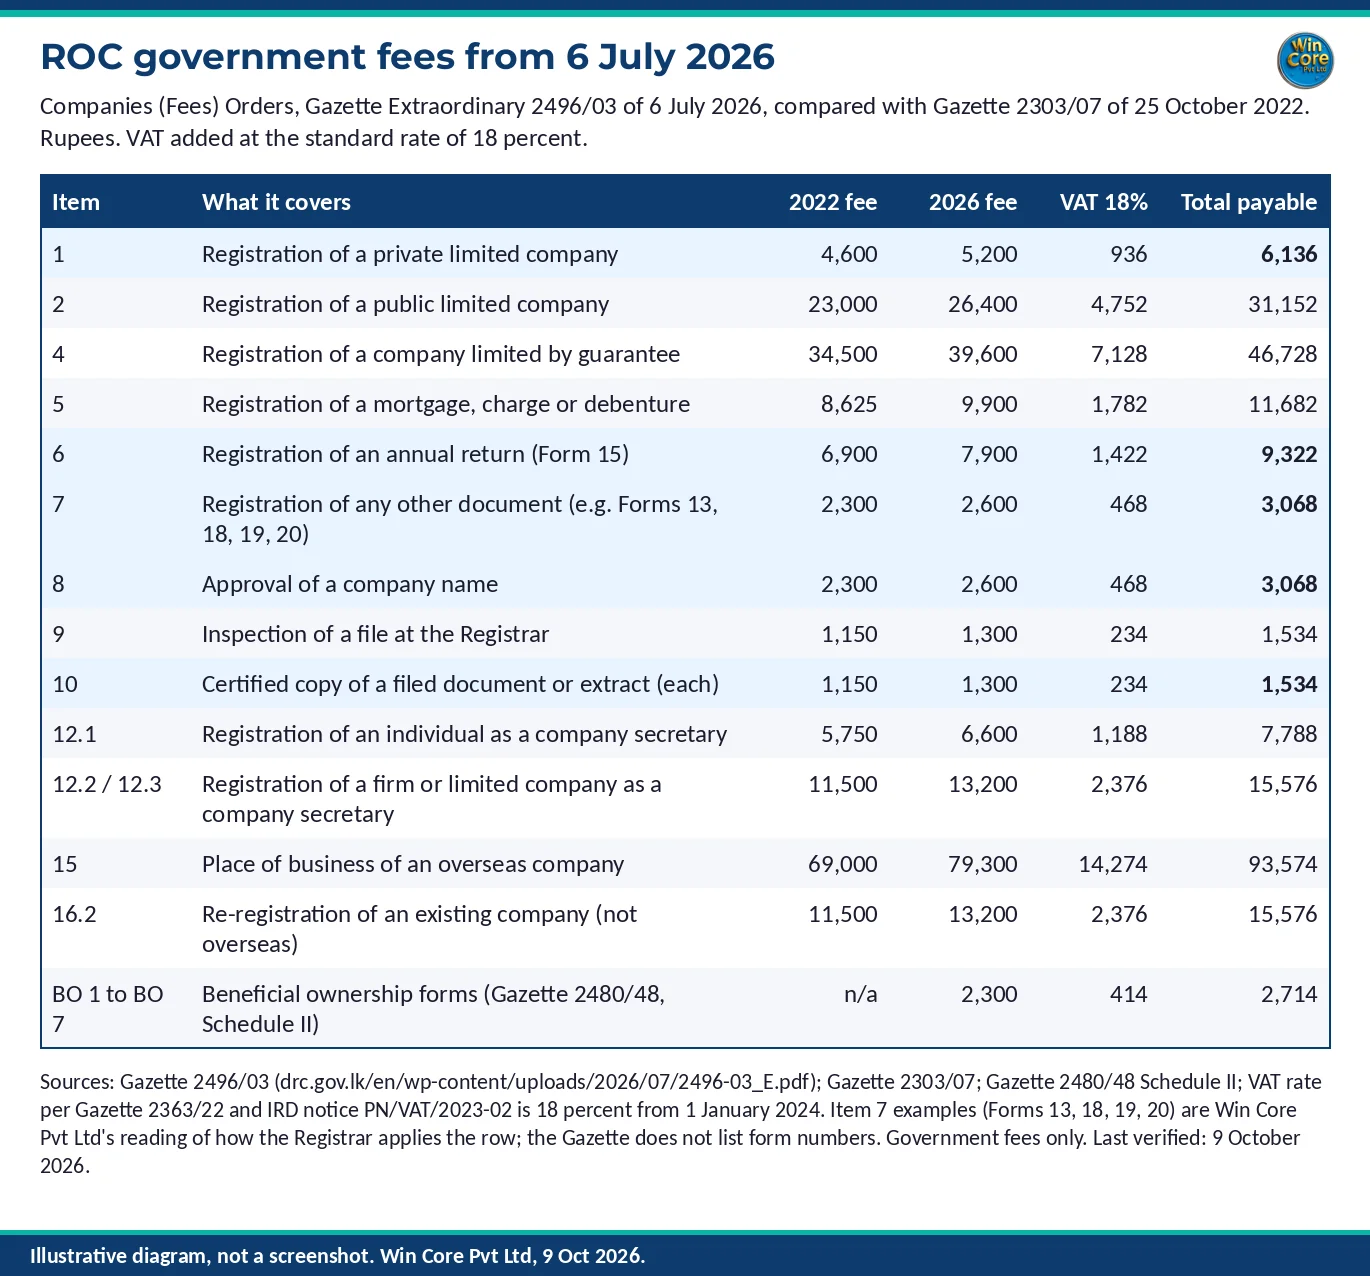
Every Registrar of Companies fee from 6 July 2026 with VAT added, and worked costs for an incorporation, a late Form 15 and a secretary change.
Most Sri Lankan companies can be 100 percent foreign owned. The three restricted lists in Gazette 2213/35, the retail test and the BOI route.