
Port City compliance calendar for Authorised Persons
One year in Colombo Port City on one page: licence renewal, audited accounts, the annual return, income tax and payroll, with the rule behind each date.
On this page
Last verified against the primary sources on 21 October 2026.
A Port City compliance calendar has three fixed points every year: renew the Commission licence thirty days before it expires (regulation 21(a)), submit audited accounts within six months of 31 March (regulation 16(a)), and file the annual return within thirty days of approving them (regulation 17), all under Regulations No. 01 of 2022, in force since 28 September 2022 [3]. Under the Amendment Act certified on 20 January 2026, every Authorised Person must also file income tax returns (new s.52C of the Port City Act) [2], and EPF and ETF apply to Port City employers as they do everywhere else [1].
A special economic zone usually trades one set of rules for another. Some national laws are switched off, some can be relaxed by order, and a new regulator adds rules of its own. Colombo Port City follows that pattern. Picture the year as a clock face with three hands. The licence hand turns on your licence date. The accounts hand turns on your financial year end. The tax hand turns on the Inland Revenue year. They move at different speeds, and each one can trip you if you only watch the others.
This piece is the map. For the two accounts deadlines and what late filing costs, read Port City audited accounts and the annual return deadline.
The Port City compliance calendar runs on three clocks: licence, accounts and tax
The instruments behind the calendar:
- Colombo Port City Economic Commission Act, No. 11 of 2021: licensing, the Schedules of laws, and offences (s.68) [1].
- CPCEC (Amendment) Act, No. 1 of 2026, certified 20 January 2026: a new s.35 on employees and a new s.52C on tax returns [2].
- Regulations No. 01 of 2022, Gazette Extraordinary No. 2299/46: the licence, changes, accounts, annual return, renewal and penalties [3].
- Inland Revenue (Amendment) Act, No. 11 of 2026, certified 3 June 2026: a new s.94(2A) for Businesses of Strategic Importance [4].
They reach every person licensed by the Commission to engage in business in and from the Area of Authority of the Colombo Port City, whether or not it has Business of Strategic Importance status.
| When | What | Source | Type |
|---|---|---|---|
| Within 30 days of any change | Schedule III notice of changed particulars | Reg 15(a) [3] | Statutory |
| Monthly, by the 15th of the following month | APIT where employment income is taxable | Inland Revenue Act s.86(1); IRD Tax Calendar 2026 [5] | Statutory |
| Monthly, by the last day of the following month | EPF and ETF contributions | EPF and ETF Acts | Statutory |
| 30 days before licence expiry | Renewal application, Schedule V | Reg 21(a) [3] | Statutory |
| 6 months after year end (30 September) | Audited, approved, signed accounts to the Commission | Reg 16(a) [3] | Statutory |
| 30 days from approval of accounts | Annual return, Schedule IV | Reg 17 [3] | Statutory |
| 30 November 2026 | Income tax return for Y/A 2025/26 | IRD Tax Calendar 2026 [5] | Administrative listing |
| Always | Accounting records at the Port City office for at least ten years | Reg 16(c) [3] | Statutory |
For payroll deadlines, first establish which Port City employees qualify for income-tax relief.
The licence must be renewed thirty days before it expires
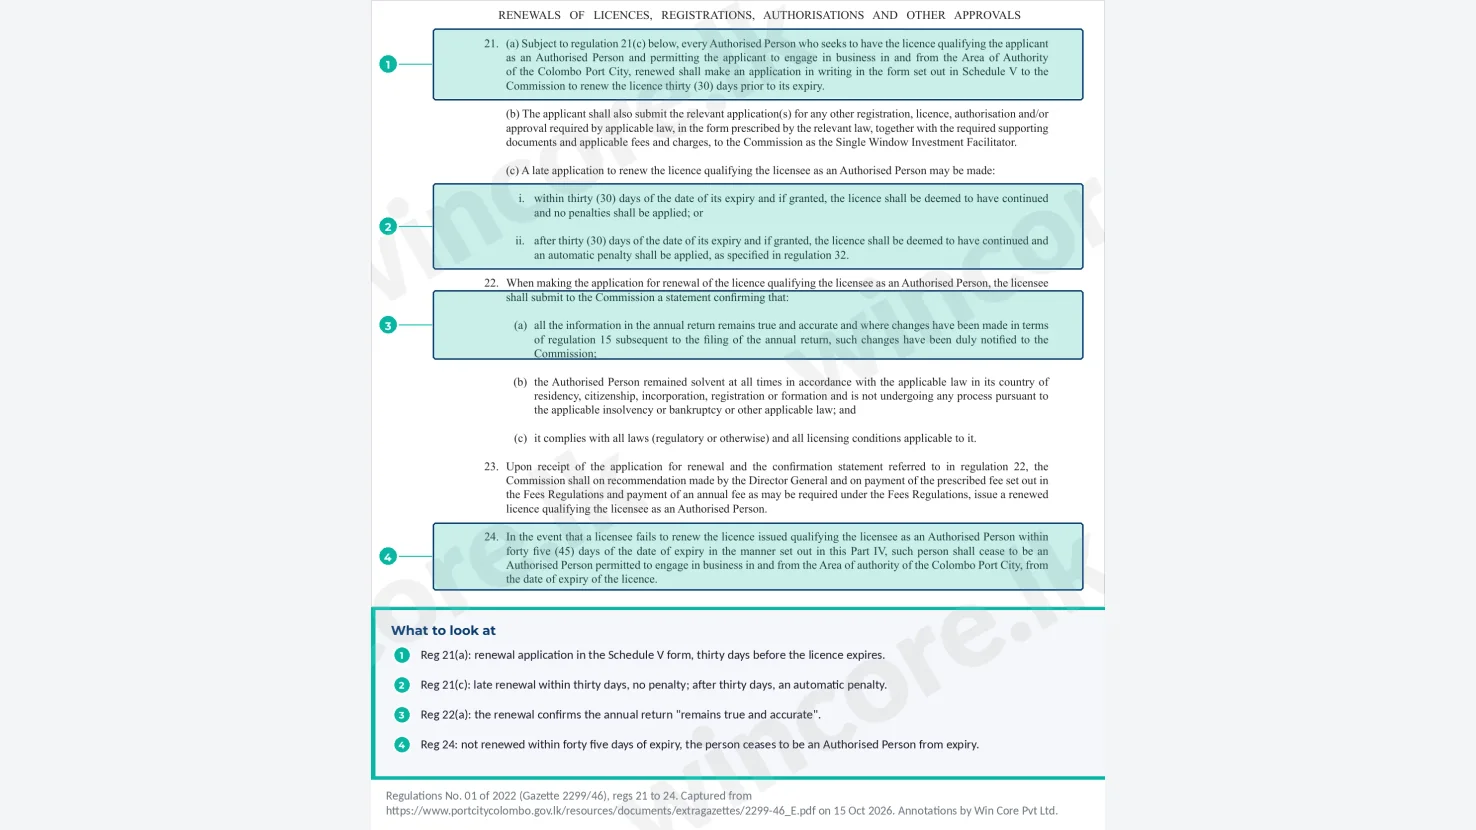
A licence "shall be valid for a period of twelve(12) months from the date of issue thereof" (reg 8(b)) [3]. Renewal is not automatic. Regulation 21(a) requires a written application in the Schedule V form "thirty (30) days prior to its expiry" [3].
Being late has three stages.
- Within thirty days after expiry: if the late application is granted, the licence is "deemed to have continued and no penalties shall be applied" (reg 21(c)(i)).
- After thirty days: if granted, the licence is deemed continued but "an automatic penalty shall be applied, as specified in regulation 32" (reg 21(c)(ii)). We found no amount for it in the Gazette, so the penalty is not quantified.
- After forty five days without renewal: the licensee "shall cease to be an Authorised Person ... from the date of expiry of the licence" (reg 24) [3].
The renewal carries a statement under reg 22: the annual return "remains true and accurate" and later changes have been notified, the business stayed solvent, and it "complies with all laws (regulatory or otherwise) and all licensing conditions applicable to it" [3]. Renewal also triggers the prescribed fee and any annual fee under the Fees Regulations (reg 23). Regulation 21(b) makes the Commission the "Single Window Investment Facilitator" for other licences you renew alongside the main one; that single window is for applications, not for every filing, so the IRD and the Labour Department still expect their own returns.
Accounts at six months, then the annual return thirty days after approval
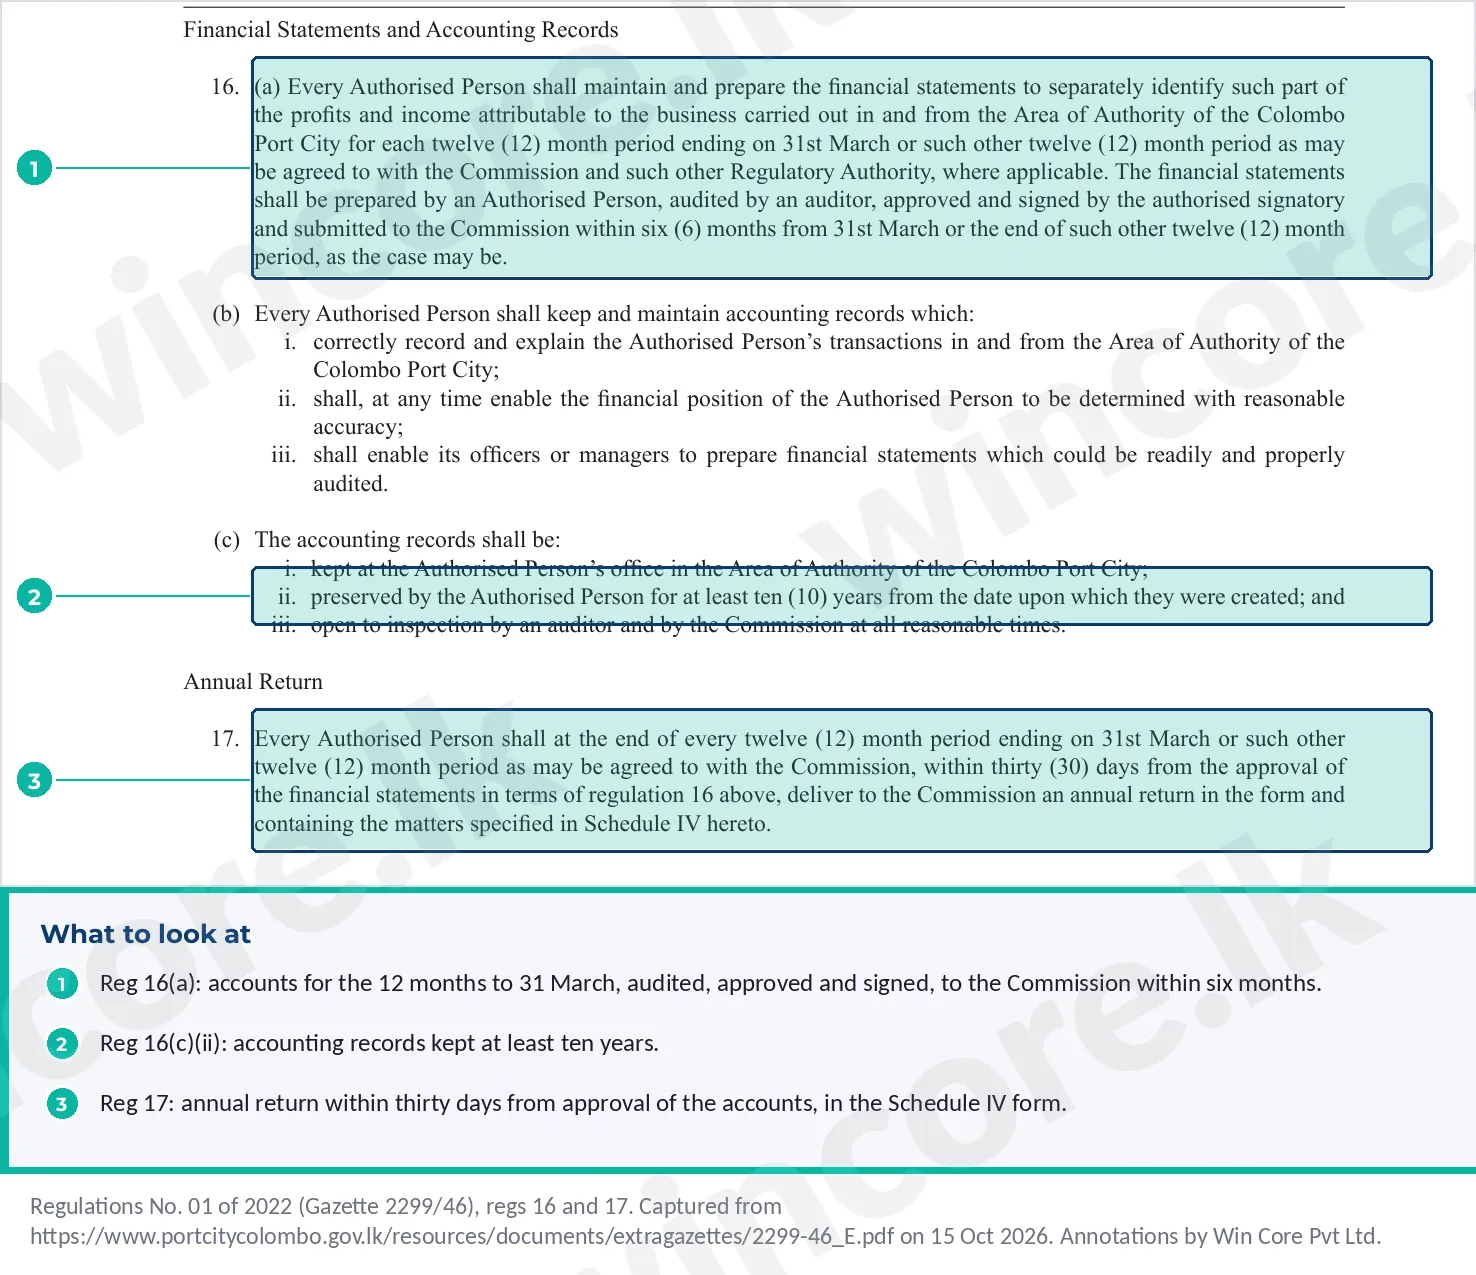
Regulation 16(a) requires accounts for each twelve months to 31 March (or another period agreed with the Commission and any other relevant regulatory authority), separately identifying Port City profits, "audited by an auditor, approved and signed by the authorised signatory and submitted to the Commission within six (6) months" [3]. Regulation 17 then requires the annual return "within thirty (30) days from the approval of the financial statements" [3]. Changes to your particulars do not wait for either: they go on Schedule III within thirty days of the change (reg 15(a)), and your company secretarial services provider should keep that register current.
Our piece on the Port City audited accounts deadline covers the two deadlines and the penalties.
Every Authorised Person files income tax returns, BSI or not
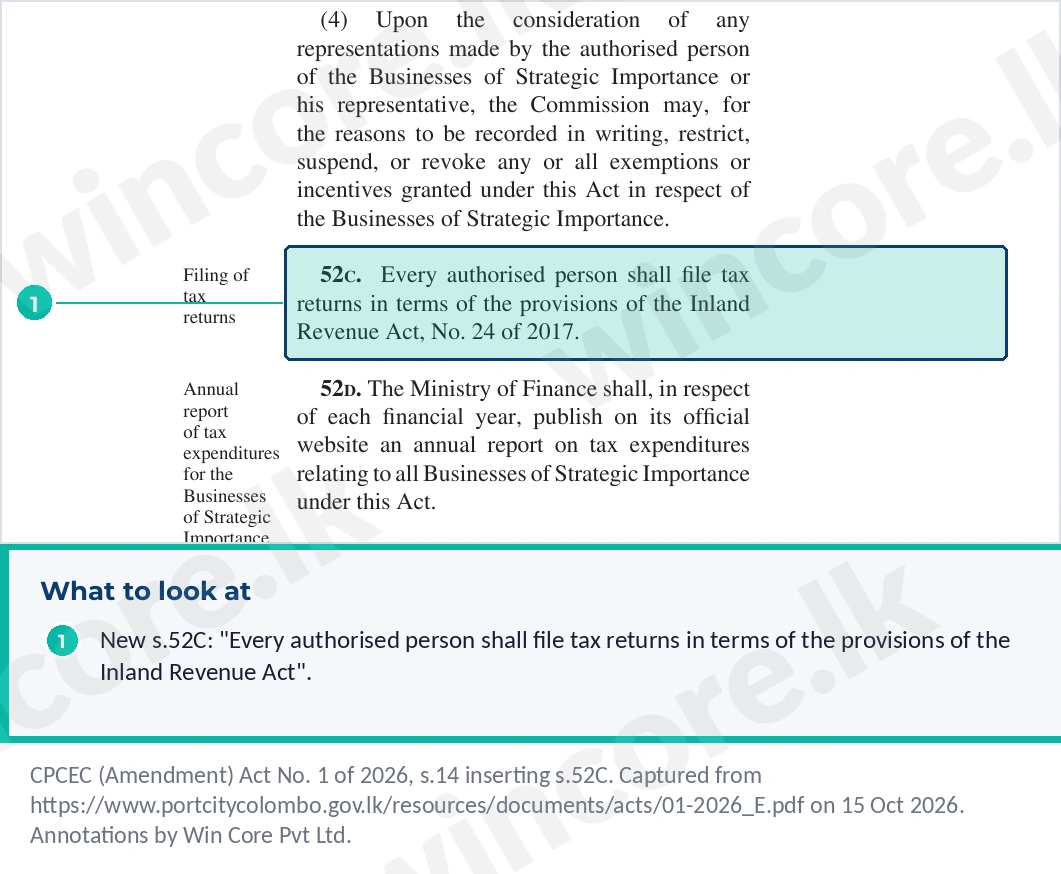
Every Authorised Person files. New s.52C reads: "Every authorised person shall file tax returns in terms of the provisions of the Inland Revenue Act, No. 24 of 2017" [2]. For a Business of Strategic Importance, new s.94(2A) of the Inland Revenue Act adds that a person carrying on such a business "shall file a tax return in the form and manner specified by the Commissioner-General", and on its terms it applies notwithstanding subsection (1), the list of people excused from filing [4].
The Y/A 2025/26 return. The IRD Tax Calendar 2026 lists 30 November 2026 for income tax returns for Y/A 2025/2026 [5]. Our income tax compliance services prepare and file it.
Concessions are not automatic. Tax concessions come from a Business of Strategic Importance Order published in the Gazette, not from the licence, and each Order sets its own reliefs and dates. Your suppliers have a separate rule: from 1 July 2026 supplies to a BSI are VAT exempt.
Staff tax exemption depends on when you were licensed, and EPF and ETF always apply
Employee income tax. The new s.35 lets a person granted a "registration, licence, authorisation or other approval" before the section came into operation employ residents or non-residents "remunerated in a designated foreign currency, other than in Sri Lanka Rupees", with their employment income exempt "for a period of three years commencing from the month immediately following the month in which this section comes into operation" [2]. Employees of persons approved "on or after" that date are "liable to income tax" (s.35(3)). The Amendment Act states no separate commencement date; on our reading the section came into operation when the Act was certified on 20 January 2026, which puts the window at February 2026 to January 2029. On our reading, too, a business whose licence lapses under reg 24 and is licensed afresh would be approved after that date and fall under s.35(3). Where pay is taxable, APIT applies as on the mainland; see our APIT deduction guide.
Labour law. Schedule III of the 2021 Act lists the laws that "shall have no application" in the Port City; none of them is a labour law [1]. Schedule II lists the enactments from which exemptions "may be granted", and it includes the Termination of Employment of Workmen (Special Provisions) Act, No. 45 of 1971, but not the EPF or ETF Acts [1]. On that text, EPF and ETF apply to Port City employers as they do elsewhere, with contributions due by the last day of the following month; see our EPF and ETF guide for 2026 and the EPF calculator. Our payroll services run the monthly cycle.
A worked year shows where the three clocks collide
Take a hypothetical Authorised Person, a regional reinsurance broker first licensed on 10 December 2024, with a 31 March year end and renewals granted on time. On our count each licence runs twelve months, so the current one expires on 9 December 2026. Its 2026 looks like this:
- Every month: APIT, where pay is taxable, by the 15th of the following month; EPF and ETF by the last day of the following month.
- 21 July 2026: the signatory approves the audited accounts for the year to 31 March 2026.
- By about 20 August 2026: annual return, thirty days from approval (reg 17).
- 30 September 2026: latest date for the audited accounts to reach the Commission (reg 16(a)); in practice they went with the approval.
- By about 9 November 2026: renewal application, thirty days before expiry (reg 21(a)), confirming the annual return is still accurate (reg 22(a)).
- 30 November 2026: income tax return for Y/A 2025/26, per the IRD Tax Calendar.
- 9 December 2026: licence expiry if not renewed; a late application made by 8 January 2027 carries no penalty if granted (reg 21(c)(i)).
The collision is in November: the renewal confirmation and the tax return fall in the same month, and the renewal asks you to confirm compliance with "all laws", tax included.
What late costs
Breach of any regulation, including late accounts, a late return or a late notice, is an offence under s.68 of the 2021 Act, which sets fines and imprisonment on conviction in two limbs, s.68(1)(e) and s.68(3) [1]. Regulation 31(a) of Part VII lets the Commission instead accept a penalty "in composition of the offence" for a late renewal or a late filing [3], and contravening the regulations is a "material default or breach" that can lead to notice of cancellation (regs 27(a)(vii), 28(a)). The penalty table, with both s.68 ranges, is in our audited accounts deadline piece. Tax and EPF penalties follow their own Acts.
What a business must do
- Diary the licence expiry, with renewal thirty days before.
- Notify changes within thirty days on Schedule III.
- Set the year end and separate Port City income in the ledger; our accounting services set this up.
- Finish the audit before six months, and diary the return for thirty days after approval.
- File income tax returns every year, even if nil.
- Run payroll with EPF and ETF, and check each employee against the s.35 exemption.
- Keep records at the Port City office for at least ten years.
- Show your particulars (name, office address, licence number, Certificate of Registration if any, authorised signatory) on official communications (reg 13) [3].
Checklist: documents needed
- Current licence with its issue and expiry dates
- Schedule V renewal form and the reg 22 confirmation statement
- Schedule III notices filed in the year
- Audited, approved and signed accounts with the approval date
- Schedule IV annual return and its working sheet
- Income tax return and computation for the year of assessment
- EPF and ETF remittance records and APIT records for each month
- For each employee, the facts behind the s.35 exemption: approval date of the employer and currency of pay
Common misreadings
- "Port City means no tax filings." Section 52C requires every Authorised Person to file.
- "The licence renews itself." Regulation 21 needs a written application.
- "Labour law does not apply." EPF and ETF are in neither Schedule II nor Schedule III.
- "The annual return is due at six months." It is due thirty days after the accounts are approved.
What this means for you
Keep one calendar with all three hands on it: the licence date, the approval date of the accounts, and the tax year. The rules are not hard. The risk is a date missed because the licence, accounts and tax years do not line up, and a renewal statement signed while one of them is still open.
Open points. Regulation 21(c)(ii) points to regulation 32 for the late renewal penalty, but we found no amount for it in the Gazette or in any other published source. The amount of the annual fee under reg 23 sits in the Fees Regulations, not reviewed for this piece. We found no Commission notice setting administrative filing dates (portcitycolombo.gov.lk searched 21 October 2026). The commencement of s.35 is our reading, not a stated date. How Companies Act duties apply to an Authorised Person that is also a Sri Lankan company is not covered here.
FAQ
How long is a Port City licence valid?
A Port City licence is valid for twelve months from the date of issue, under regulation 8(b) of Regulations No. 01 of 2022. It does not renew itself. You apply in writing on the Schedule V form thirty days before it expires, with a statement confirming the annual return is still accurate, solvency, and compliance with all laws.
What happens if we renew the Port City licence late?
A late application made within thirty days of expiry carries no penalty if granted, and the licence is treated as continuing. After thirty days an automatic penalty applies, but we found no amount for it in the Gazette. If the licence is not renewed within forty five days of expiry, you cease to be an Authorised Person from the expiry date.
Must a Port City company file a tax return if it has no income?
Yes. Section 52C of the Port City Act, inserted in January 2026, requires every authorised person to file tax returns under the Inland Revenue Act. For a Business of Strategic Importance, the new s.94(2A) of the Inland Revenue Act adds a filing duty that applies despite the usual exemptions in s.94(1), so a nil return is still a return.
Do EPF and ETF apply in Port City?
Yes, on the text of the Port City Act. Neither the EPF Act nor the ETF Act appears in Schedule III, the laws that do not apply in the Port City, or in Schedule II, the laws from which a Business of Strategic Importance can be exempted. Contributions are due by the last day of the following month, as on the mainland.
Is every Port City employee's salary tax free?
No. Under the new s.35, only employees of businesses approved by the Commission before the section came into operation, paid in a designated foreign currency, are exempt, and only for three years from the following month, on our reading February 2026 to January 2029. Employees of businesses approved on or after that date are liable to income tax.
This article is general information, not advice for your specific situation.
Talk to us. If you want one calendar for your licence, accounts, tax and payroll, book a consultation at our contact page and we will build it from your licence and year end.
WinCore Pvt Ltd
References
- Parliament of Sri Lanka. Colombo Port City Economic Commission Act, No. 11 of 2021, s.68, Schedules II and III. https://www.portcitycolombo.gov.lk/resources/documents/acts/11-2021_E.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Colombo Port City Economic Commission (Amendment) Act, No. 1 of 2026 (certified 20 January 2026), ss.3 (new s.35) and 14 (new s.52C). https://www.portcitycolombo.gov.lk/resources/documents/acts/01-2026_E.pdf . Primary. Accessed 21 October 2026.
- Colombo Port City Economic Commission. Regulations No. 01 of 2022, Gazette Extraordinary No. 2299/46 (28 September 2022), regs 8(b), 13, 15 to 17, 21 to 24, 27, 28, 31 and 32. https://www.portcitycolombo.gov.lk/resources/documents/extragazettes/2299-46_E.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act, No. 11 of 2026 (certified 3 June 2026), s.19(2) (new s.94(2A)). https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 21 October 2026 (closing words and certification date re-read; opening words as read on 15 October 2026).
- Inland Revenue Department. Tax Calendar 2026, APIT payment entries (15th of each month) and 30 November 2026 entries. https://www.ird.gov.lk/en/publications/Tax%20Calendar_Documents/Tax_Calendar_2026_E.pdf . Primary (administrative). Accessed 21 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
Accounts by 30 September, the return thirty days after approval: how the two Port City deadlines interlock, and what a late filing costs.
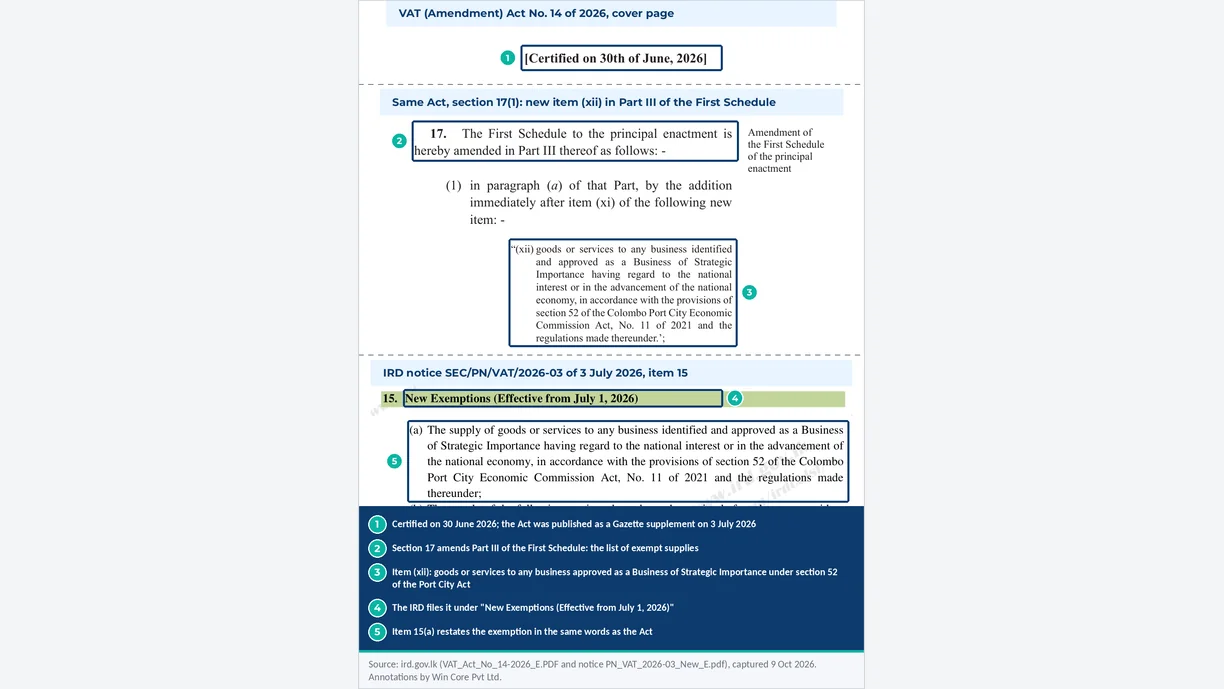
From 1 July 2026 supplies to a Port City Business of Strategic Importance are VAT exempt. The legal basis, invoicing and the input VAT effect.
A late annual return rarely stands alone. Fix the officers, file beneficial ownership at once, then each overdue return with its AGM, then tax.