
Port City audited accounts deadline: six months, then the return
Accounts by 30 September, the return thirty days after approval: how the two Port City deadlines interlock, and what a late filing costs.
On this page
Last verified against the primary sources on 21 October 2026.
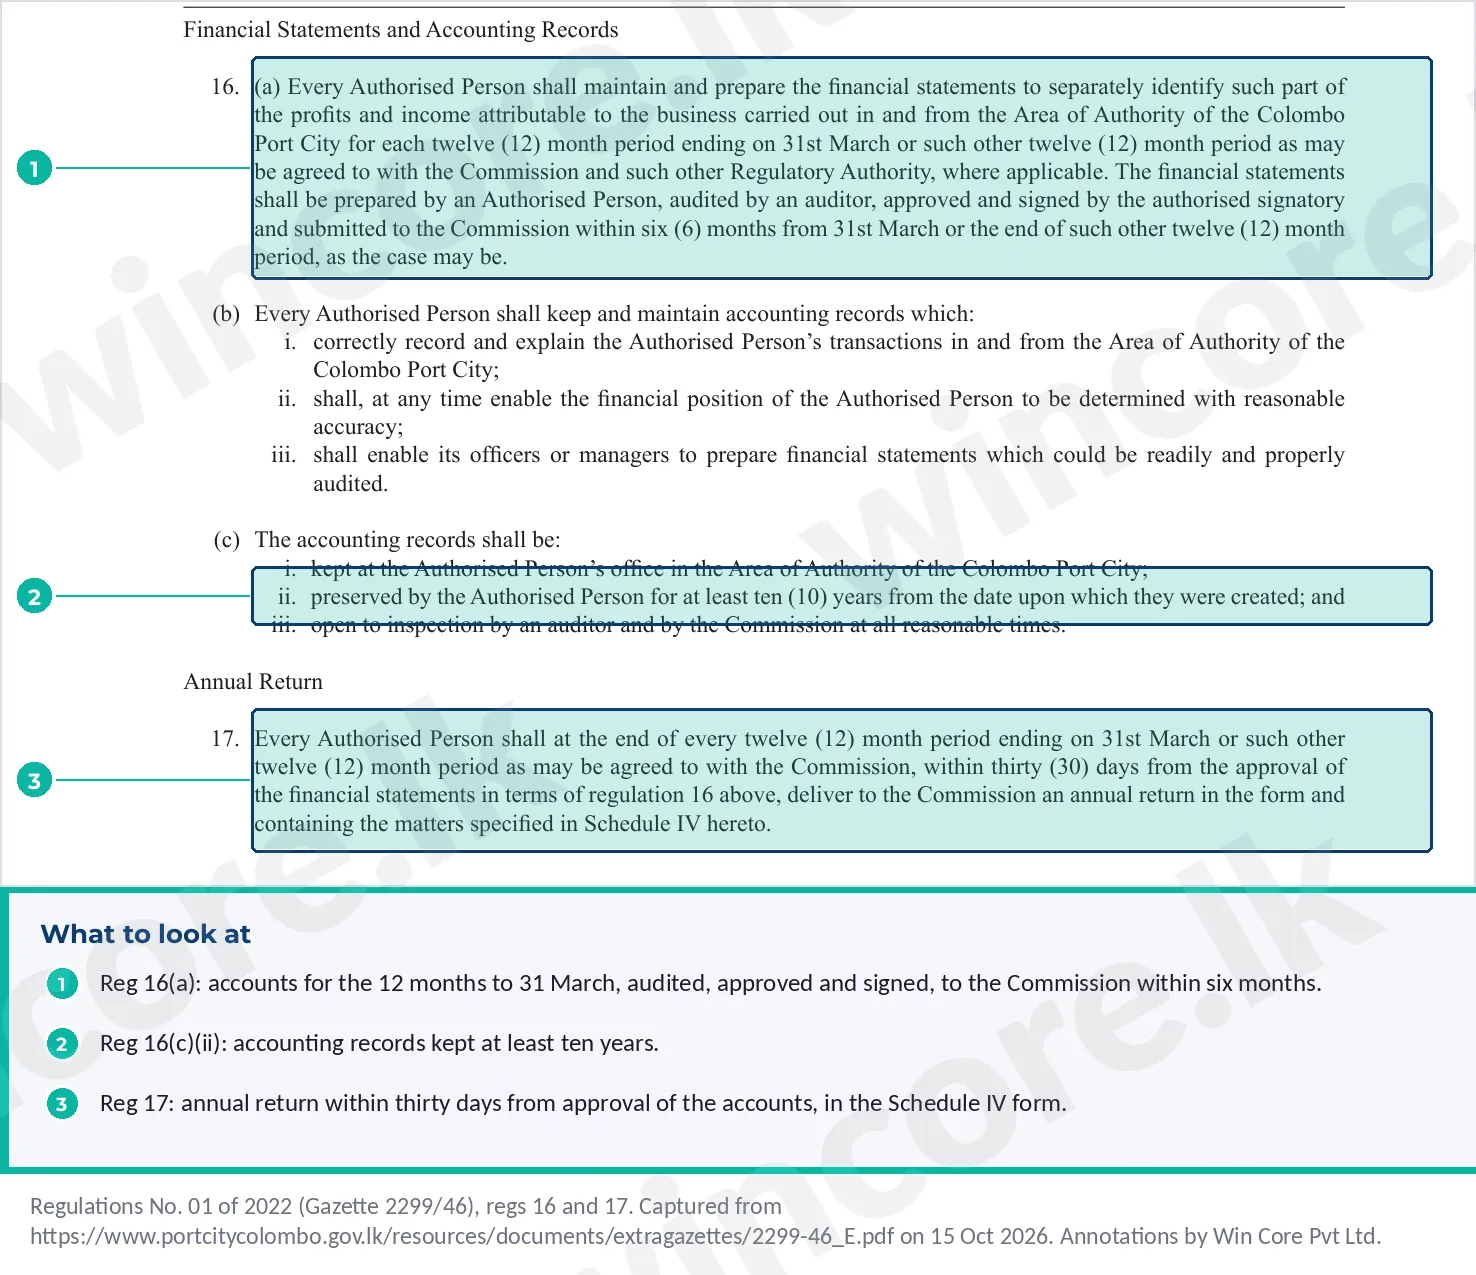
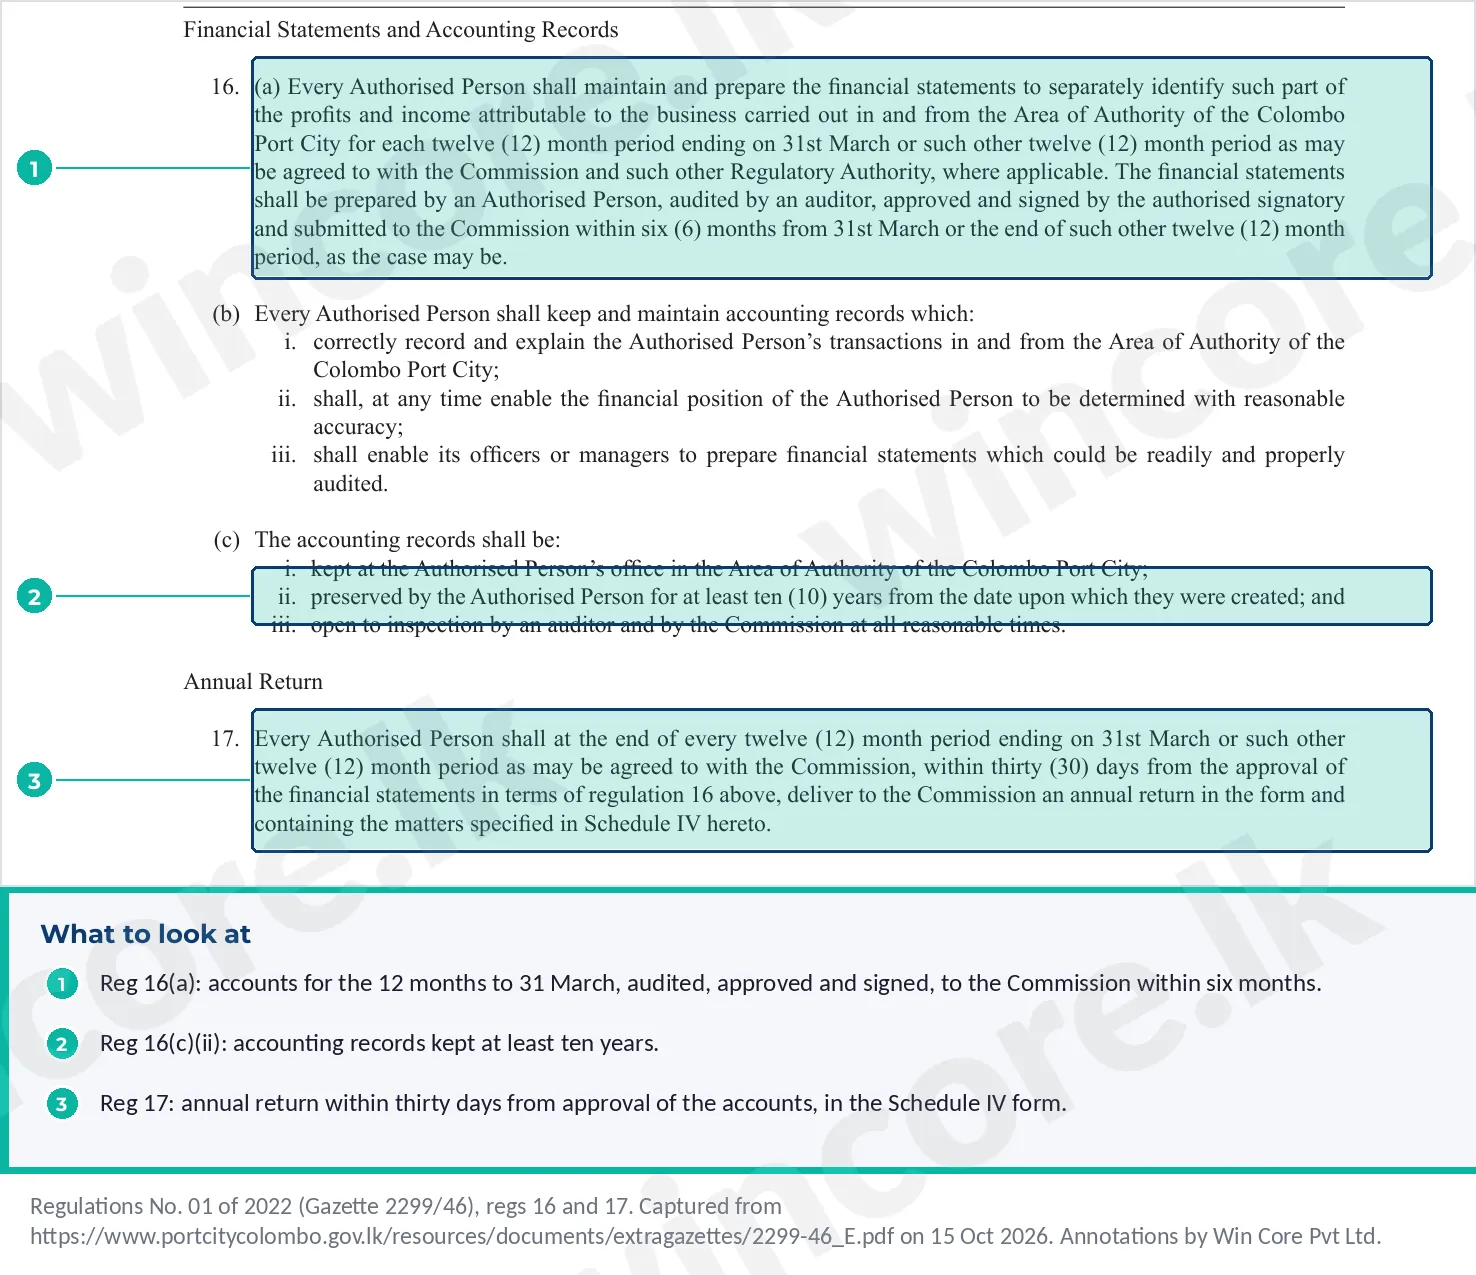
The Port City audited accounts deadline is six months from 31 March, so 30 September for a March year end: regulation 16(a) of the Colombo Port City Commission's Regulations No. 01 of 2022, in force since 28 September 2022, requires the financial statements to be audited, approved, signed and submitted to the Commission by then [1]. The annual return follows within thirty days of the day the accounts are approved (regulation 17) [1]. One deadline is fixed on the calendar. The other moves with an event you control.
Think of it as a relay. The first runner, the audited accounts, must reach the handover point by a fixed time. The second runner, the annual return, starts the moment the baton changes hands, and has thirty days to finish. A slow first leg does not give the second runner more time. It only means the first leg was already late.
This piece is about the two deadlines and how they fit together. Our Port City compliance calendar puts these dates alongside the licence renewal and the tax year.
Port City audited accounts are due six months after 31 March
The rule is in the Regulations for Registration, Licensing, Authorisation and other Approvals of Authorised Persons, No. 01 of 2022, published in Gazette Extraordinary No. 2299/46 of 28 September 2022 [1]. It applies to every Authorised Person, meaning any business licensed by the Commission to operate in and from the Area of Authority of the Colombo Port City, whether or not it has Business of Strategic Importance status.
Regulation 16(a) requires every Authorised Person to "maintain and prepare the financial statements to separately identify such part of the profits and income attributable to the business carried out in and from the Area of Authority of the Colombo Port City" for each twelve-month period ending 31 March, "or such other twelve (12) month period as may be agreed to with the Commission and such other Regulatory Authority, where applicable" [1]. Each element is a separate test.
- Separate identification. The accounts must show which profits come from Port City business. A single undivided profit line does not meet the words.
- Audited. "Audited by an auditor". The regulation does not say which auditing standards or which auditor qualifications apply; we treat that as open.
- Approved and signed by the authorised signatory. The approval date matters, because it starts the second leg.
- Submitted within six months. "Submitted to the Commission within six (6) months from 31st March or the end of such other twelve (12) month period, as the case may be" [1].
Regulation 16(b) and (c) add the records behind the accounts. They must correctly record and explain the Port City transactions, be kept at the Port City office, be "preserved by the Authorised Person for at least ten (10) years from the date upon which they were created", and be open to the auditor and the Commission at all reasonable times [1]. If you want a different year end, agree it with the Commission first; our piece on changing your financial year end covers the Companies Act side.
The annual return runs thirty days from approval, not from the year end
Regulation 17 requires an annual return "within thirty (30) days from the approval of the financial statements in terms of regulation 16 above", in the Schedule IV form [1]. The clock starts at approval, not at 31 March and not at the auditor's report date.
Two consequences follow.
- Early approval means an early return. Accounts approved on 20 July need a return by about 19 August, long before 30 September.
- Late accounts do not buy time. If approval slips past six months, reg 16(a) is already breached, and the reg 17 clock still runs from approval.
Day counting: the regulations do not define how to count the thirty days. On our reading you count thirty calendar days from the day after approval; where in doubt, file a day early.
The filing itself goes through the Commission's electronic lodgement system or, in its absence or in special circumstances, manually "as instructed by the Commission" (the regulation 31 in Part VIII), and copies of everything filed must be kept for ten years (reg 31(c), Part VIII) [1].
Only the regulations set these dates; the filing method is administrative
| Date or step | What it is | Source | Type |
|---|---|---|---|
| 31 March | End of the twelve-month period, unless another period is agreed with the Commission and any other relevant regulator | Reg 16(a) | Statutory |
| Six months after year end (30 September for 31 March) | Audited, approved and signed accounts submitted to the Commission | Reg 16(a) | Statutory |
| Thirty days from approval of the accounts | Annual return in the Schedule IV form | Reg 17 | Statutory |
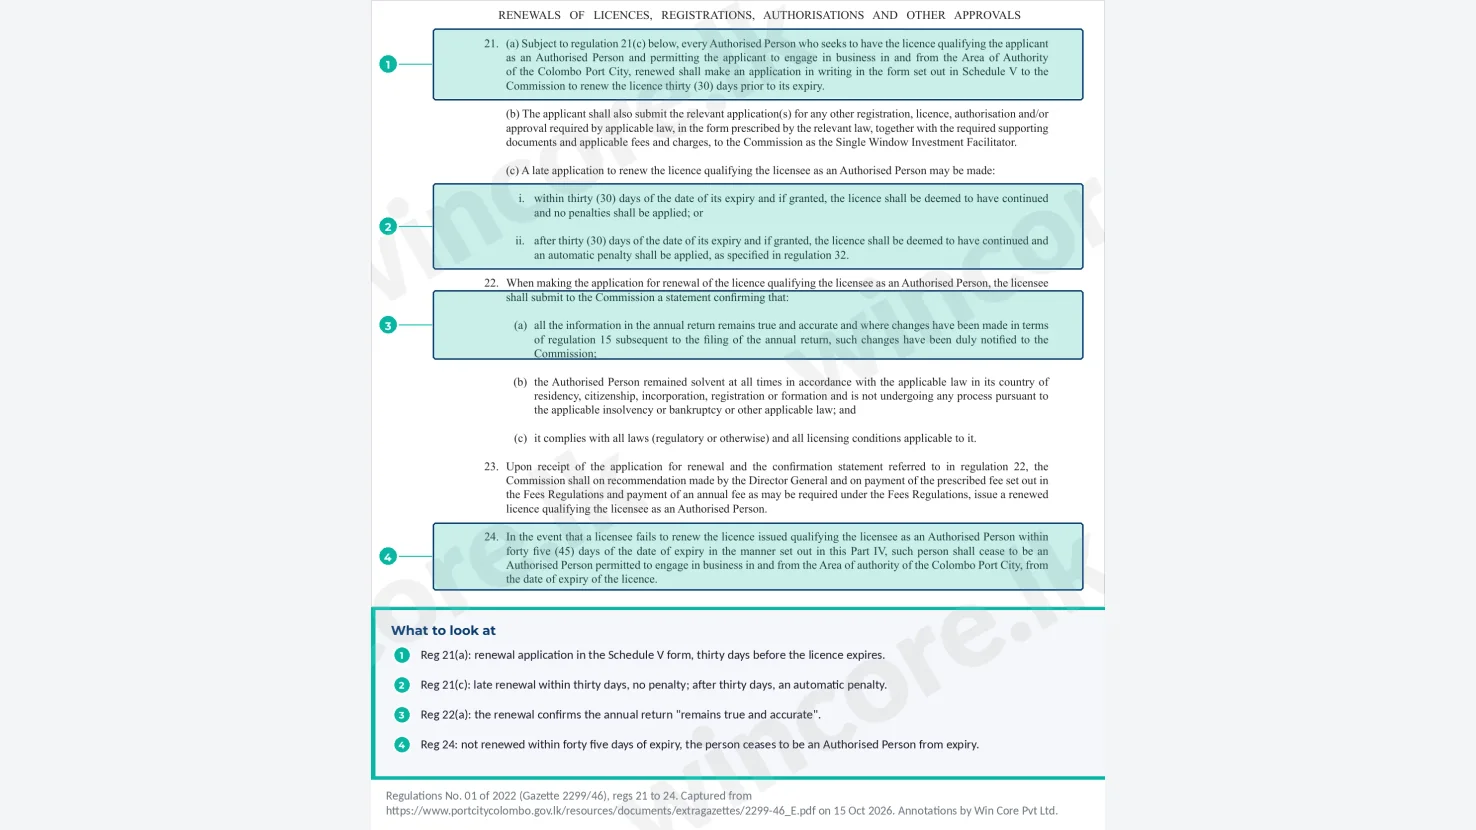
| Thirty days before licence expiry | Renewal application, with a statement that the annual return "remains true and accurate" | Regs 21(a), 22(a) | Statutory |
| How to file | Electronic lodgement system, or manually "as instructed by the Commission" | Reg 31, Part VIII | Statutory rule, administrative method |
| Form version | The Commission's published Schedule IV form [3], or any fuller version it sends you | Commission website | Administrative |
We searched portcitycolombo.gov.lk on 21 October 2026 and found no Commission notice setting a different administrative date for either filing. That is an absence, not a ruling: if a notice is issued, read it alongside the regulations, not instead of them.
Late filing is an offence, but the Commission can compound it
| Failure | Consequence | Source |
|---|---|---|
| Contravening or failing to comply with any regulation, which includes late accounts or a late return | Offence: on conviction, a fine of Rs 1 million to Rs 5 million, or imprisonment of three months to two years, or both | Act s.68(1)(e) [2] |
| The same failure, under the Act's general offence | Offence: on conviction, a fine of Rs 500,000 to Rs 1 million, or imprisonment of three months to one year, or both, and a continuing fine of up to Rs 500,000 for each day the offence continues | Act s.68(3) [2] |
| A late account or return that is an offence | Instead of prosecuting, the Commission may impose "a penalty of such amount as the Commission may think proper in composition of the offence" | Reg 31(a), Part VII [1] |
| Contravening the Act or the regulations | A "material default or breach", which can lead to notice of intention to cancel the licence, with thirty days to object | Regs 27(a)(vii), 28(a) and (b) [1] |
Both s.68(1)(e) and s.68(3)(a) cover a failure to comply with a regulation, with different ranges. The Act does not say which a prosecutor must use for a late filing, so we show both and treat the choice as open. Both are on conviction by a Magistrate after summary trial. Composition under regulation 31(a) is at the Commission's discretion, and once a penalty is accepted no proceedings may be taken or continued for that offence (reg 31(b)) [1].
There is no fixed late-filing fee in the regulations for these two filings. We do not quote a figure because none is published in them.
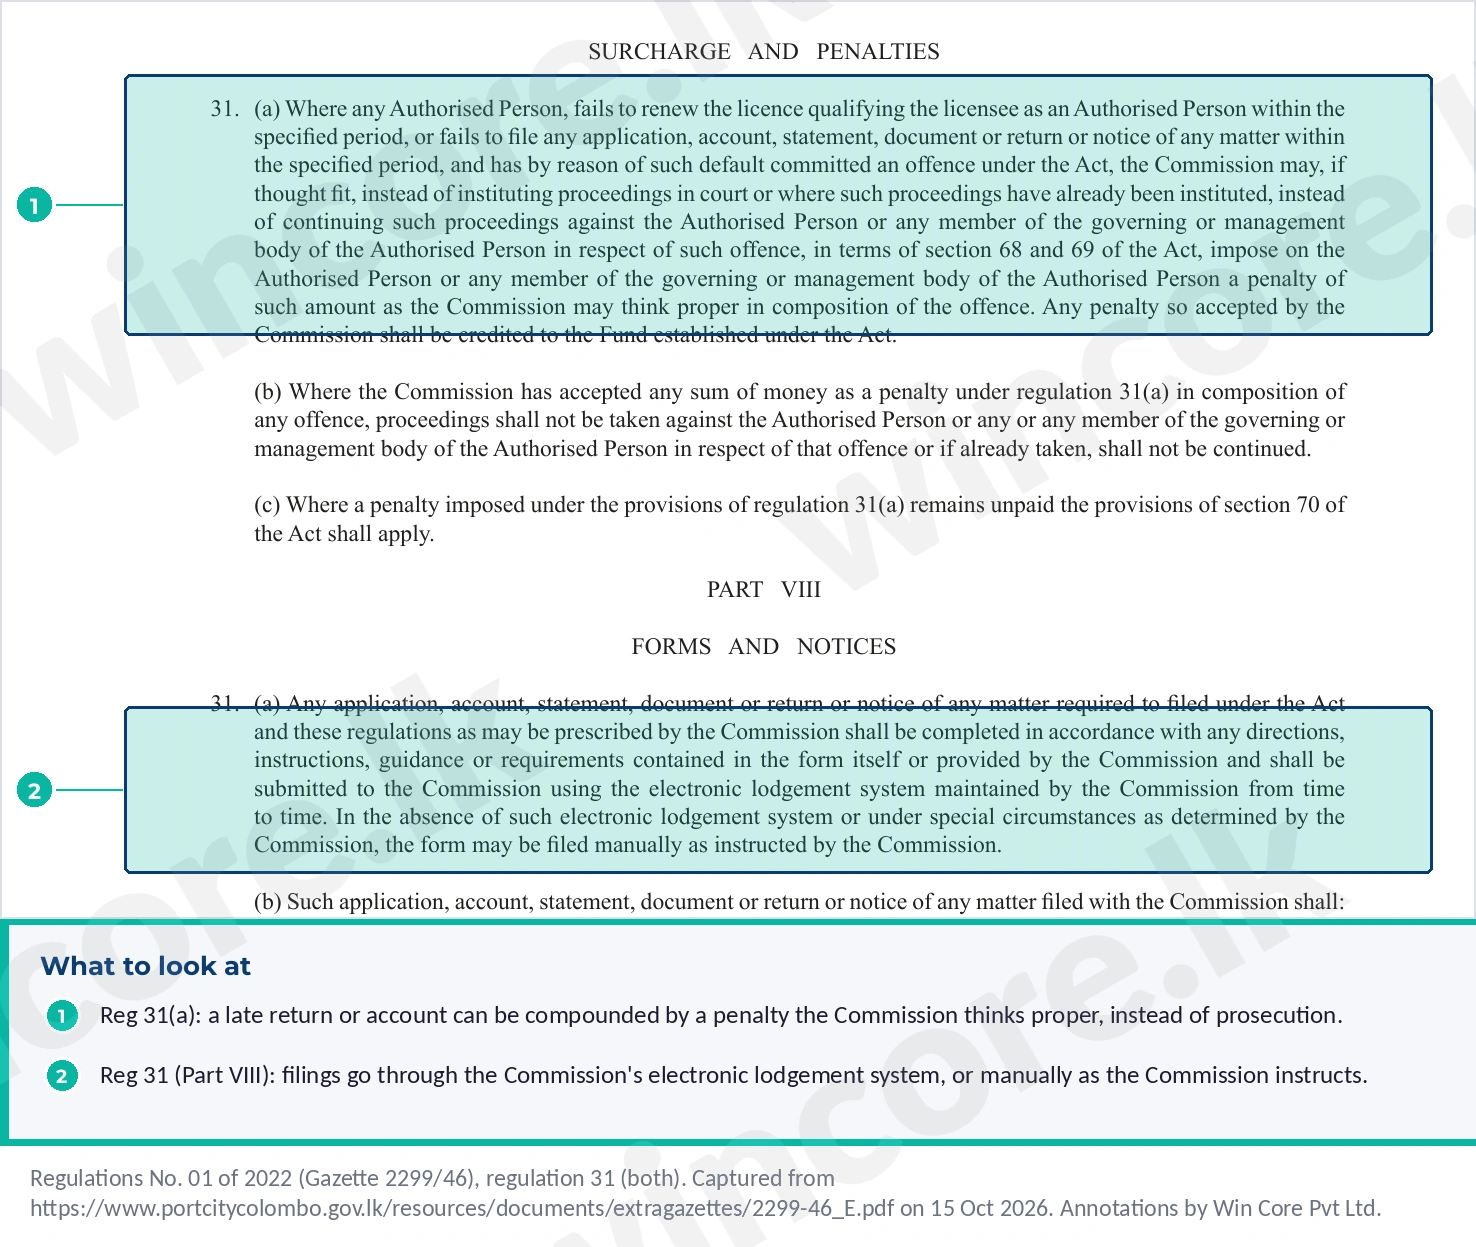
A short digression on numbering. The Gazette prints two regulations numbered 31: one on penalties and one on forms. Regulation 21(c)(ii) also refers to "an automatic penalty ... as specified in regulation 32", but the text we read has no regulation numbered 32. Citing "reg 31" alone is ambiguous, so we name the Part. Which brings us back to the relay: the dates themselves, in regs 16 and 17, are clear.
A worked timeline shows how early approval pulls the return forward
Take a hypothetical Port City Authorised Person, a commodities trading office with a 31 March year end. Its year ends 31 March 2027. The auditors sign their report on 24 July, and the authorised signatory approves and signs the accounts on 28 July 2027.
- Accounts: submitted to the Commission by 30 September 2027 (reg 16(a)). Sending them on approval is simplest.
- Annual return: due by about 27 August 2027, thirty days from approval (reg 17), more than a month before the accounts deadline.
- Renewal: the next renewal application, thirty days before licence expiry, must confirm the return "remains true and accurate" (reg 22(a)).
If the signatory had approved the accounts on 20 October instead, the accounts would be late under reg 16(a), and the return would be due by about 19 November.
What a business must do
- Agree the year end with the Commission if it is not 31 March.
- Set up the ledger to separate Port City income from the start of the year. Our accounting services build this into the chart of accounts.
- Book the audit to finish well before the six-month date; our audit support prepares the schedules auditors ask for.
- Record the approval date on the signed accounts.
- Diary the annual return for thirty days after approval, the same day.
- File through the Commission's lodgement system, or as it instructs.
- Keep copies and records for ten years.
- Use the same accounts for the income tax return.
Checklist: documents needed
- Commission's written agreement to any year end other than 31 March
- Ledger with Port City income and profit identified separately
- Audited financial statements, signed by the authorised signatory, with the approval date
- Proof of submission of the accounts to the Commission
- Completed Schedule IV annual return and its working sheet
- Lodgement record or the Commission's filing instruction
- Copies of everything filed, kept for ten years
Common misreadings
- "The return is due six months after year end." The return is due thirty days after approval of the accounts; the accounts are due at six months.
- "Late accounts give more time for the return." The return clock runs from approval, but the late accounts are already a breach.
- "Only tax-paying businesses need audited accounts." Regulation 16 applies to every Authorised Person.
- "There is a fixed late fee." Composition is discretionary under reg 31(a).
What this means for you
Plan backwards from 30 September for the audit, and forwards from the approval date for the return. Treat the approval date as the most important date in the file. Late filings risk prosecution under s.68 or a composition penalty, and can feed into licence cancellation. A Port City company may also have Companies Act filings to the Registrar, which run on their own dates; our Form 15 annual return guide, our statutory secretarial services and the annual filing checklist cover that side.
Open points. Auditor qualifications or auditing standards for reg 16(a): not stated. How the thirty days in reg 17 are counted: not defined. Regulation 21(c)(ii) refers to a penalty in "regulation 32": we did not find one. Which of s.68(1)(e) and s.68(3) applies to a late filing: not stated. Whether the Commission has issued any notice on composition amounts: none found on its site on 21 October 2026. How these rules sit with Companies Act duties for a Sri Lankan company that is also an Authorised Person: not covered here.
FAQ
When are Port City audited accounts due to the Commission?
Port City audited accounts are due within six months of 31 March, so by 30 September, or within six months of the end of another twelve-month period agreed with the Commission. They must be prepared by the Authorised Person, audited by an auditor, approved and signed by the authorised signatory, and then submitted, all within that window under regulation 16(a).
When is the CPCEC annual return due?
The annual return is due within thirty days from the approval of the audited accounts, under regulation 17. It does not run from 31 March or from the auditor's report. Accounts approved early in the year therefore pull the return forward, sometimes well before the 30 September accounts deadline, so the approval date is the one to diary.
Is there a fixed penalty for filing Port City accounts late?
No fixed late fee is set in the regulations. A late filing is an offence under section 68 of the Port City Act, with fines and imprisonment on conviction, but regulation 31(a) of Part VII lets the Commission instead accept a penalty in composition of the offence, in an amount it thinks proper.
Can a Port City company use a year end other than 31 March?
Yes, if the other twelve-month period is agreed with the Commission and, where applicable, any other relevant regulatory authority, as regulation 16(a) provides. The six-month deadline for the accounts then runs from the end of that agreed period, and the annual return still follows thirty days after the accounts are approved.
Do we file the accounts and return online?
Yes, where the Commission's electronic lodgement system is available, under the regulation 31 in Part VIII. Where there is no such system, or in special circumstances the Commission decides, the form may be filed manually as the Commission instructs. Either way, keep a copy of everything you file for ten years.
This article is general information, not advice for your specific situation.
Talk to us. If your audit is running close to 30 September or your accounts have just been approved, book a consultation at our contact page and we will map both deadlines for you.
WinCore Pvt Ltd
References
- Colombo Port City Economic Commission. Regulations for Registration, Licensing, Authorisation and other Approvals of Authorised Persons No. 01 of 2022, Gazette Extraordinary No. 2299/46 (28 September 2022), regs 16, 17, 21, 22, 27, 28, 31 (Parts VII and VIII) and Schedule IV. https://www.portcitycolombo.gov.lk/resources/documents/extragazettes/2299-46_E.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Colombo Port City Economic Commission Act, No. 11 of 2021, s.68(1) and (3). https://www.portcitycolombo.gov.lk/resources/documents/acts/11-2021_E.pdf . Primary. Accessed 21 October 2026. Section 68 checked as not amended by the CPCEC (Amendment) Act No. 1 of 2026.
- Colombo Port City Economic Commission. Schedule IV: Annual Return (blank form). https://www.portcitycolombo.gov.lk/resources/documents/forms/Schedule%204%20-%20ANNUAL%20RETURN.pdf . Primary. Accessed 15 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
One year in Colombo Port City on one page: licence renewal, audited accounts, the annual return, income tax and payroll, with the rule behind each date.

Close your books before the March 31 deadline to reduce audit risk and start with clean numbers. A practical 10-step year-end guide for SMEs.
A late annual return rarely stands alone. Fix the officers, file beneficial ownership at once, then each overdue return with its AGM, then tax.