
Port City BSI tax exemption: which gazette gives what relief
Two BSI schemes, two kinds of Order. Which Port City gazettes carry the withholding clause, which give 7.5 percent, and how to read yours.
On this page
Last verified against the primary sources on 21 October 2026.
A Port City BSI tax exemption is whatever your own section 53 Order says, and nothing more. Orders made under the 2023 BSI regulations (Gazette 2343/60), such as the four Primary BSI Orders of 14 July 2025, exempt the business's income for 25 years and add that "all payments made shall be exempted from the Withholding Tax". Orders made under the 2025 regulations (Gazette 2454/62 of 20 September 2025) say nothing about withholding: the April 2026 Secondary BSI Orders we read charge corporate income tax at 7.5 percent for four years from commencement of commercial operations, beside import, foreign exchange and other reliefs, and the May 2026 Primary BSI Order exempts profits for ten years once the building phase ends. A Port City licence on its own gives neither.
So the useful question is "what does our own Order say?" For example, a business planning a Port City application reads a summary quoting a 25-year tax holiday and plans its budget on it. That question is answered by reading one document, its own Order, not a summary. This article shows which gazettes carry which relief, and how to read your own.
Every BSI's relief is set by its own section 53 Order
The Colombo Port City Economic Commission Act, No. 11 of 2021 lets the Commission identify businesses as Businesses of Strategic Importance and grant them exemptions or incentives "in accordance with the regulations made under this Act". For tax, those exemptions "may be granted, either in full or part, and from all or any of the enactments set out in Schedule II" [1, s.52(3)]. Schedule II lists thirteen enactments, from the Inland Revenue Act and the VAT Act to the Customs Ordinance and the Foreign Exchange Act.
Once the Cabinet approves a designation, the Minister must, by Order published in the Gazette, specify "the specific exemptions from those enactments listed in Schedule II to this Act that are applicable to such Business of Strategic Importance", with commencement and expiry dates and the applicant's name [1, s.53(3)]. The Order is the grant. The regulations are the menu the Order is drawn from, and the menu has changed.
The CPCEC (Amendment) Act, No. 1 of 2026 adds a Ministry of Finance technical analysis and five-yearly reviews [2, s.13], but it does not rewrite an existing Order by itself. So if you want to know what your company has, you need one document: the section 53 Order with your company's name in Schedule I. Its Schedule III lists, enactment by enactment, what you get and for how long.
2023-scheme and 2025-scheme Orders give different reliefs
BSI Orders have been made under two sets of guidelines.
The 2023 regulations, Regulations No. 2 of 2023 (Gazette 2343/60 of 4 August 2023), let a Primary BSI choose exemptions from the Schedule II enactments "for a period of twenty-five years" followed by a ten-year 50 percent rate incentive, or a 300 percent enhanced capital allowance scheme [3, reg 3], and gave Secondary BSIs exemptions or incentives under the Schedule II enactments for twenty-five years from the date of the Order [3, reg 5]. Regulation 6 required designation "within a period of two years from the date of publication of these regulations", so by early August 2025 [3, reg 6], and the Commission says Gazette 2343/60 "expired on 3 August 2025" [4]. The regulations themselves never mention withholding tax; the withholding clause comes from the Orders made under them, which read generously. Item 1 of Schedule III, the Inland Revenue Act line, typically says "(a) all income, profits, and dividends distributed shall be exempt from all taxes specified under this Act; (b) all payments made shall be exempted from the Withholding Tax specified under this Act" [5][6].
The 2025 regulations, Regulations No. 1 of 2025 (Gazette 2454/62 of 20 September 2025), apply to any business identified as a BSI on or after they came into effect [7, reg 2]. They are much tighter. A Primary BSI (a plot developer meeting one of four investment categories) gets a corporate income tax exemption of 8 to 15 years, but it only "commence[s] upon expiry of the project implementation period" [7, reg 4(b)]. A Secondary BSI, which is everyone else, gets corporate income tax "at the concessionary rate of 7.5% for four (04) years commencing from the date of commencement of commercial operations" [7, reg 6(b)]. That 7.5 percent is only the income tax item. The same regulation exempts a Secondary BSI from the Customs Ordinance, the Ports and Airports Development Levy Act and the Sri Lanka Export Development Act until commercial operations start [7, reg 6(a)], and from the Entertainment Tax Ordinance, the Foreign Exchange Act and the Termination of Employment of Workmen Act from the date of its Order [7, reg 6(c)]. A Primary BSI gets a matching set of non-income tax reliefs [7, reg 4(a) and (c)]. Regulation 7 adds that the incentives are "non-negotiable and non-renewable". There is no withholding item anywhere in the 2025 menu. Material still quoting 25-year holidays for new designations is describing the old menu, a point law firm commentary on the 2025 regulations makes too [8].
Every 2026 Order we read follows the 2025 menu exactly, while an Order made under the 2023 scheme keeps its own terms.
Port City BSI tax exemption, gazette by gazette
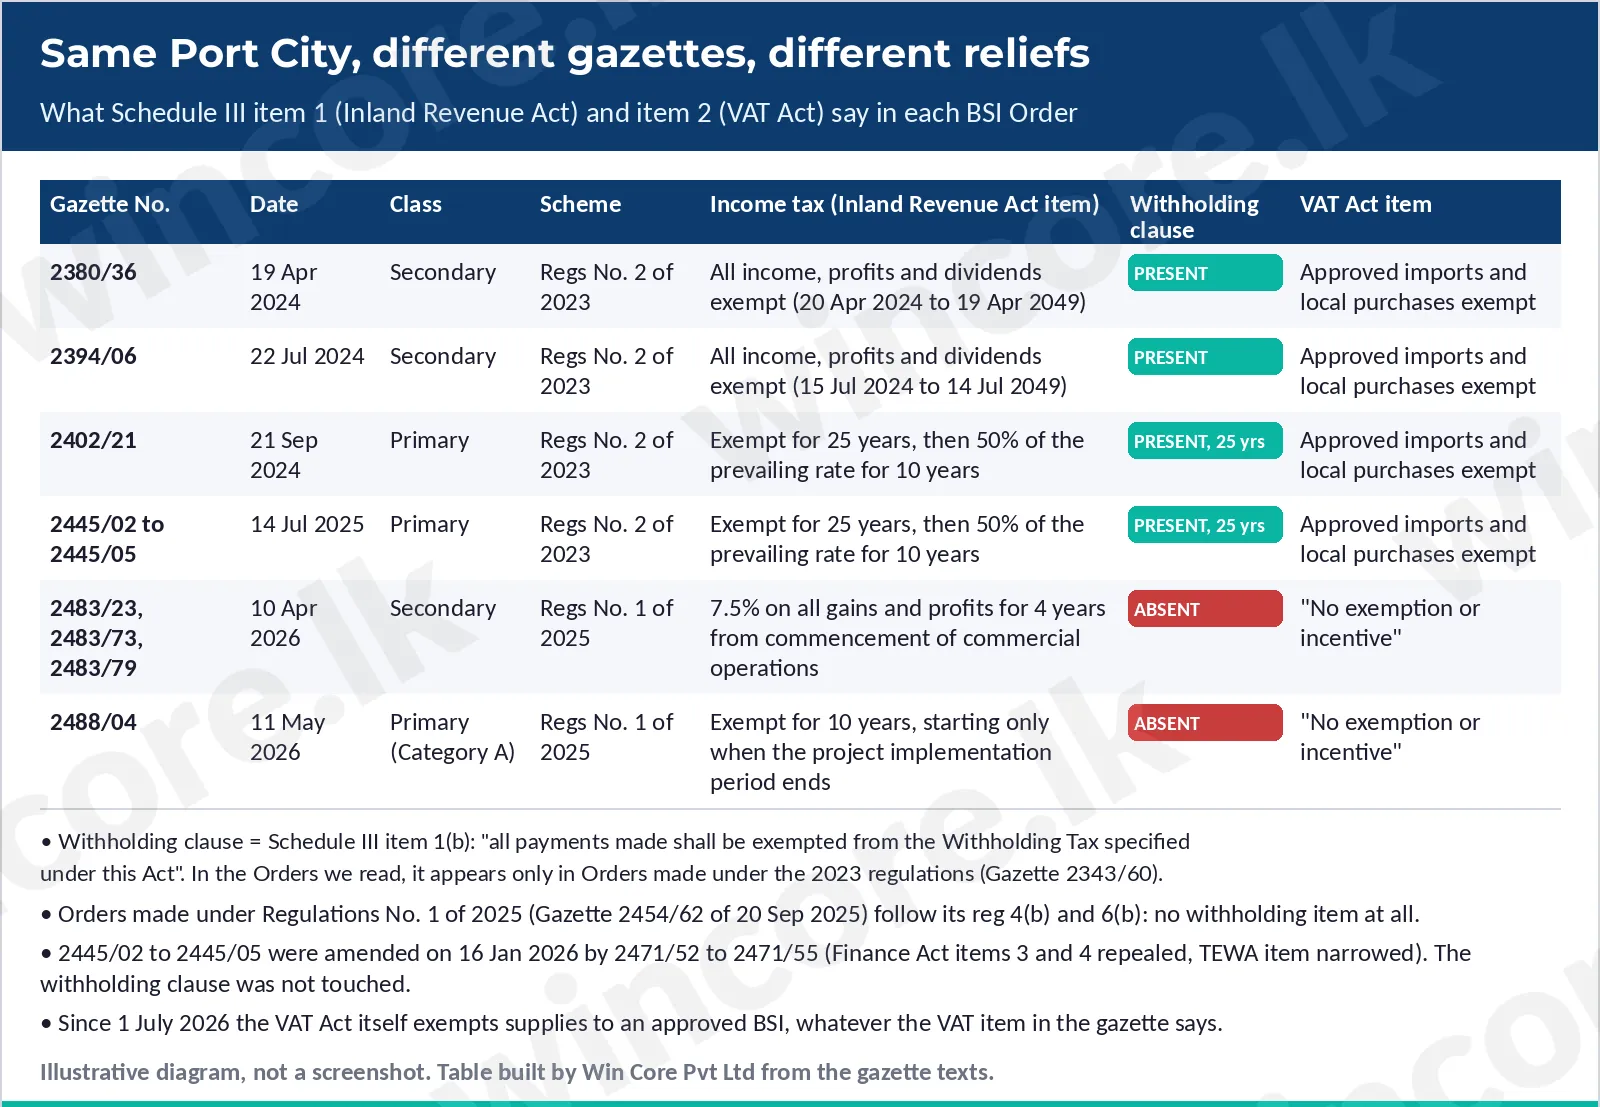
We read a dozen BSI Orders and four amending Orders on documents.gov.lk in October 2026, and re-read seven of them at source on 21 October 2026. The table below sets out the lines that matter for most finance teams: what item 1 grants under the Inland Revenue Act, and whether the withholding clause is there.
The July 2025 Primary BSI Orders carry the clause. Gazettes 2445/02, 2445/03, 2445/04 and 2445/05, all published on 14 July 2025, designate four plot developers as Primary BSIs under the 2023 scheme. Each Schedule III item 1 reads: "(a) all income, profits, and dividends distributed shall be exempted from all taxes specified under this Act for the first twenty-five years; (b) all payments made shall be exempted from the Withholding Tax specified under this Act for the first twenty-five years; (c) After the end of the aforesaid twenty-five year period, 50% incentive from the prevailing corporate tax rate ... shall be given for a period of ten years" [9]. In the Orders we rechecked, the income tax line runs from 14 July 2025 to 13 July 2060.
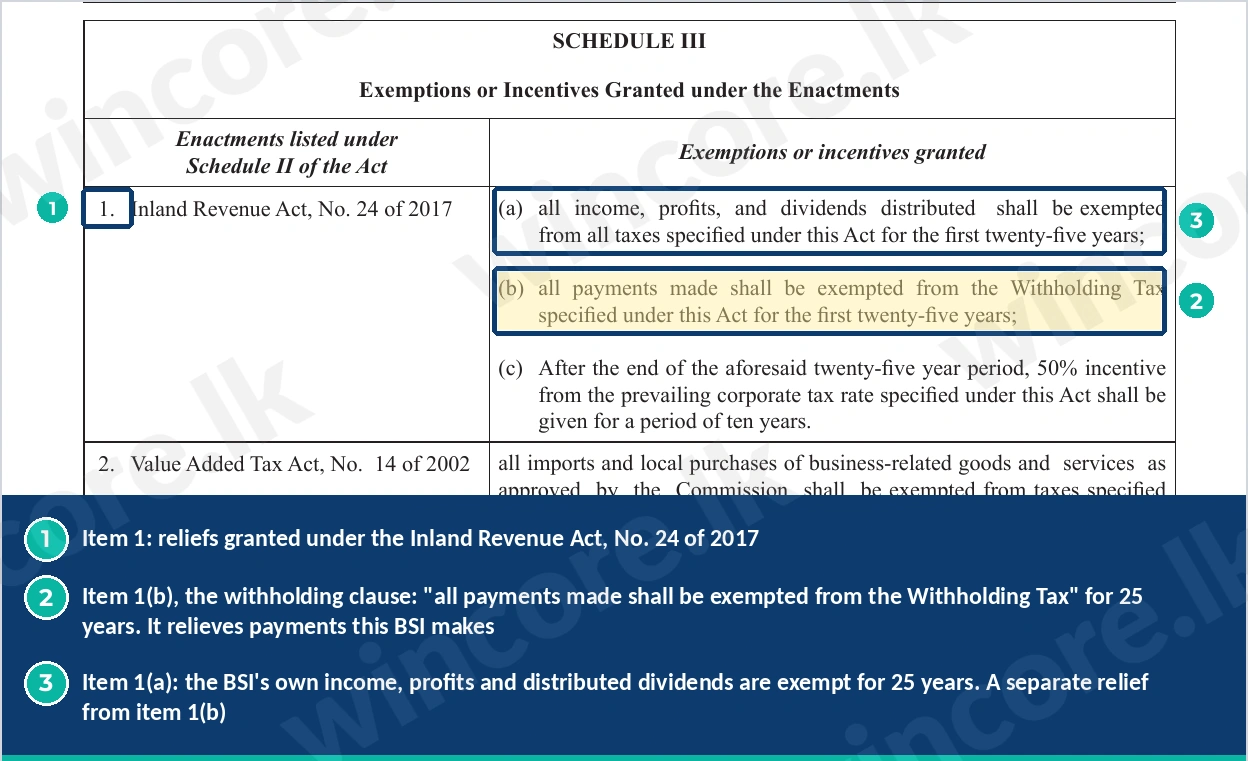
Some Secondary BSIs carry it too. This is the bit that makes "Primary gets it, Secondary doesn't" wrong. Gazette 2380/36 (19 April 2024) and Gazette 2394/06 (22 July 2024) are Secondary BSI Orders under the 2023 scheme, and both carry the same item 1(a) and 1(b), with no 25-year wording inside the item: the dates in their Schedule IV run from April and July 2024 to April and July 2049 [5][6].
The April 2026 Secondary BSI Orders do not. Gazettes 2483/23, 2483/73 and 2483/79, all of 10 April 2026, designate three businesses as Secondary BSIs under the 2025 scheme. Item 1 in each reads "Charge corporate income tax under the Inland Revenue Act, No. 24 of 2017 on all gains and profits, at the concessionary rate of 7.5%", from the date of commencement of commercial operations to four years after it [10]. Nothing on withholding. Item 2 on the VAT Act says "No exemption or incentive is granted under this Act."
Nor does the newest Primary Order. Gazette 2488/04 of 11 May 2026 designates a residential tower developer as a Category A Primary BSI under the 2025 scheme. Item 1 grants "Exemptions of all gains and profits from the corporate income tax" for ten years, starting "Upon expiry of the Project Implementation Period" [11]. No withholding clause, no VAT item ("No exemption or incentive is granted under this Act"), and no income tax relief at all while the building is going up.
Amendments matter as much as originals. On 16 January 2026 Gazettes 2471/52 to 2471/55 amended each of the four July 2025 Orders: items 3 and 4 (the two Finance Acts) were repealed and the Termination of Employment of Workmen Act item narrowed to sections 2, 11 and 12 [12]. The withholding clause survived. You would only know that by finding the amending Order. Search documents.gov.lk for your original number and the amendment usually shows up in the same results, if you look.
Gazette instruments: CPCEC Act No. 11 of 2021 ss.52 and 53; Regulations 2343/60 and 2454/62; Orders as listed in the table and References. Official source: documents.gov.lk. Last verified: 21 October 2026.
Review the separate conditions for Port City employee income relief before extending a business concession to payroll.
The withholding clause relieves the payer, not the payee
Read the clause "all payments made shall be exempted from the Withholding Tax specified under this Act" where it sits. It is item 1(b) of a schedule headed "Exemptions or Incentives Granted under the Enactments", in an Order that names one business and grants reliefs to that business. Item 1(a) deals with that business's own income. Item 1(b) deals with payments, and the natural reading is payments that business makes: fees, interest and the other payments on which the Inland Revenue Act would make it a withholding agent. The withholding obligation sits on the payer. An exemption granted to the payer switches off the payer's duty. It cannot reach into someone else's books.
That gives two practical rules.
If your own Order has item 1(b), the clause covers what you pay out. On our reading, a Primary BSI under one of the July 2025 Orders should not need to deduct withholding tax on its payments for the first twenty-five years.
If the other party's Order has item 1(b), it does nothing for you. Suppose a company you pay is a 2023-scheme BSI and you are any other business, BSI or not. Its item 1(b) covers its own payments, not the fees you pay it. Your withholding duty on that payment comes from the Inland Revenue Act and IRD Circular SEC/2026/E/04, which sets the rates and the payer exclusions, and those exclusions do not mention BSIs [13]. If the payee's own income is exempt under its item 1(a), the circular's route is specific: "The persons who have exempt amounts other than above exempt amounts are required to obtain income tax exemption confirmation letter for such amounts from the CGIR and submit to WHA prior to the WHT deduction" [13, part 2]. No letter, keep deducting. The WHT registration guide covers registering as a withholding agent. The WHT tax calculator works out the deduction.
Now the honest caveat. The words "all payments made" do not say "by whom". We think the payer reading is the only one that fits the structure of the Order, the Act's grant "in so far as it relates to its operations" [1, s.52(3)] and the circular's separate exemption-letter route for payees. But we have found no IRD notice, circular or ruling that applies item 1(b) either way. If you are a 2023-scheme BSI planning to stop deducting on the strength of 1(b), put the question to the IRD in writing first. That is a few weeks' delay against an assessment with penalties and interest.
What this means for you
- Find your own section 53 Order. Search documents.gov.lk (Publications, Extra Gazettes) for the gazette number on your CPCEC correspondence [15]. Download the English text. If you do not know the number, the Commission's designation letter or your BSI agreement will have it.
- Search for amendments. Search the number again and look for a later Order that "amend[s] the Order published in the Gazette Extraordinary No." yours. Read the two together.
- Read Schedule III item 1 line by line. Is there an item 1(b)? What are the commencement and expiry dates in the date table? If your relief starts at "commencement of commercial operations", know that date and keep the evidence for it.
- For each counterparty, ask two questions, not one. Is it resident or non-resident for the Inland Revenue Act? Has it given you a CGIR exemption confirmation letter? Its BSI status alone answers neither.
- Do not import VAT assumptions from the gazette either. Since 1 July 2026 supplies to an approved BSI are VAT exempt under the VAT Act itself, even where the gazette says "No exemption" under the VAT Act [14]. We cover that in supplies to a BSI are VAT exempt from 1 July 2026.
- Know your rate and your dates, and file regardless. Every BSI, exempt or not, files an income tax return.
If you want a second reading of your Order and your withholding set-up, our income tax services cover exactly this review, and the corporate tax calculator shows the effect of a concessionary rate.
Checklist: documents needed
- Your section 53 Order (English text) with its gazette number
- Every amending Order found by searching that number on documents.gov.lk
- Your Commission designation letter or BSI agreement under section 32
- Evidence of your commencement of commercial operations date, if your relief runs from it
- For each BSI counterparty: its Order number and Schedule III
- For each exempt payee: its CGIR income tax exemption confirmation letter
- For each payee: evidence of its residence status
FAQ
Is a Port City BSI exempt from withholding tax?
Only if its own Order says so. Check Schedule III item 1 for a (b) line reading "all payments made shall be exempted from the Withholding Tax". In the Orders we read, 2023-scheme Orders (Primary and some Secondary) carry it, and the 2025-scheme Orders of 2026 do not. Never rely on another company's gazette or on general statements about Port City.
Can we pay a BSI supplier without deducting withholding tax?
Not on the strength of its withholding clause. On our reading that clause covers payments the BSI itself makes. You can stop deducting only if the payment is an exempt amount for the payee and the payee gives you a CGIR income tax exemption confirmation letter before you pay, which is the route IRD Circular SEC/2026/E/04 sets out [13].
Do the 2023 or the 2025 BSI regulations apply to us?
It depends on when you were identified as a BSI and what your Order cites. Schedule I of each Order names the regulation it applies. Orders citing Regulations No. 2 of 2023 keep their own 25-year style reliefs; Orders citing Regulations No. 1 of 2025 follow its tighter menu, which has no withholding item [7].
Where do I find a Port City BSI gazette?
Search documents.gov.lk, Publications, Extra Gazettes, by the gazette number, and download the English text. Search the same number again for any amending Order, and read the two together, because an amendment sits under a different gazette number. The Commission also publishes many Port City instruments on portcitycolombo.gov.lk under Laws and regulations [15][16].
Talk to us. If you want your BSI Order read line by line and your withholding and VAT set-up matched to it, contact us at our contact page.
WinCore Pvt Ltd
References
- Parliament of Sri Lanka. Colombo Port City Economic Commission Act, No. 11 of 2021, ss.41(6), 52 and 53, Schedule II. https://www.portcitycolombo.gov.lk/resources/documents/acts/11-2021_E.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Colombo Port City Economic Commission (Amendment) Act, No. 1 of 2026, s.13 (amending s.52) and s.14 (new ss.52A to 52E). https://www.portcitycolombo.gov.lk/resources/documents/acts/01-2026_E.pdf . Primary. Accessed October 2026.
- Minister of Finance. Colombo Port City (Guidelines on the Grant of Exemptions or Incentives to Businesses of Strategic Importance) Regulations, No. 2 of 2023, Gazette Extraordinary No. 2343/60 (4 August 2023), regs 5 and 6. https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2343-60_E_1784565136.pdf . Primary. Accessed 21 October 2026.
- Colombo Port City Economic Commission. CPCEC: ushering in a new era of stability, investor confidence and regulatory reform, news release (24 September 2025). https://www.portcitycolombo.gov.lk/news/20250924/cpcec-ushering-in-a-new-era-of-stability-investor-confidence-and-regulatory-reform . Primary (official). Accessed October 2026.
- Order under s.53, Secondary BSI, Gazette Extraordinary No. 2380/36 (19 April 2024), Schedule III item 1 and date table. https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2380-36_E_1784565853.pdf . Primary. Accessed October 2026.
- Order under s.53, Secondary BSI, Gazette Extraordinary No. 2394/06 (22 July 2024), Schedule III item 1 and date table. https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2394-06_E_1784566055.pdf . Primary. Accessed October 2026.
- Minister of Finance. Colombo Port City (Guidelines on the Grant of Exemptions or Incentives to Businesses of Strategic Importance) Regulations, No. 1 of 2025, Gazette Extraordinary No. 2454/62 (20 September 2025), regs 2 to 8. https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2454-62_E_1784567464.pdf . Primary. Accessed 21 October 2026.
- AW Chambers. Tax, incentives and the Business of Strategic Importance, Port City Colombo guide. https://www.awchambers.com/port-city-colombo/guide/tax-incentives-and-the-business-of-strategic-importance . Secondary (corroboration). Accessed October 2026.
- Orders under s.53, Primary BSIs, Gazettes Extraordinary Nos. 2445/02, 2445/03, 2445/04 and 2445/05 (14 July 2025), Schedule III item 1; and No. 2402/21 (21 September 2024), Schedule III item 1. https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2445-02_E_1784567218.pdf ; https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2445-03_E_1784567219.pdf ; https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2445-04_E_1784567219.pdf ; https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2445-05_E_1784567219.pdf ; https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2402-21_E_1784566254.pdf . Primary. Accessed October 2026.
- Orders under s.53, Secondary BSIs, Gazettes Extraordinary Nos. 2483/23, 2483/73 and 2483/79 (10 April 2026), Schedule III items 1 and 2. https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2483-23_E_1784568095.pdf ; https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2483-73_E_1784568114.pdf ; https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2483-79_E_1784568116.pdf . Primary. Accessed October 2026.
- Order under s.53, Primary BSI, Gazette Extraordinary No. 2488/04 (11 May 2026), Schedules I and III. https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2488-04_E_1784568182.pdf . Primary. Accessed October 2026.
- Orders under s.53 amending Gazettes 2445/02 to 2445/05, Gazettes Extraordinary Nos. 2471/52, 2471/53, 2471/54 and 2471/55 (16 January 2026). https://documents.gov.lk/api/content-file-proxy?file=%2Fextra-gazette-content%2F2471-52_E_1784567854.pdf (and 2471-53, 2471-54, 2471-55 at the same path). Primary. Accessed October 2026.
- Inland Revenue Department. Circular to Withholding Agents: Deduction of Withholding Tax and Advance Income Tax, Circular No. SEC/2026/E/04 (8 June 2026), parts 1 and 2. https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2026_E_04_E.PDF . Primary. Accessed 21 October 2026.
- Inland Revenue Department. Notice to the Taxpayers: Amendments to the Value Added Tax Act, No. 14 of 2002, SEC/PN/VAT/2026-03 (3 July 2026), item 15. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/799/PN_VAT_2026-03_New_E.pdf . Primary. Accessed October 2026.
- Documents.gov.lk (Department of Government Printing). Extra Gazettes search. https://documents.gov.lk/web/extra_gazettes . Primary (official portal). Accessed October 2026.
- Colombo Port City Economic Commission. Laws and regulations. https://www.portcitycolombo.gov.lk/laws-and-regulations . Primary (official portal). Accessed October 2026.
- Inland Revenue Department. Consolidated Text of the Inland Revenue Act No. 24 of 2017, incorporating amendments up to 31 March 2025, s.69(4). https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary. Accessed 21 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
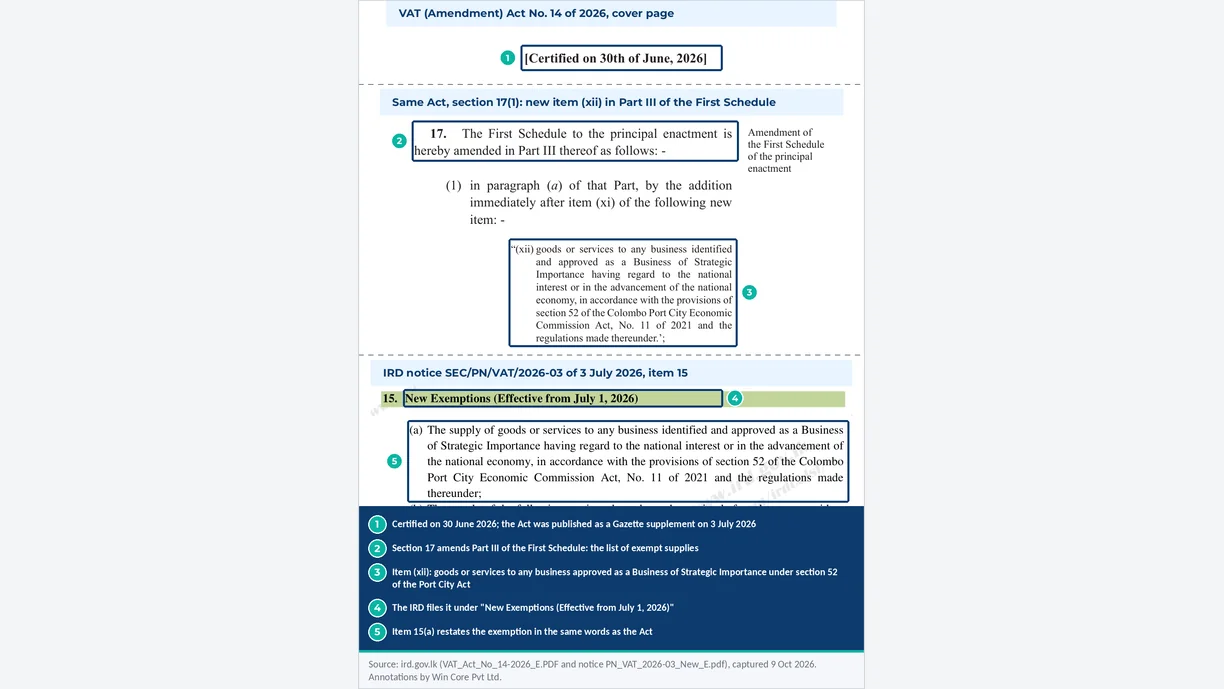
From 1 July 2026 supplies to a Port City Business of Strategic Importance are VAT exempt. The legal basis, invoicing and the input VAT effect.

WHT registration works best when withholding-agent onboarding, payment mapping, deduction, and remittance controls are designed as one process.
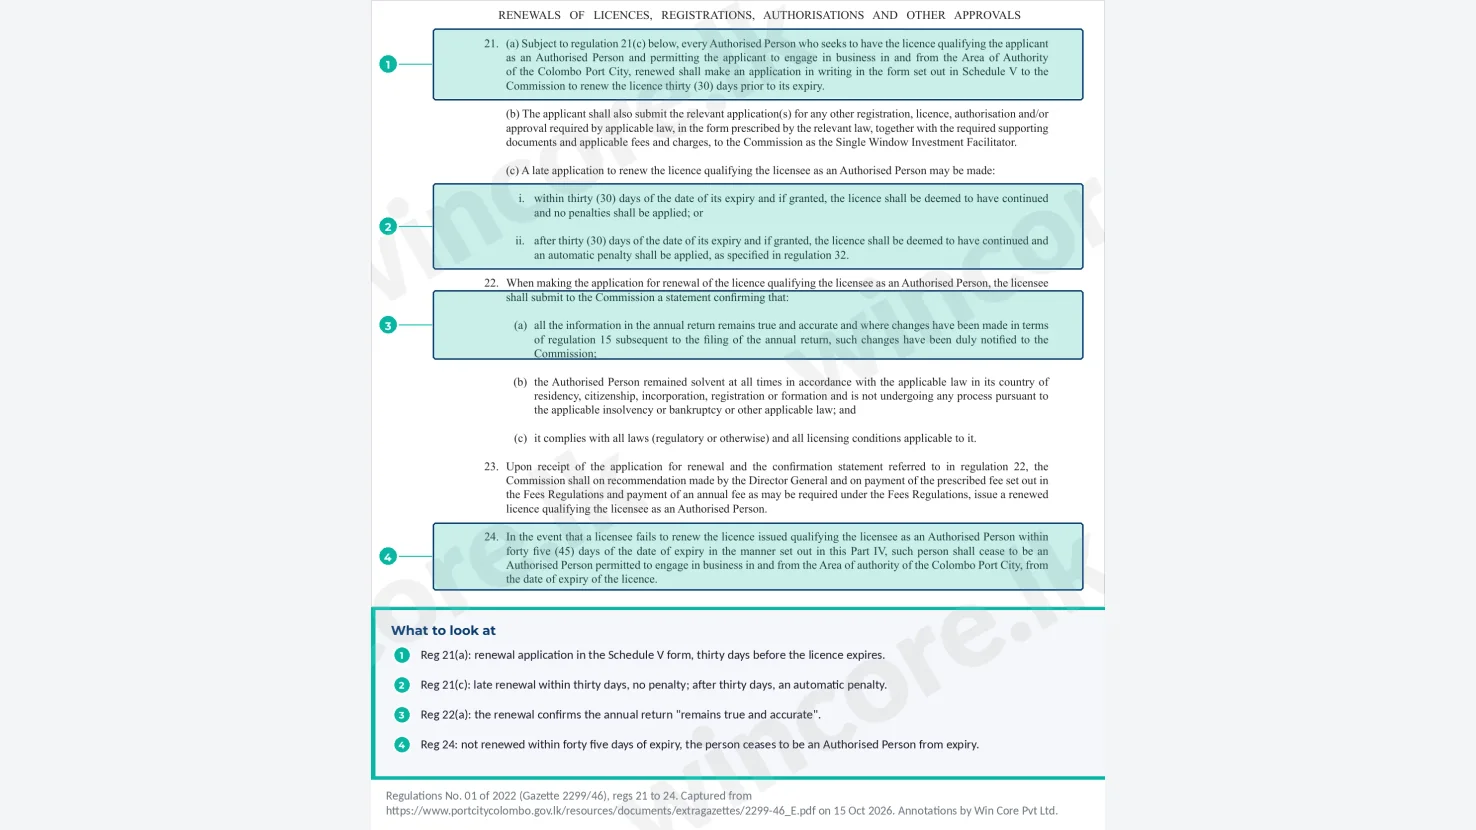
One year in Colombo Port City on one page: licence renewal, audited accounts, the annual return, income tax and payroll, with the rule behind each date.