
Lease stamp duty: Rs 20 per Rs 1,000 of aggregate rent from 1 April 2025
Stamp duty on a lease is Rs 20 per Rs 1,000 of the aggregate rent from April 2025. Who pays, how to pay, the exemptions and worked examples.
On this page
Last verified against the primary sources on 15 October 2026. Material added on 21 October 2026 was verified that day.
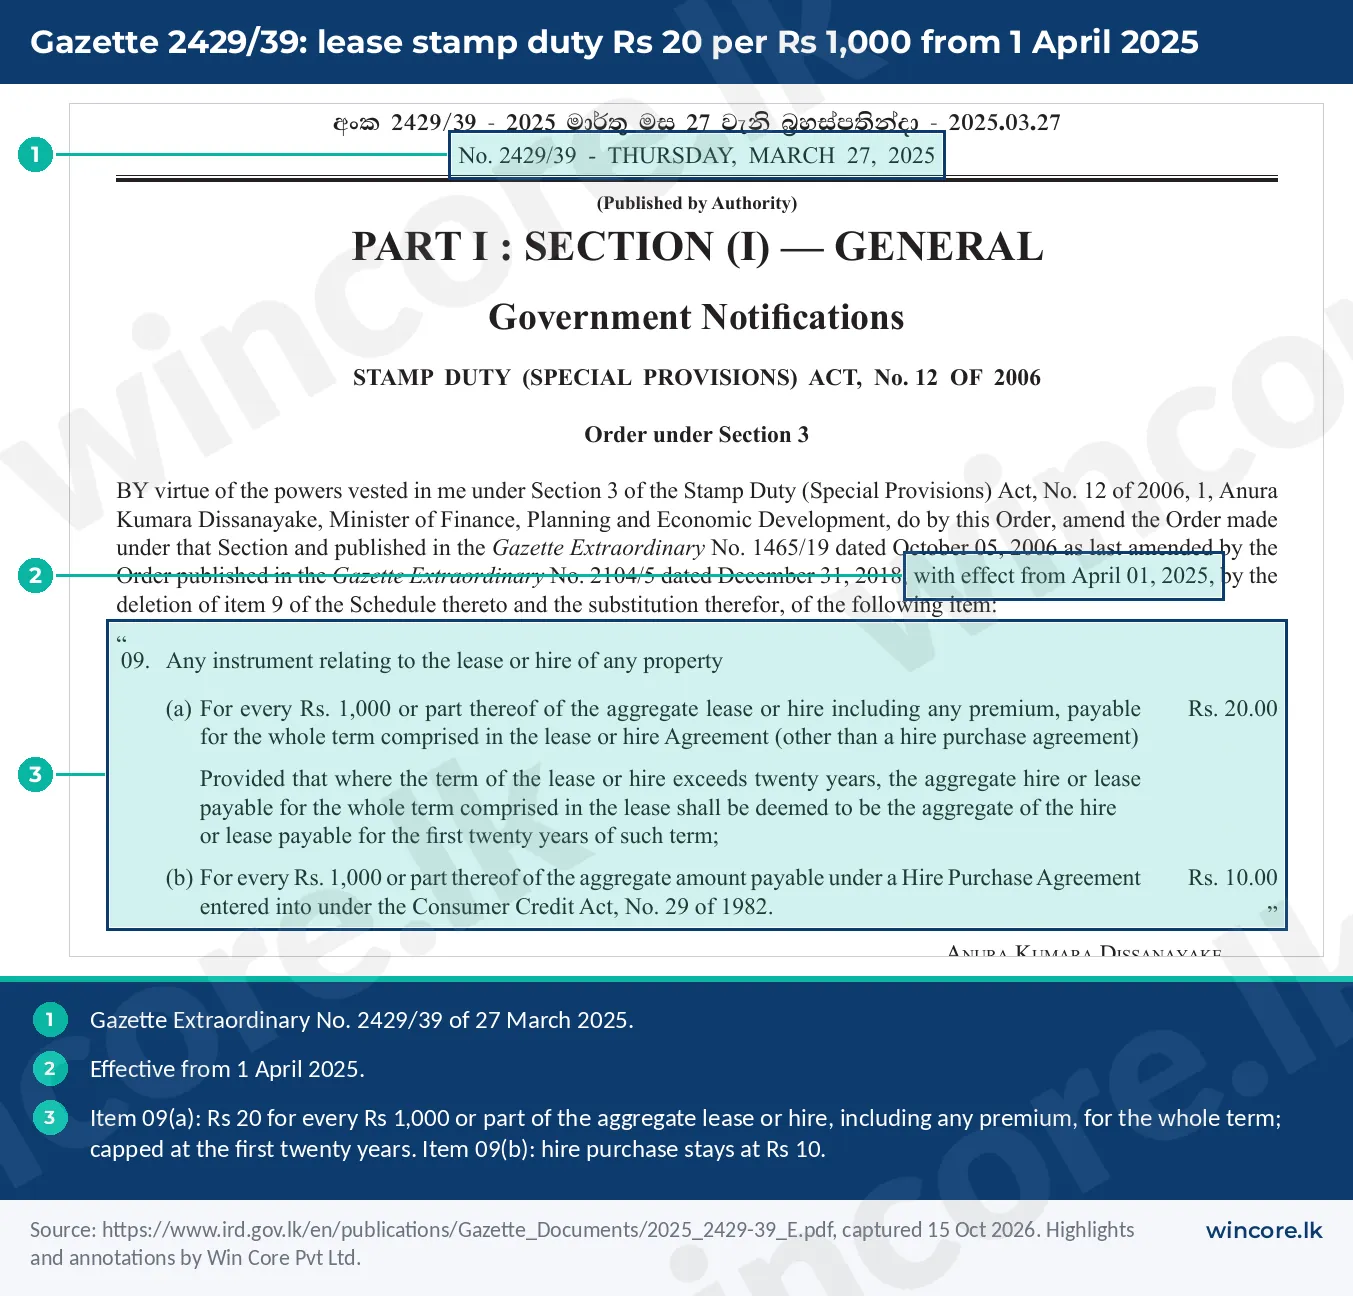
A three-year warehouse lease at Rs 100,000 a month looks straightforward until the stamp is calculated. The duty is not 2 percent of the first year's rent. It is Rs 20 for every Rs 1,000 or part of Rs 1,000 of the aggregate lease rent, including any premium, payable for the whole term, and where the term exceeds twenty years only the first twenty years count [1]. On the three-year example the aggregate is Rs 3,600,000 and the duty is Rs 72,000. Unless the parties agree otherwise, the lessee pays [2].
The rate doubled on 1 April 2025. Gazette Extraordinary No. 2429/39 of 27 March 2025, an Order under section 3 of the Stamp Duty (Special Provisions) Act, No. 12 of 2006, replaced item 9 of the Schedule to the 2006 Order in Gazette 1465/19, which had charged Rs 10 [1] [3]. Hire purchase agreements under the Consumer Credit Act, No. 29 of 1982 stay at Rs 10 per Rs 1,000 [1].
This guide covers the exemption for small building rents, the aggregate, the rounding, who pays, how to pay and what happens if a lease is under-stamped. It does not cover stamp duty on deeds of transfer or mortgages, or withholding tax on the rent itself; our guide on advance income tax on rent covers that.
Checklist: documents needed
- The lease, or the final draft, showing monthly rent, any rent steps, the term and any premium or key money
- Any clause that says who bears the stamp duty
- A working paper showing the aggregate, the twenty year cap if relevant, and the rounding
- For immovable property: the bank certificate of payment, to be affixed to the lease
- For other leases: adhesive stamps to the required value, cancelled on execution
- A copy of the stamped and executed lease for the file
Step 1. Check the instrument is chargeable and not exempt
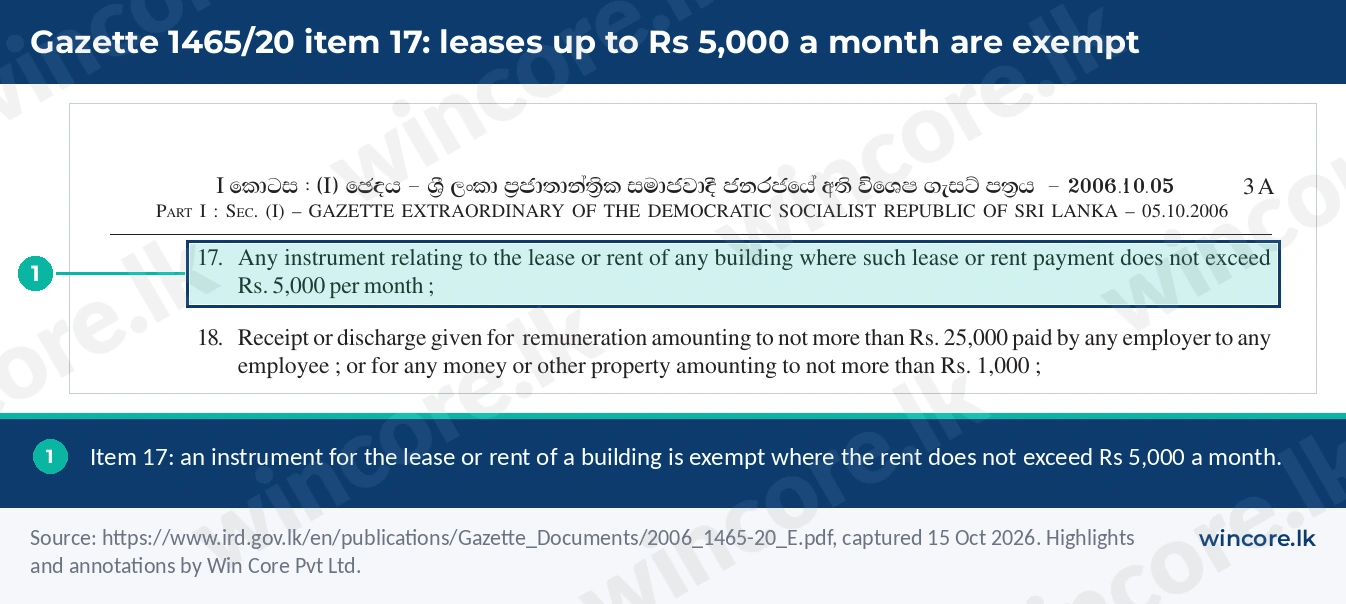
What to do. Item 9 charges "any instrument relating to the lease or hire of any property" [1]. Before calculating, check the exemptions in the Order under section 5 of the Act, published in Gazette 1465/20. Item 17 exempts "any instrument relating to the lease or rent of any building where such lease or rent payment does not exceed Rs. 5,000 per month" [4]. A small shop or store room at Rs 5,000 a month or less needs no stamp; at Rs 5,001 it does. Item 13, as substituted by Gazette 1546/7 of 22 April 2008, exempts "any deed of mortgage or lease affecting any air-craft registered under the Air Navigation Act (Chapter 365) or any ship registered under the Merchant Shipping Act, No. 52 of 1971" [7]. On our reading, a lease of an unregistered vessel or aircraft is not within that wording.
Where. The exemption Order and the rent clause of the lease.
What you need. The monthly rent.
What goes wrong. Assuming every lease is exempt below some higher figure, or that the exemption covers vehicles and equipment. It is for buildings only. Item 9 is wider than property leases: it covers the lease or hire of "any property" [1]. But the same Order, as substituted by Gazette 2007/24 from 21 February 2017, exempts any finance lease of property other than one in respect of "any car or dual purpose motor vehicle of Class B" under section 122 of the Motor Traffic Act (item 15), and hire purchase agreements under the Consumer Credit Act for moveable property other than such vehicles (item 16) [4] [6]. On our reading, a finance lease of machinery or equipment is exempt, a finance lease of a car or a Class B dual purpose vehicle is not, and an ordinary rental of equipment that is not a finance lease falls under item 9 at Rs 20. The exemption Order dates from 2006 and has been amended since, including by Gazettes 1546/7 and 2007/24; check the IRD stamp duty page for any later amendment before relying on item 17 [5].
How long. Minutes.
Instrument: Stamp Duty (Special Provisions) Act, No. 12 of 2006, s.5; Order in Gazette Extraordinary No. 1465/20 of 5 October 2006, items 13, 15, 16 and 17, item 13 as substituted by Gazette 1546/7 and items 15 and 16 by Gazette 2007/24. Official link: Gazette 1465/20. Last verified: 21 Oct 2026.
Step 2. Calculate the aggregate rent for the whole term
What to do. Add up every rent payment for the whole term, including scheduled rent steps, and add any premium. If the term exceeds twenty years, the aggregate is deemed to be the rent for the first twenty years only [1]. A lease with rent of Rs 100,000 a month for the first year and Rs 110,000 for the second has an aggregate of Rs 2,520,000, not Rs 2,400,000.
Where. The lease itself.
What you need. The rent schedule, the term and any premium.
What goes wrong. Using only the first year's rent. Leaving out a premium or key money. Calculating a 25 year term in full when the cap applies. Where future rent depends on an index or a later valuation, the Gazette gives no rule for estimating it; on our reading, include every amount the lease fixes and take advice on the rest.
How long. Minutes once the figures are clear. For a long stepped lease, build the schedule in a spreadsheet year by year, total the first 240 months, and keep the sheet with the lease so the figure can be checked later.
Instrument: Gazette Extraordinary No. 2429/39 of 27 March 2025, item 09(a) and proviso. Official link: Gazette 2429/39. Last verified: 15 Oct 2026.
Step 3. Apply Rs 20 for every Rs 1,000 or part of Rs 1,000
What to do. Divide the aggregate by 1,000. Round any fraction up, because a part of Rs 1,000 is charged as a full Rs 1,000. Multiply by Rs 20 [1]. The result is close to 2 percent of the aggregate, and exactly 2 percent where the aggregate is a round thousand.
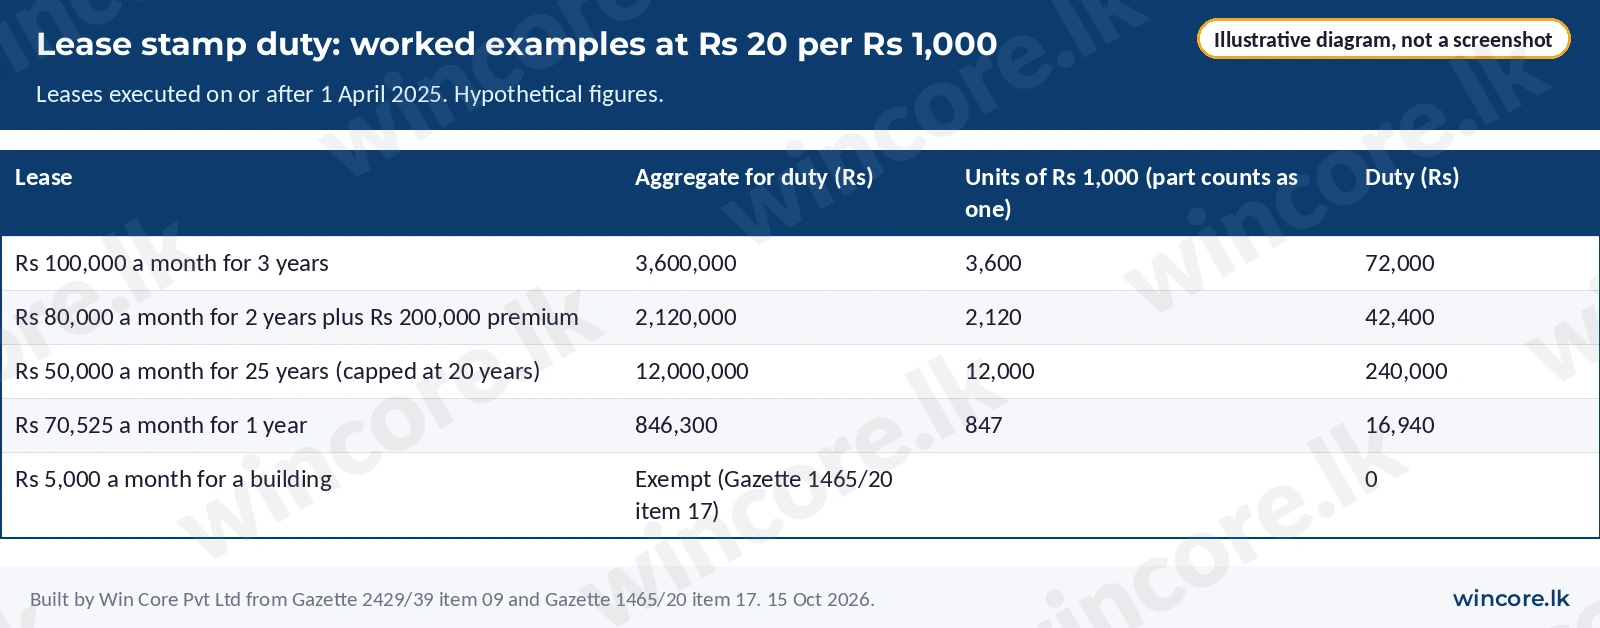
Example 1. Rs 100,000 a month for 36 months, no premium. Aggregate Rs 3,600,000. 3,600 units of Rs 1,000. Duty 3,600 x Rs 20 = Rs 72,000.
Example 2, with a premium. Rs 80,000 a month for 24 months plus a premium of Rs 200,000. Aggregate (80,000 x 24) + 200,000 = Rs 2,120,000. Duty 2,120 x Rs 20 = Rs 42,400.
Example 3, with the cap. Rs 50,000 a month for 25 years. Aggregate limited to the first 20 years: 50,000 x 240 = Rs 12,000,000. Duty 12,000 x Rs 20 = Rs 240,000.
Example 4, with rounding. Rs 70,525 a month for 12 months. Aggregate Rs 846,300, which is 846.3 units, rounded up to 847. Duty 847 x Rs 20 = Rs 16,940, not Rs 16,926.
Example 5, with a percentage escalation. Rs 380,000 a month for three years, rising 5 percent each year, no premium.
| Year | Monthly rent | Rent for the year |
|---|---|---|
| 1 | Rs 380,000 | Rs 4,560,000 |
| 2 | Rs 399,000 | Rs 4,788,000 |
| 3 | Rs 418,950 | Rs 5,027,400 |
| Total | Rs 14,375,400 |
The aggregate is 14,375.4 units, rounded up to 14,376. Duty 14,376 x Rs 20 = Rs 287,520. The same lease executed before 1 April 2025 would have paid Rs 143,760 at Rs 10, so the new rate adds Rs 143,760 to the cost of signing. An escalation clause is easy to miss when the duty is worked from the first year's rent. Our stamp duty calculator runs the same arithmetic.
Where. Your working paper.
What you need. The aggregate from Step 2.
What goes wrong. Rounding down on a part of Rs 1,000. Applying the old Rs 10 rate to a lease executed on or after 1 April 2025.
How long. Immediate.
Instrument: Gazette 2429/39, item 09(a). Official link: Gazette 2429/39. Last verified: 15 Oct 2026.
Step 4. Confirm who pays
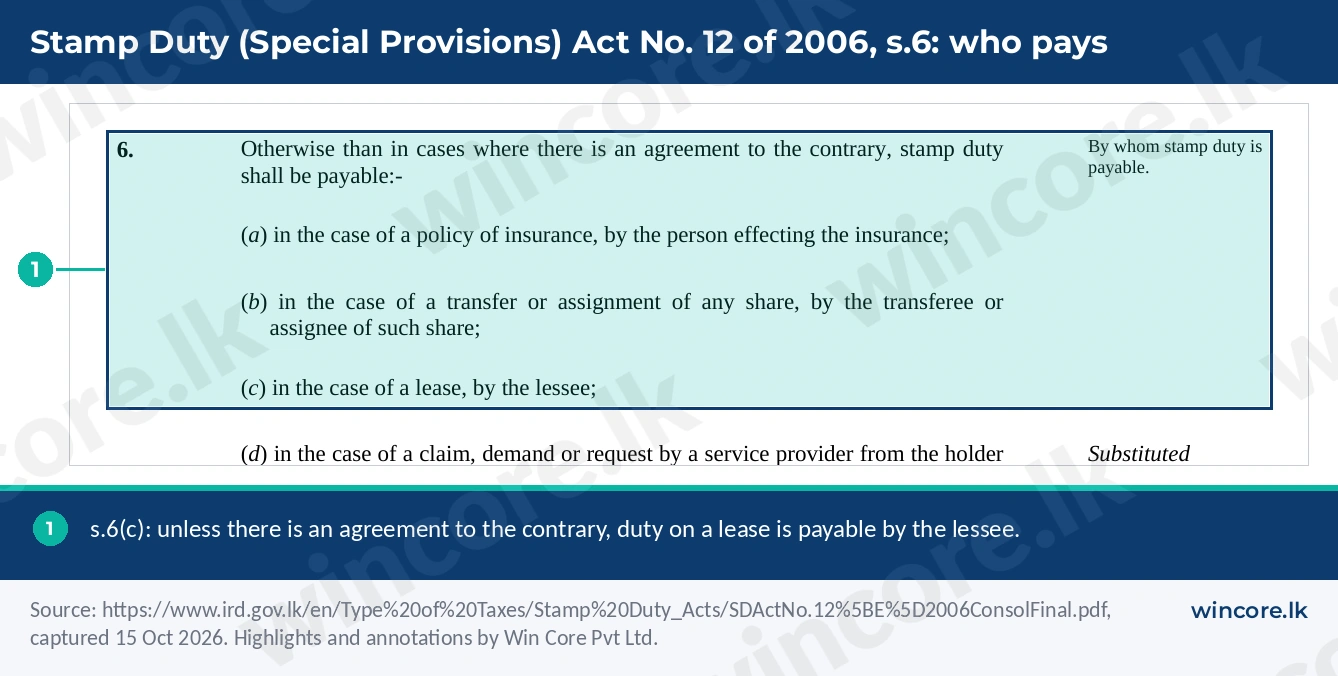
What to do. Section 6 says that, "otherwise than in cases where there is an agreement to the contrary", stamp duty "in the case of a lease" is payable "by the lessee" [2]. If the landlord has agreed to bear it, or the parties share it, say so in the lease.
Where. The stamp duty clause of the lease.
What you need. The agreed position.
What goes wrong. Assuming the landlord always pays, or leaving the point to be argued after signing. A tenant who has agreed to bear the duty should also agree who calculates it and who goes to the bank, so that the certificate is ready on the signing day.
How long. One clause in the draft.
Instrument: Stamp Duty (Special Provisions) Act, No. 12 of 2006, s.6(c). Official link: Act No. 12 of 2006, consolidated. Last verified: 15 Oct 2026.
Step 5. Pay before or at execution, in the right way
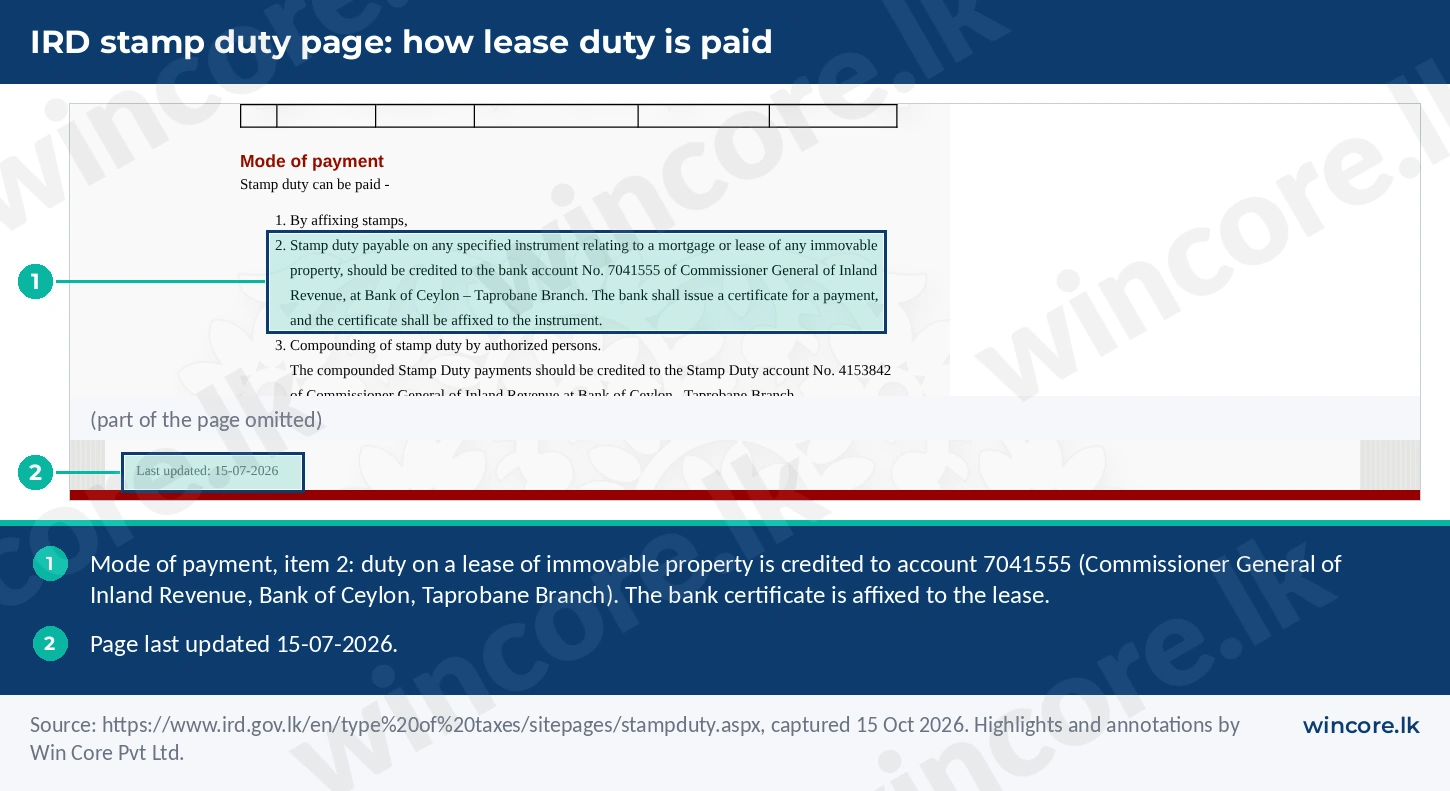
What to do. For a lease of immovable property, the duty may be paid to a prescribed bank prior to or at execution; if that is not possible for reasons beyond the payer's control, it must be paid within seven days of execution. The bank issues a certificate, which is affixed to the lease [2]. The Inland Revenue Department's stamp duty page says this duty "should be credited to the bank account No. 7041555 of Commissioner General of Inland Revenue, at Bank of Ceylon, Taprobane Branch" [5]. For other leases, affix adhesive stamps to the required value prior to or at execution, state the value of the duty on the face of the instrument, and cancel each stamp by writing your name or initials across it; a stamp of Rs 50 or more must also be perforated [2].
Where. Bank of Ceylon, Taprobane Branch, for immovable property; otherwise on the instrument itself.
What you need. The duty figure and the lease.
What goes wrong. Signing first and paying weeks later. Forgetting to affix the bank certificate. Overlooking a lease signed abroad: s.3(1)(b) charges an instrument "executed outside Sri Lanka being an instrument which relates to property situated in Sri Lanka, at the time such instrument was presented in Sri Lanka" [2], so plan the payment for the day the lease is presented here, not the day it was signed. Leaving adhesive stamps uncancelled: an uncancelled stamp is treated as if the instrument were unstamped to that extent [2].
How long. Same day.
Instrument: Stamp Duty (Special Provisions) Act, No. 12 of 2006, ss.3(1)(b) and 8(1) to (4); IRD stamp duty page. Official link: IRD stamp duty page. Last verified: 21 Oct 2026.
Step 6. Deal with under-stamping and later variations
What to do. If an Assessor considers that an instrument has not been duly stamped, the Assessor assesses the duty payable by the person liable and sends a notice requiring payment within the time stated [2]. The Inland Revenue Act's provisions on assessment, appeals and recovery apply to stamp duty [2]. If a lease is later varied to raise the rent or extend the term, check whether the variation is itself an instrument relating to a lease; on our reading, a deed that extends the term or increases the rent should be stamped on the additional aggregate it creates.
Where. The variation deed or side letter.
What you need. The original aggregate and the new figures.
What goes wrong. Assuming the original stamp covers every later change.
How long. A short review when the variation is drafted.
Instrument: Stamp Duty (Special Provisions) Act, No. 12 of 2006, ss.10 and 11. Official link: Act No. 12 of 2006, consolidated. Last verified: 15 Oct 2026.
Frequently asked questions
Is the effective date 1 March or 1 April 2025?
1 April 2025. The Order is dated 27 March 2025 and amends the Schedule "with effect from April 01, 2025" [1]. Section 3(3) of the Act lets a rate Order take effect on publication "or on such later date as may be specified therein", and requires it to be placed before Parliament for approval within three months. Under s.3(4), an Order Parliament disapproves is rescinded from the date of disapproval, "without prejudice to anything previously done thereunder" [2].
Does the twenty year cap apply to every lease?
It applies where the term exceeds twenty years; the aggregate is then the rent for the first twenty years [1].
Who pays if the lease is silent?
The lessee [2].
Does the rate apply to hire purchase agreements?
No. Hire purchase agreements under the Consumer Credit Act, No. 29 of 1982 stay at Rs 10 per Rs 1,000 [1].
Is a lease at Rs 5,000 a month stamped?
Not if it is a building: item 17 of the exemption Order covers building rent that does not exceed Rs 5,000 a month [4].
What about a lease signed before 1 April 2025?
The Order changes the Schedule from 1 April 2025. Because duty is paid prior to or at execution [2], on our reading a lease executed before that date carried the Rs 10 rate and does not need restamping; a new lease or a renewal executed on or after 1 April 2025 carries Rs 20.
Talk to us. If you are about to sign a lease and want the duty calculated and paid correctly, our tax team will run the numbers against the Gazette with you; book a consultation at our contact page. For keeping lease records in order, see our note on bookkeeping practices for small businesses.
WinCore Pvt Ltd
This guide is general information on the law as at 15 October 2026 and is not advice on your specific situation.
References
- Minister of Finance, Planning and Economic Development. Order under Section 3 of the Stamp Duty (Special Provisions) Act, No. 12 of 2006, Gazette Extraordinary No. 2429/39 (27 March 2025), item 09. https://www.ird.gov.lk/en/publications/Gazette_Documents/2025_2429-39_E.pdf . Primary. Accessed 15 October 2026.
- Parliament of Sri Lanka. Stamp Duty (Special Provisions) Act, No. 12 of 2006, consolidated, ss.3, 5, 6, 8, 10 and 11. https://www.ird.gov.lk/en/Type%20of%20Taxes/Stamp%20Duty_Acts/SDActNo.12%5BE%5D2006ConsolFinal.pdf . Primary. Accessed 15 October 2026 (s.3 on 21 October 2026).
- Government of Sri Lanka. Order under Section 3 of the Stamp Duty (Special Provisions) Act, Gazette Extraordinary No. 1465/19 (5 October 2006), item 09 (former Rs 10 rate). https://www.ird.gov.lk/en/publications/Gazette_Documents/2006_1465-19_E.pdf . Primary. Accessed 15 October 2026.
- Government of Sri Lanka. Order under Section 5 of the Stamp Duty (Special Provisions) Act, Gazette Extraordinary No. 1465/20 (5 October 2006), items 15, 16 and 17. https://www.ird.gov.lk/en/publications/Gazette_Documents/2006_1465-20_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Stamp Duty, mode of payment (page last updated 15 July 2026). https://www.ird.gov.lk/en/type%20of%20taxes/sitepages/stampduty.aspx . Primary. Accessed 15 October 2026.
- Government of Sri Lanka. Order under Section 5 of the Stamp Duty (Special Provisions) Act, Gazette Extraordinary No. 2007/24 (21 February 2017), items 15 and 16 substituted. https://www.ird.gov.lk/en/publications/Gazette_Documents/2017_2007_24_E.pdf . Primary. Accessed 21 October 2026.
- Government of Sri Lanka. Order under Section 5 of the Stamp Duty (Special Provisions) Act, Gazette Extraordinary No. 1546/7 (22 April 2008), item 13 substituted. https://www.ird.gov.lk/en/publications/Gazette_Documents/20081546_7%28E%29.pdf . Primary. Accessed 21 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
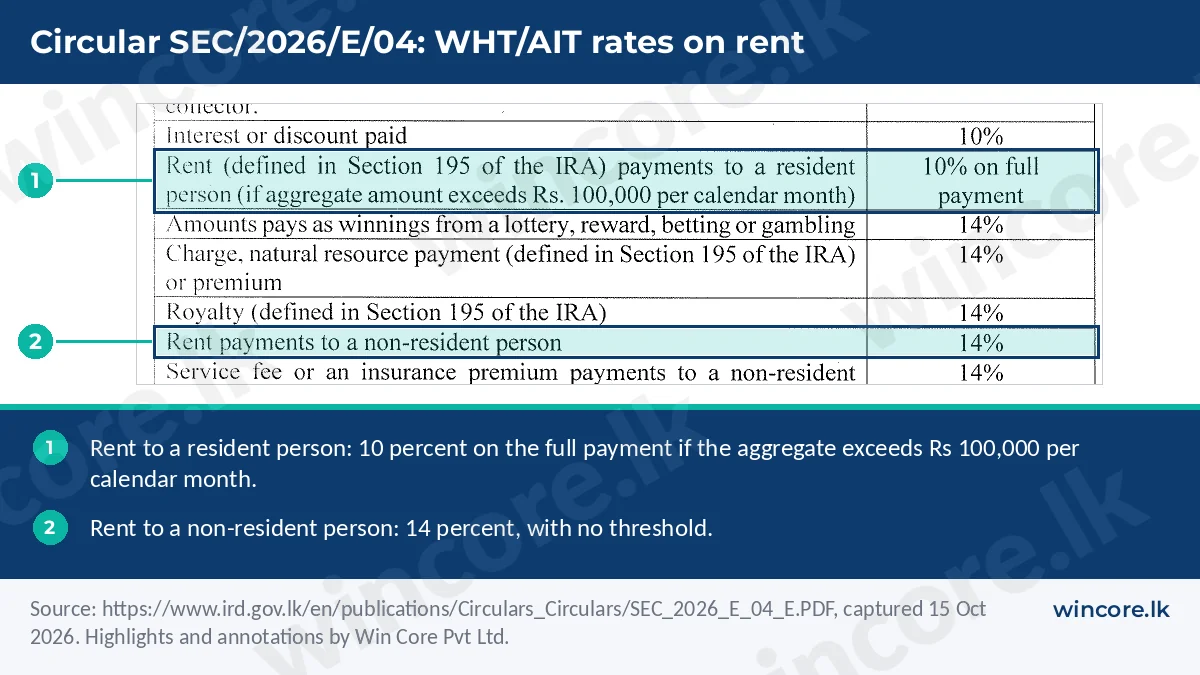
When a tenant must deduct 10 percent AIT from rent, the base excluding VAT, payment within 15 days, certificates and worked examples.
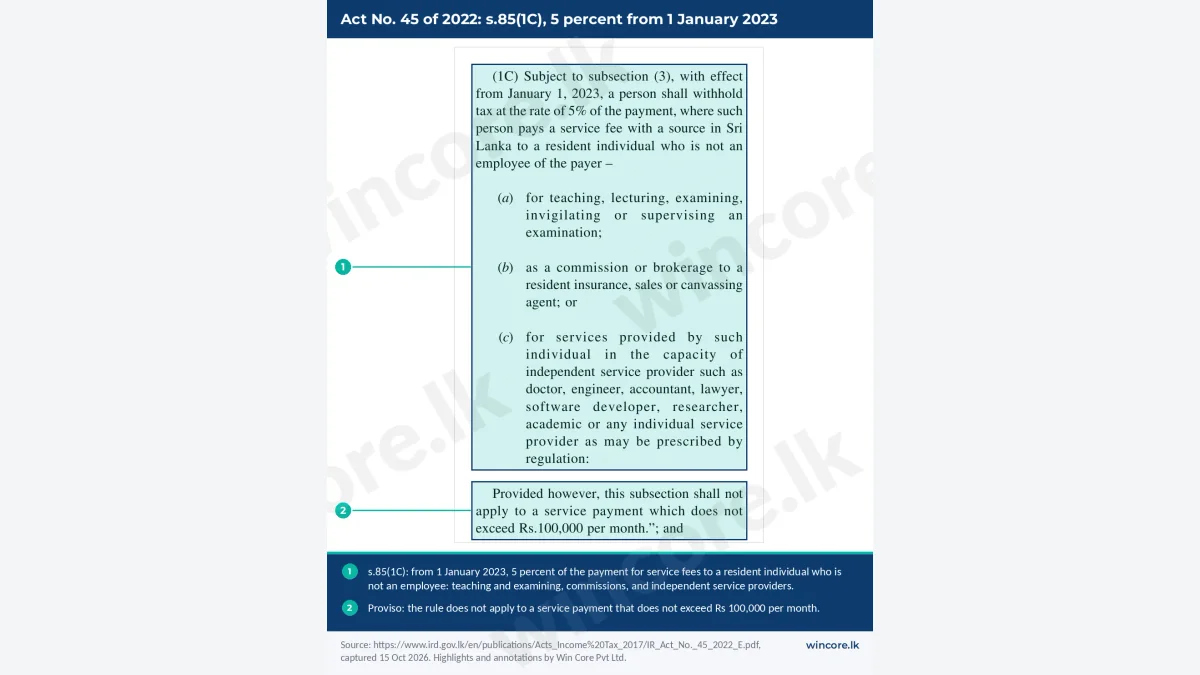
When a payer must withhold 5 percent on service fees, the services added in June 2026, payment within 15 days and the certificate rules.
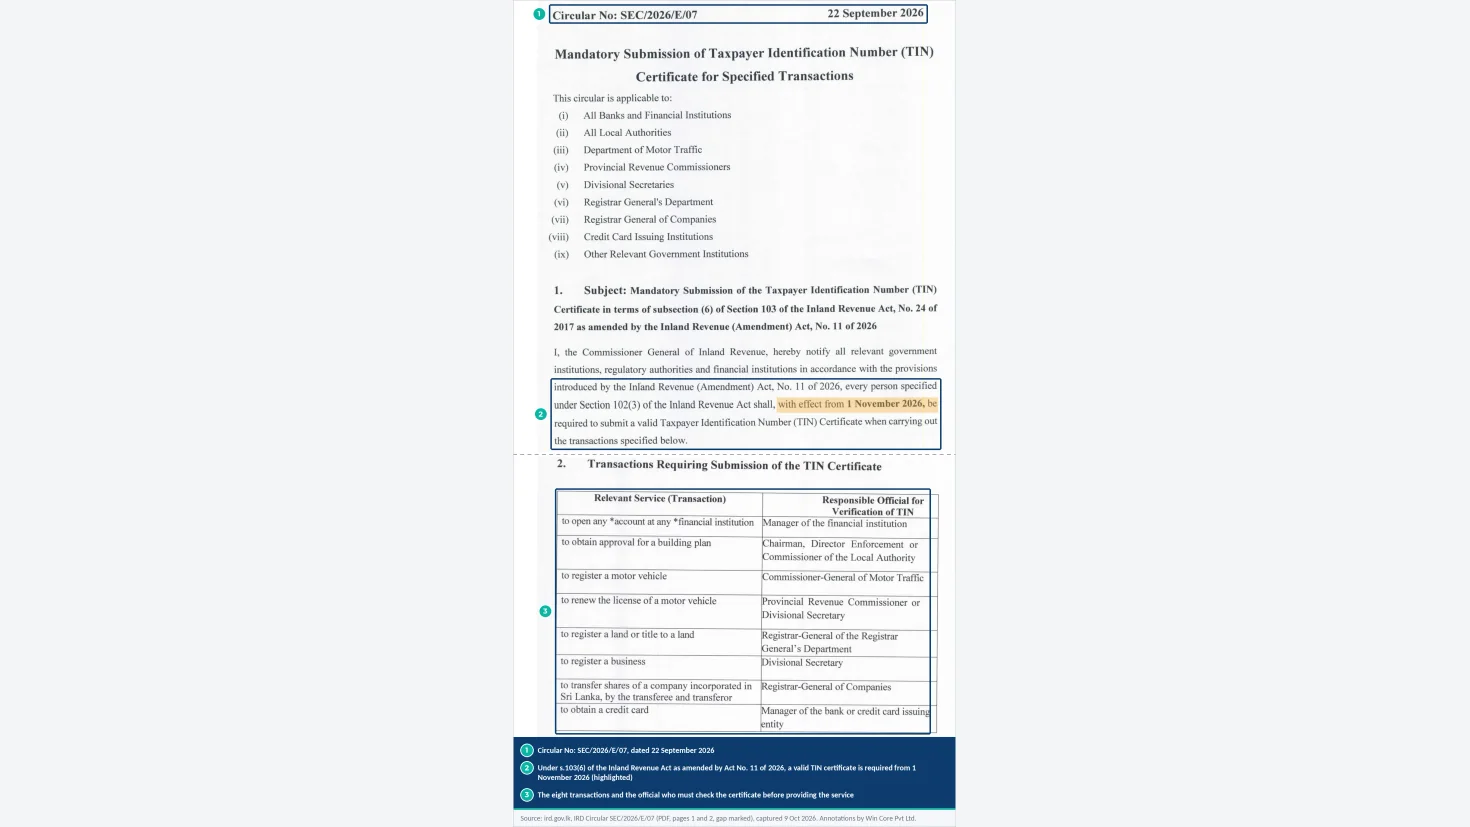
From 1 November 2026 individuals need a TIN certificate for eight transactions. Who needs one, how to get it, and TINs for companies and staff.