
IRD tax chart 2025/26 Sri Lanka: rates checked and what changed
The IRD's 2025/26 chart is a dated record. Which rows match the Act, which were overtaken, and the levy that changed inside the year.
On this page
Last verified against the primary sources on 21 October 2026.
The IRD tax chart 2025/26 for Sri Lanka, last updated 28 August 2025, gives the rates for the year of assessment 1 April 2025 to 31 March 2026: personal relief of Rs 1,800,000, individual bands of 6, 18, 24, 30 and 36 percent, company tax at 30 percent, VAT at 18 percent and SSCL at 2.5 percent [1]. Its income tax rows match the Act for 2025/26. One row was overtaken inside the year: the levy on betting and gaming gross collection rose from 15 to 18 percent for years from 1 January 2026, under Act No. 25 of 2025 [6]. Other rows moved from June and July 2026.
With the 2025/26 return due on 30 November 2026, the chart is the page most people open. Think of it as a photograph: sharp for the day it was taken, silent on what moved after.
Take a hypothetical resident freelance consultant in Kandy finishing a 2025/26 return, with taxable income of Rs 3,000,000 after relief. Which bands apply, and is anything on the chart already out of date for that return? We work it through below.
The IRD tax chart 2025/26 is a record of one year, dated 28 August 2025
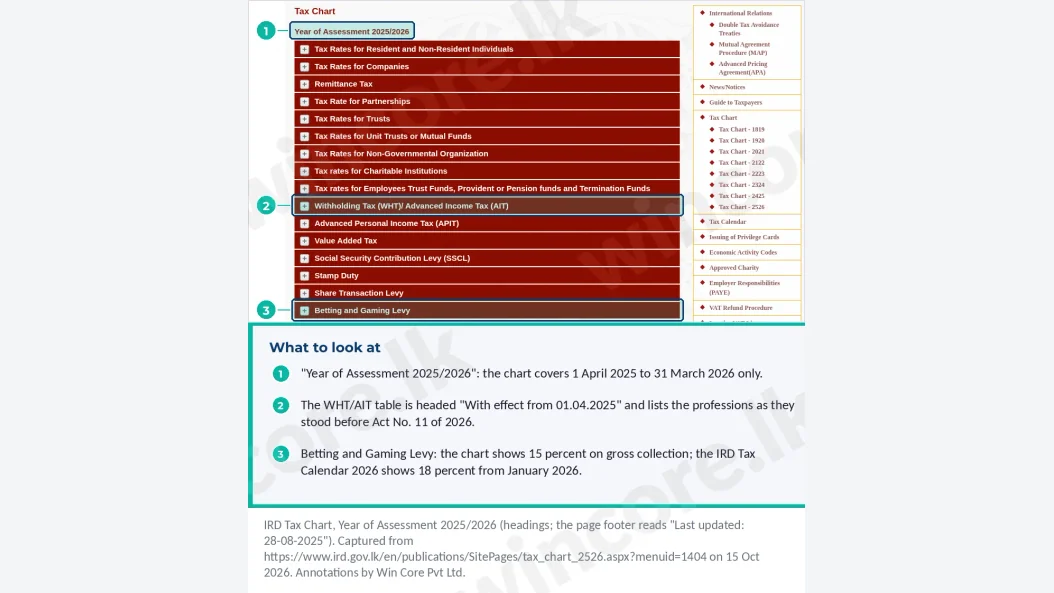
The Tax Chart is an IRD web page headed "Year of Assessment 2025/2026", with sections from individual rates to the Betting and Gaming Levy. Its footer reads "Last updated" 28-08-2025 [1]. It cites some sections and gazettes but is a summary, not law: the rates come from the Inland Revenue Act and the other taxing Acts.
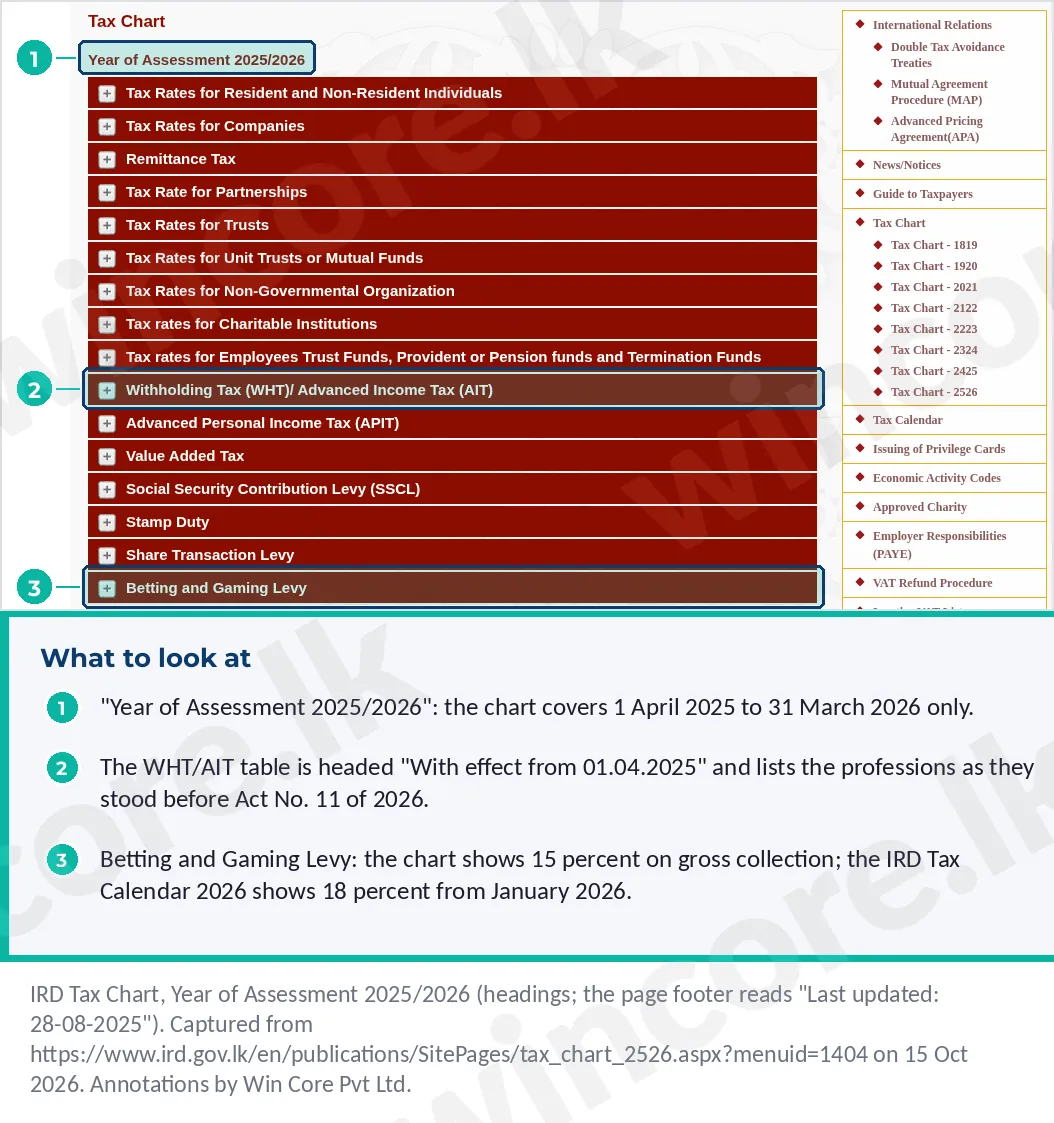
The year of assessment 2025/26 ran from 1 April 2025 to 31 March 2026 [2]. VAT, SSCL and the betting levy are charged by taxable period, not by year of assessment, which is why a change on 1 January 2026 can fall inside a chart that calls itself 2025/26.
The income tax rows match the Act for 2025/26
Individuals. First Rs 1,000,000 at 6 percent, next Rs 500,000 at 18 percent, next Rs 500,000 at 24 percent, next Rs 500,000 at 30 percent, and the balance at 36 percent. Gains from realising investment assets: 10 percent on the 2025/26 chart (15 percent from 3 June 2026; see below). Personal relief for residents and non-resident citizens: "Rs. 1,800,000/-", "not available for gains from the realization of investment asset" [1]. These are the bands Act No. 2 of 2025 set from 1 April 2025, which our post on Sri Lanka income tax bands for 2026 sets out with examples.
Companies. Standard rate 30 percent; 15 percent on services used outside Sri Lanka paid in foreign currency and remitted through a bank, and on such foreign-source gains; 45 percent on betting and gaming, liquor and tobacco; 30 percent on investment asset gains [1]. These match the Act's corporate rates: there has been no SME rate since 2023, and company gains have been taxed at 30 percent since 1 October 2022 [2].
Others, reported from the chart. Partnerships: 0 percent on the first Rs 1,000,000 and 6 percent on the balance, 10 percent on investment asset gains on the chart (15 percent from 3 June 2026). Trusts and NGOs: 30 percent. Charitable institutions and employee funds: 14 percent. Remittance tax on a non-resident: 14 percent, or 0 percent on retained income reinvested on the stated conditions [1]. We did not trace these rows to the Schedule today.
Terminal benefits. The chart shows a concessionary scale of 0 percent on the first Rs 10,000,000, 6 percent on the next Rs 10,000,000 and 12 percent on the balance [1]. Payroll deducts on terminal pay through APIT Table 03, which works differently; our piece on APIT on gratuity and termination pay sets out that open difference.
The WHT, VAT and SSCL rows were right for 2025/26 but have since moved
The WHT and AIT table is headed "With effect from 01.04.2025": 5 percent "on full payment" of service fees to a resident individual where the month's total exceeds Rs 100,000, 10 percent on interest and on resident rent above Rs 100,000, 14 percent on most other payments, 15 percent on dividends [1]. These match Circular SEC/2026/E/04 [5], except for the list of professions, which the chart still shows as it stood before June 2026.
VAT: 18 percent "From 01.01.2024"; financial services 18 percent "With effect from 01.01.2022"; registration where supplies exceed Rs 15 million for a one or three month period, or Rs 60 million in twelve months. SSCL: 2.5 percent, registration above Rs 15 million for any quarter from 1 January 2024. Share Transaction Levy 0.3 percent [1].
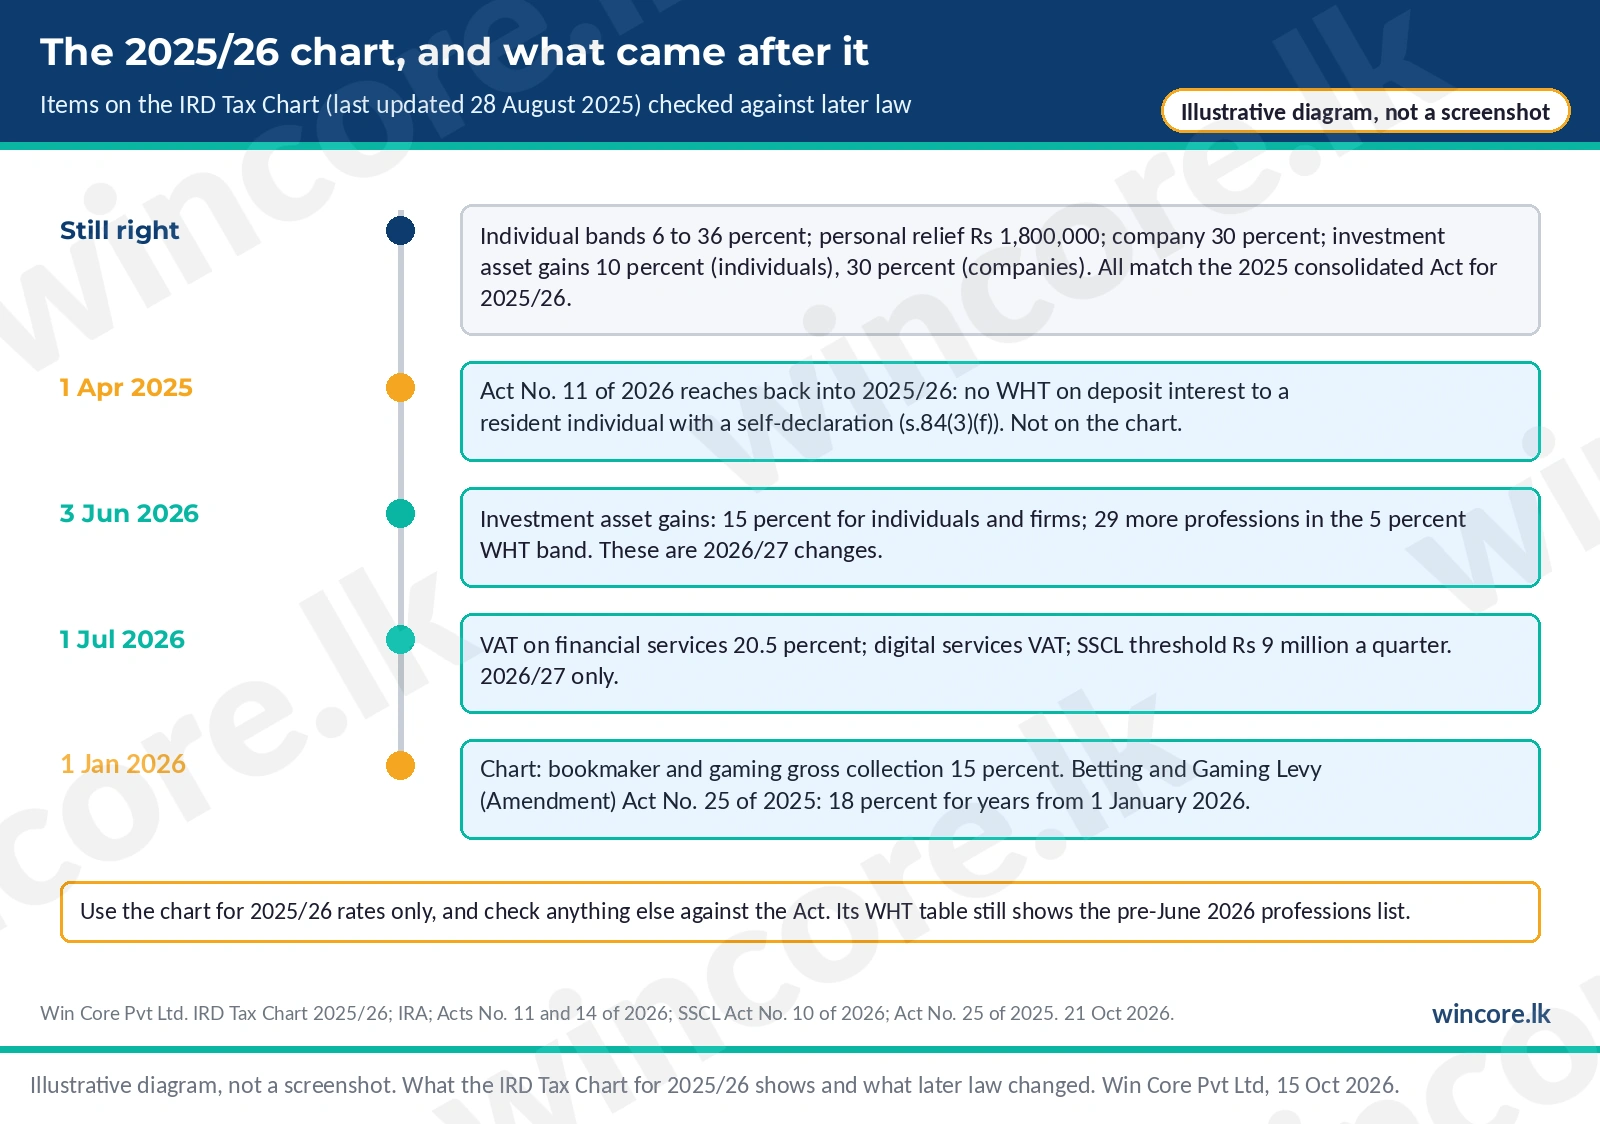
From 3 June 2026, the Inland Revenue (Amendment) Act No. 11 of 2026 came into operation. Investment asset gains for individuals and partnerships move to 15 percent [4], and 29 more professions join the 5 percent WHT band [3]; our guide to capital gains tax in Sri Lanka covers the gains side. From 1 July 2026, VAT on financial services is 20.5 percent and digital services supplied by non-residents are taxed, under the VAT (Amendment) Act No. 14 of 2026 [7], while the VAT registration threshold stays at Rs 15 million a quarter or Rs 60 million a year. The SSCL registration threshold drops to Rs 9 million a quarter or Rs 36 million over four consecutive quarters, under the SSCL (Amendment) Act No. 10 of 2026 [8]. None of these belongs in a 2025/26 computation, and none is on the chart.
The betting and gaming levy changed inside the year, on 1 January 2026
The chart's Betting and Gaming Levy section shows 15 percent on "the gross collection on the business of book marker or Business of gaming (after deducting winning prize)", where gross collection exceeds one million rupees a month [1]. The Betting and Gaming Levy (Amendment) Act, No. 25 of 2025, certified on 17 December 2025, limits the 15 percent rate to earlier years and adds a new rate "for any year commencing on or after January 1, 2026, at the rate of eighteen per centum" [6]. The IRD's Tax Calendar 2026, as we read it on 15 October 2026, shows the same 18 percent from January 2026. So for January to March 2026, inside the chart's own year, the 15 percent row is out of date. Some Secondary sources give 1 October 2025; the Act says 1 January 2026.
Two smaller faults sit in the service-fee row. It lists "teaching , lecturing, invigilating or supervising an examination", but section 85(1C)(a) of the Act and the IRD's own circular also say "examining" [2] [5]. And it spells lawyer as "layer". An examiner paid more than Rs 100,000 in a month is inside the 5 percent rule; see our guide to 5 percent WHT on service fees.
One change reaches back into 2025/26 without touching a rate. Act No. 11 of 2026 inserted section 84(3)(f): no WHT on deposit interest paid by a financial institution to a resident individual who provides a self-declaration, "for any year of assessment commencing on or after April 1, 2025" [3]. Our piece on the withholding tax circular 2026 covers the withholding changes that followed.
Worked example: Rs 3,000,000 of taxable income for 2025/26
Back to the Kandy consultant, with Rs 3,000,000 of 2025/26 taxable income after the Rs 1,800,000 relief:
| Band | Rate | Tax |
|---|---|---|
| First Rs 1,000,000 | 6% | Rs 60,000 |
| Next Rs 500,000 | 18% | Rs 90,000 |
| Next Rs 500,000 | 24% | Rs 120,000 |
| Next Rs 500,000 | 30% | Rs 150,000 |
| Balance Rs 500,000 | 36% | Rs 180,000 |
| Total | Rs 600,000 |
That is Rs 420,000 on the first Rs 2,500,000 plus 36 percent of the Rs 500,000 above it. WHT deducted by clients at 5 percent is credited against it, using the certificates they issued. If the consultant also had deposit interest and no taxable income, section 84(3)(f) would matter; here it does not. Nothing in this computation depends on a chart row that has changed.
Each default on a 2025/26 return has its own penalty section
| Default | Section | Consequence |
|---|---|---|
| 2025/26 return filed after 30 November 2026 | IRA s.178(1), (2) | Greater of 5 percent of tax owing plus 1 percent a month, or Rs 50,000 plus Rs 10,000 a month; capped at Rs 400,000 a return |
| Tax not paid within fourteen days of the due date, or by the due date in a notice of assessment if later | IRA s.179(1) | 20 percent of the tax due but not paid |
| Any tax paid late | IRA s.157, s.159(1) | Interest at 1.5 percent a month or part of a month |
| Underpayment from an incorrect return, through intent or negligence | IRA s.180 | 25 percent of the underpayment, or 75 percent where it exceeds Rs 10 million or 25 percent of the liability |
Our penalty calculator gives a first estimate for late filing and late payment.
What this means for you
For a 2025/26 return, the chart's income tax rows are right on every row we checked. For a betting or gaming business, the levy for January to March 2026 is 18 percent, not the chart's 15. For anything after March 2026, start from the Acts and our income tax return filing guide, not the chart. Our income tax services team prepares 2025/26 returns and checks each rate against the Act.
- Use the chart for 2025/26 income tax rates only.
- Apply 18 percent to betting and gaming gross collection from 1 January 2026.
- Check deposit interest for a section 84(3)(f) self-declaration.
- Do not carry the 10 percent gains rate to individual gains from 3 June 2026.
- File by 30 November 2026.
Checklist: documents needed
- Income and expense records for 1 April 2025 to 31 March 2026
- WHT and AIT certificates from every payer for the year
- T-10 certificates from employers, if you had employment income
- Bank statements showing deposit interest and any AIT deducted
- Records of any investment asset sold, with dates
- Last year's return and any notice from the IRD
Points we have not closed
- Unchecked rows. Partnership, trust, NGO, charity, fund, remittance and terminal benefit rates are reported from the chart only.
- Terminal benefits. The chart's 0 percent to Rs 10 million scale and APIT Table 03 do not line up; the difference is open.
- Reliance on the chart. We have not found any provision that makes reliance on an IRD chart row a defence, or any ruling on whether it counts as "negligence" under s.180.
Frequently asked questions
What are the income tax rates in Sri Lanka for 2025/26?
For individuals, 6 percent on the first Rs 1,000,000 of taxable income, then 18, 24 and 30 percent on successive Rs 500,000 bands, and 36 percent on the balance, after personal relief of Rs 1,800,000 [1]. Companies pay 30 percent as standard, 15 percent on qualifying foreign currency service income and 45 percent on betting, liquor and tobacco.
What is the personal relief for the 2025/26 year of assessment?
Rs 1,800,000 for residents and non-resident citizens, for each year of assessment from 1 April 2025 [1]. It is not available against gains from realising investment assets. In monthly terms it is the Rs 150,000 built into APIT Table 01, which is why employees under that amount suffer no APIT.
Is the investment asset gains rate 10 or 15 percent?
Ten percent for individuals and partnerships in 2025/26, as the chart shows [1]. From 3 June 2026, when Act No. 11 of 2026 came into operation, it is 15 percent for individuals and partnerships, and 30 percent for trusts and NGOs [4]. Companies stay at 30 percent, unchanged since 1 October 2022.
Is the betting and gaming levy 15 or 18 percent?
Eighteen percent for any year commencing on or after 1 January 2026, under the Betting and Gaming Levy (Amendment) Act No. 25 of 2025, certified on 17 December 2025 [6]. The IRD chart still shows 15 percent, so for January to March 2026 its levy row is out of date.
When is the 2025/26 income tax return due?
By 30 November 2026, the deadline for a year of assessment ending on 31 March 2026 [2]. Filing late attracts the s.178 penalty, the greater of 5 percent of the tax owing plus 1 percent a month or Rs 50,000 plus Rs 10,000 a month, capped at Rs 400,000 a return.
Talk to us. If you would like us to check your 2025/26 computation before 30 November 2026, book a consultation at our contact page.
WinCore Pvt Ltd
This article is general information on the law as at 21 October 2026 and is not advice on your specific position.
References
- Inland Revenue Department. Tax Chart, Year of Assessment 2025/2026 (last updated 28 August 2025). https://www.ird.gov.lk/en/publications/SitePages/tax_chart_2526.aspx?menuid=1404 . Primary. Accessed 21 October 2026.
- Inland Revenue Department. Inland Revenue Act, No. 24 of 2017, consolidated with amendments to 2025, ss.20(1), 85(1C), 157, 159, 178, 179 and 180; First Schedule. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act, No. 11 of 2026 (certified 3 June 2026), ss.1, 12 and 13. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 21 October 2026.
- Inland Revenue Department. Notice to the Taxpayers: Amendments to the Inland Revenue Act, No. 24 of 2017, SEC/PN/IT/2026/02 (8 June 2026), item 20. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/794/SEC_PN_IT_2026-02_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Circular to Withholding Agents, SEC/2026/E/04 (8 June 2026), para 1. https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2026_E_04_E.PDF . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Betting and Gaming Levy (Amendment) Act, No. 25 of 2025 (certified 17 December 2025), s.2. https://www.ird.gov.lk/en/publications/Acts_Betting%20and%20Gaming%20Levy/BNG_Act_No._25_2025_E.pdf . Primary. Accessed 21 October 2026.
- Parliament of Sri Lanka. Value Added Tax (Amendment) Act, No. 14 of 2026. https://www.ird.gov.lk/en/publications/Value%20Added%20Tax_Acts/VAT_Act_No_14-2026_E.PDF . Primary. Accessed 15 October 2026.
- Parliament of Sri Lanka. Social Security Contribution Levy (Amendment) Act, No. 10 of 2026. https://www.ird.gov.lk/en/publications/Acts_SSCL/SSCL_Act_No_10-2026_E.pdf . Primary. Accessed 15 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.

Sri Lanka income tax bands for 2026 explained with current rates, worked examples, and practical APIT planning for employees and employers.

Step-by-step guide to filing income tax returns in Sri Lanka: deadlines, RAMIS process, relief, bands, WHT credits, and common penalty traps.
Sri Lanka taxes gains on investment assets at a flat rate, separate from your other income: 15% for individuals from 3 June 2026 (10% before). Here is what is exempt and how to file the capital gains tax return.