
BOI incentives in Sri Lanka in 2026: why standard projects now get Enhanced Capital Allowances, and where tax holidays still apply
The BOI's 2026 investment guide gives standard projects Enhanced Capital Allowances. Tax holidays are reserved for Strategic Development Projects.

On this page
Last verified against the primary sources on 15 October 2026.
If you have read that a Board of Investment (BOI) project gets a corporate income tax holiday of three to twelve years, that information is out of date. The BOI's own Investment Guide 2026 gives standard BOI projects Enhanced Capital Allowances (ECA), and reserves tax holidays for projects under the Strategic Development Projects Act No. 14 of 2008 [1]. A standard project is taxed at the ordinary corporate rates, and the incentive comes through faster deductions for its capital spending.
Take a hypothetical new manufacturing undertaking that invests the equivalent of USD 1 million in plant and machinery. On the ordinary rules, plant and machinery is written off at 20 percent a year on a straight-line basis [2]. Because its depreciable assets are above USD 250,000 and not above USD 3 million, the undertaking falls within the 100 percent Enhanced Capital Allowance band that applies from 1 April 2026 [3]. The tax rate does not change; the timing of the deduction does.
This guide covers what the 2026 incentive framework gives standard projects, where tax holidays still apply, and the separate role the BOI plays in foreign ownership. It does not cover customs concessions or the BOI application procedure.
What standard BOI projects get in 2026: Enhanced Capital Allowances
What to know. The Investment Guide 2026, dated 25 June 2026, sets out Enhanced Capital Allowances as the incentive for standard projects [1]. The Inland Revenue (Amendment) Act No. 11 of 2026 gives a 100 percent allowance for a new undertaking whose depreciable assets exceed USD 250,000 but do not exceed USD 3 million, from 1 April 2026; an expansion of an existing undertaking needs specific BOI approval [3].
What it means. Profits are taxed at the normal corporate rates: 30 percent standard, 15 percent on specified concessionary income and 45 percent on liquor, tobacco, betting and similar activities [2]. The benefit is that the capital cost is deducted faster than the ordinary straight-line allowances of 20 percent a year for plant, machinery and equipment and 5 percent for buildings [2].
What goes wrong. Building a business plan around a tax holiday that a standard project will not get. Assuming an expansion qualifies automatically: it needs specific BOI approval.
Our guide to the Enhanced Capital Allowance covers the computation.
Instrument: Inland Revenue (Amendment) Act No. 11 of 2026, s.37 (new Second Schedule para 1(2A)); BOI Investment Guide 2026. Official link: Act No. 11 of 2026. Last verified: 15 Oct 2026.
Where tax holidays still apply: Strategic Development Projects
What to know. In the 2026 framework, tax holidays are reserved for projects approved under the Strategic Development Projects Act No. 14 of 2008 [1]. That is a separate statute from the BOI law, with its own approval route.
What it means. An ordinary manufacturing, services or export project should not expect a tax holiday. A project large or strategic enough to be considered under the Strategic Development Projects Act is a different conversation, and its terms are set through that Act's approval.
What goes wrong. Treating "BOI project" and "Strategic Development Project" as the same thing.
Instrument: BOI Investment Guide 2026 (25 June 2026). Official link: Investment Guide 2026. Last verified: 15 Oct 2026.
The BOI's other role: foreign ownership above 40 percent
What to know. A foreign-owned company in an activity outside the restricted lists in Gazette 2213/35 does not need BOI approval to take foreign shareholders; the permission comes from the Foreign Exchange Regulations themselves [4]. For the ten activities in paragraph 8(1), such as education, freight forwarding and travel agencies, foreign holdings are capped at 40 percent unless the BOI grants special approval for a higher percentage [4].
What it means. There are two separate reasons to deal with the BOI: incentives for the project, and a higher foreign shareholding in a capped activity. The BOI describes itself as administering the incentives granted under the BOI law [5].
What goes wrong. Assuming every foreign-owned company has to go through the BOI. Our guide to 100 percent foreign ownership sets out the three lists.
Instrument: Foreign Exchange Regulations No. 2 of 2021, Gazette 2213/35, Schedule Part I paras 7 and 8. Official link: Gazette 2213/35 on cbsl.gov.lk. Last verified: 15 Oct 2026.
Before you apply
The legal framework for investment approval has been under reform, and the BOI revises its criteria and thresholds. Read the current Investment Guide and confirm the position with the BOI for your sector before you build the incentive into a business plan. Then compare the Enhanced Capital Allowance with the ordinary capital allowances on your own capital budget: the larger and earlier the capital spending, the more the faster deduction is worth.
Frequently asked questions
Do BOI projects still get tax holidays?
Not standard projects. The BOI's 2026 guide gives them Enhanced Capital Allowances and reserves tax holidays for projects under the Strategic Development Projects Act No. 14 of 2008 [1].
What is the Enhanced Capital Allowance?
From 1 April 2026, a 100 percent capital allowance for a new undertaking whose depreciable assets exceed USD 250,000 but not USD 3 million; an expansion needs specific BOI approval [3].
Does a BOI company pay a lower tax rate?
A standard project pays the ordinary corporate rates, with the benefit coming through faster capital allowances [1] [2].
Do I need BOI approval to set up a foreign-owned company?
Not for an activity outside the restricted lists. BOI approval matters for incentives and for a foreign holding above 40 percent in a paragraph 8(1) activity [4].
Talk to us. If you are weighing BOI status for a new project, our tax page explains how we can help you compare the incentive with the ordinary tax rules, and our company registration page covers setting up the company; book a consultation at our contact page.
This guide is general information on the law as at 15 October 2026 and is not advice on your specific situation.
References
- Board of Investment of Sri Lanka. Investment Guide 2026 (25 June 2026), investment incentives. https://investsrilanka.com/wp-content/uploads/2026/07/Investment-Guide-2026-Changing-Pages-25.06.2026.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Inland Revenue Act, No. 24 of 2017, consolidated, First and Fourth Schedules. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary. Accessed 15 October 2026.
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act, No. 11 of 2026, certified 3 June 2026, s.37 (new Second Schedule para 1(2A)). https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 15 October 2026.
- Central Bank of Sri Lanka. Foreign Exchange (Classes of Capital Transactions Undertaken in Sri Lanka by a Person Resident Outside Sri Lanka) Regulations No. 2 of 2021, Gazette Extraordinary No. 2213/35 (3 February 2021), Schedule Part I, paras 1, 7 and 8. https://www.cbsl.gov.lk/sites/default/files/cbslweb_documents/laws/acts/en/dfe_gazette_20210203_2213_35_e.pdf . Primary. Accessed 15 October 2026.
- Board of Investment of Sri Lanka. Who we are, web page. https://investsrilanka.com/who-we-are/ . Primary. Accessed 15 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
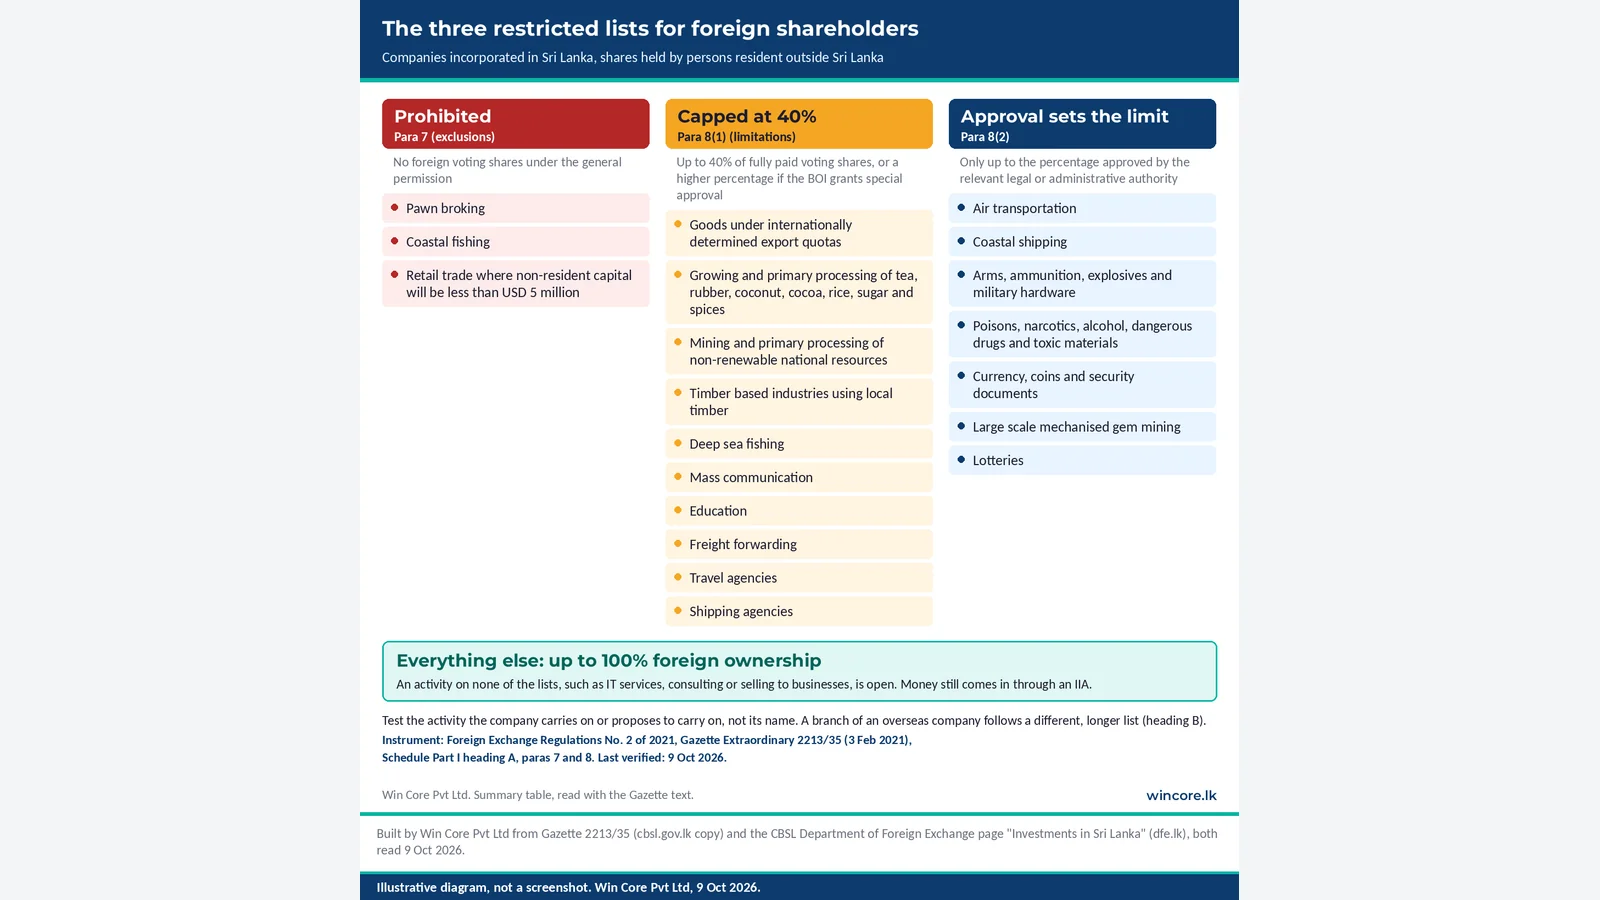
Most Sri Lankan companies can be 100 percent foreign owned. The three restricted lists in Gazette 2213/35, the retail test and the BOI route.
From 1 April 2026, Sri Lanka's Enhanced Capital Allowance also applies to new undertakings whose depreciable assets exceed USD 250,000 but not USD 3 million, opening a 100% allowance to mid-market investors.
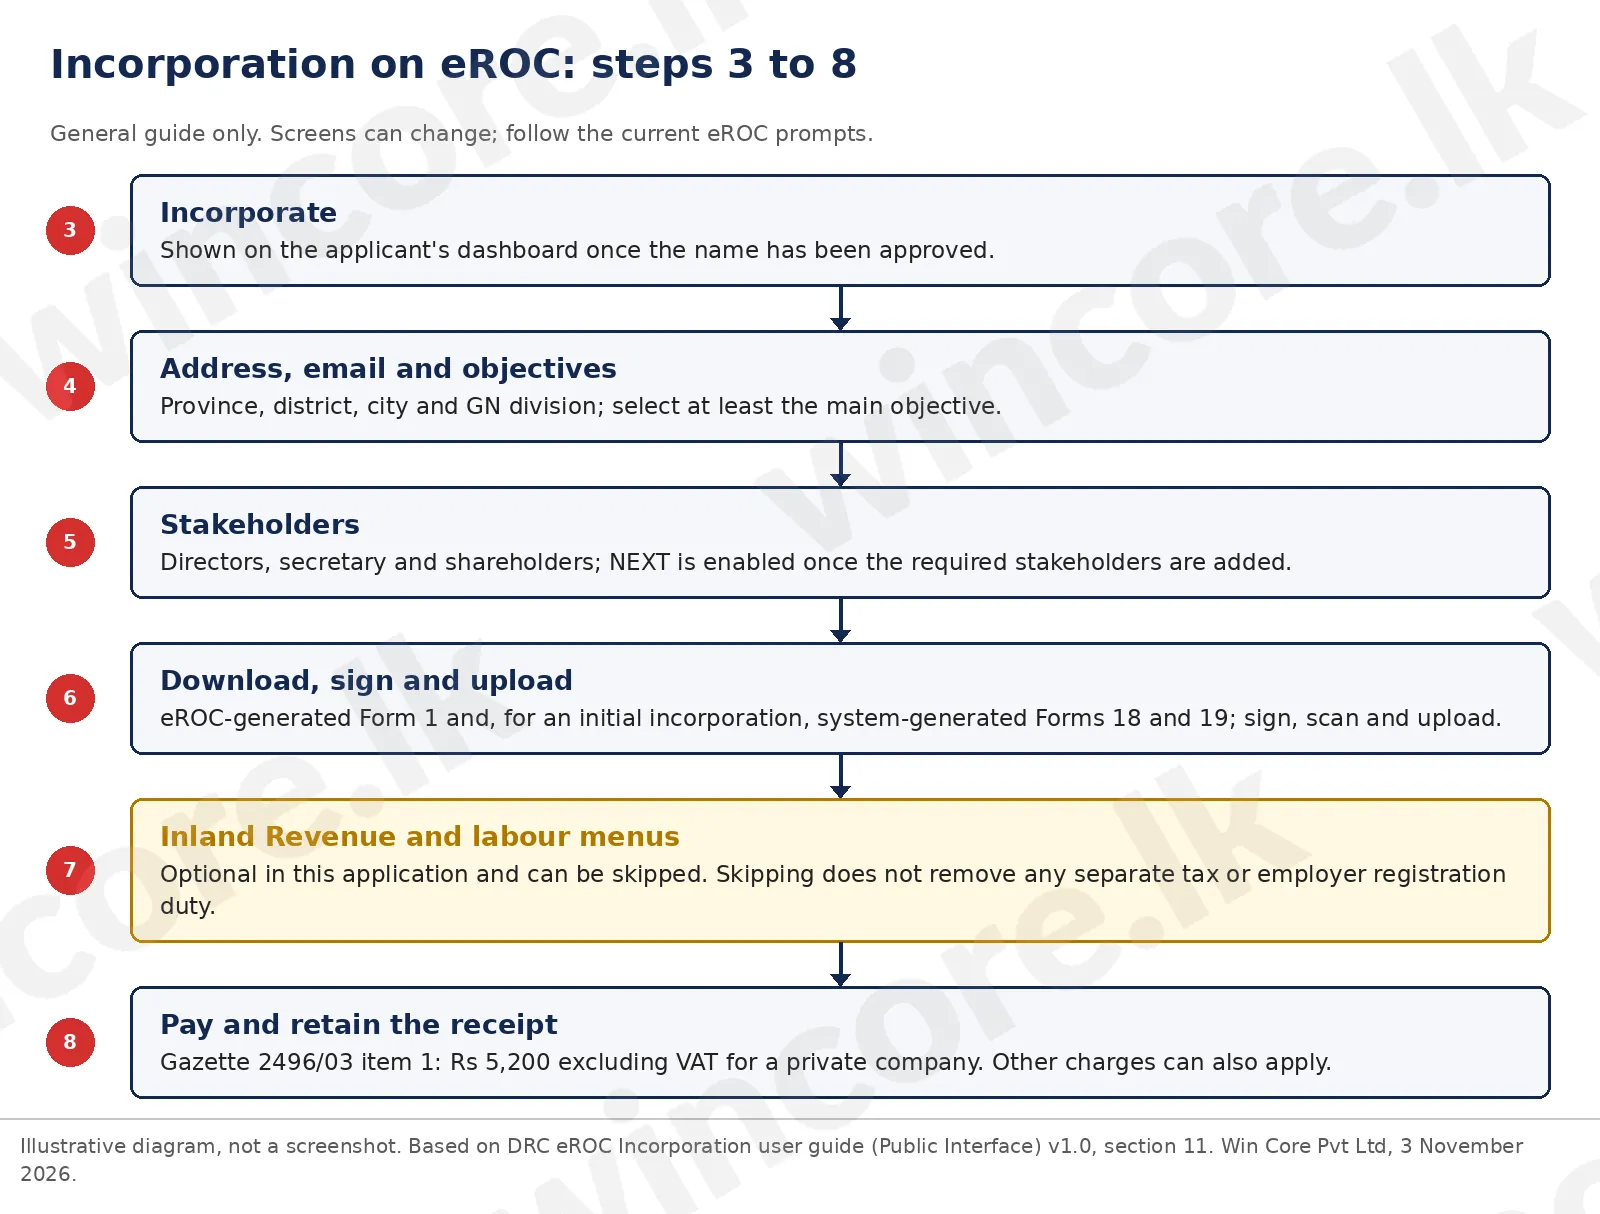
Registering a private limited company in Sri Lanka in 2026: structure, name approval, the eROC filing with BO 1 and BO 5, the TIN and the first year.