IRD interest write off Sri Lanka: who qualifies?
Find out which tax interest can be written off, what must be paid and how to check a disputed assessment before the deadline.
On this page
Last verified 13 November 2026.
Last updated 13 November 2026.
IRD interest write off Sri Lanka, in brief. Section 42 of the Inland Revenue (Amendment) Act No. 11 of 2026 covers qualifying outstanding interest on income tax, surcharge tax and debt repayment levy when the full tax and applicable unwaived penalties are paid. IRD notice SEC/PN/IT/2026/03 names 2 December 2026 as the final settlement date and applies its guidance through 2024/25. Pay before that date. [1] [2]
An invented building contractor has an additional assessment for 2022/23. Part of its tax payment was applied to interest, so its statement's tax balance needs a separate calculation before deciding what remains to pay. The example below shows why paying principal alone is not enough when an assessed penalty remains payable.
What changed
- 8 June 2026: The IRD published notice SEC/PN/IT/2026/03, setting out the conditions and the 2 December settlement date. [2]
| Date | Event | Why it matters |
|---|---|---|
| 3 June 2026 | Act No. 11 of 2026 certified; section 42 took effect | The six-month period runs from the Act's operation date. [1] |
| 8 June 2026 | IRD notices 02 and 03 issued | Notice 03 sets out the process and covered assessments. [2] [5] |
| 30 November 2026 | 2025/26 income tax return due where required | This is a separate filing obligation; 2025/26 is outside the notice's write-off years. [3] |
| 2 December 2026 | IRD's final settlement date | Pay the full tax and any penalty still payable in time. [2] |
| From 3 December 2026 | The stated window has passed | A taxpayer who did not meet its conditions cannot rely on the stated window without a later change. [1] [2] |
Key dates: section 42 effective 3 June 2026; IRD notice dated 8 June 2026 and IRD tax calendar.
Key facts: The relief is for outstanding interest, not tax or penalties. The IRD notice covers income tax and the other listed taxes up to 2024/25. For each relevant year or period, the full principal and applicable penalty not waived must be paid within the window. Section 42 and IRD notice 03 supply the rule and the operational conditions. [1] [2]
Which interest does the IRD interest write off in Sri Lanka cover?
Section 42 covers qualifying interest on underpayments and late payments which remains outstanding. For section 157 interest under the Inland Revenue Act, the Act specifies the year of assessment ending 31 March 2025 as the upper limit. It also names surcharge tax and debt repayment levy. The IRD notice applies its guidance up to and including 2024/25. [1] [2]
The notice lists income tax, including withholding tax such as APIT, PAYE and AIT, capital gains tax, remittance tax and NGO tax; surcharge tax; and debt repayment levy. It refers to an assessment including a self-assessment, default, advance, amended or additional assessment. Check the particular tax and period on the statement instead of assuming that every balance qualifies. [2]
Interest on 2025/26 and later income tax does not fall within the specified section 157 years. Each year of assessment or taxable period is considered separately under section 42(3)(b). Meeting the condition for one year does not automatically settle the condition for another. [1]
What must be paid by 2 December 2026?
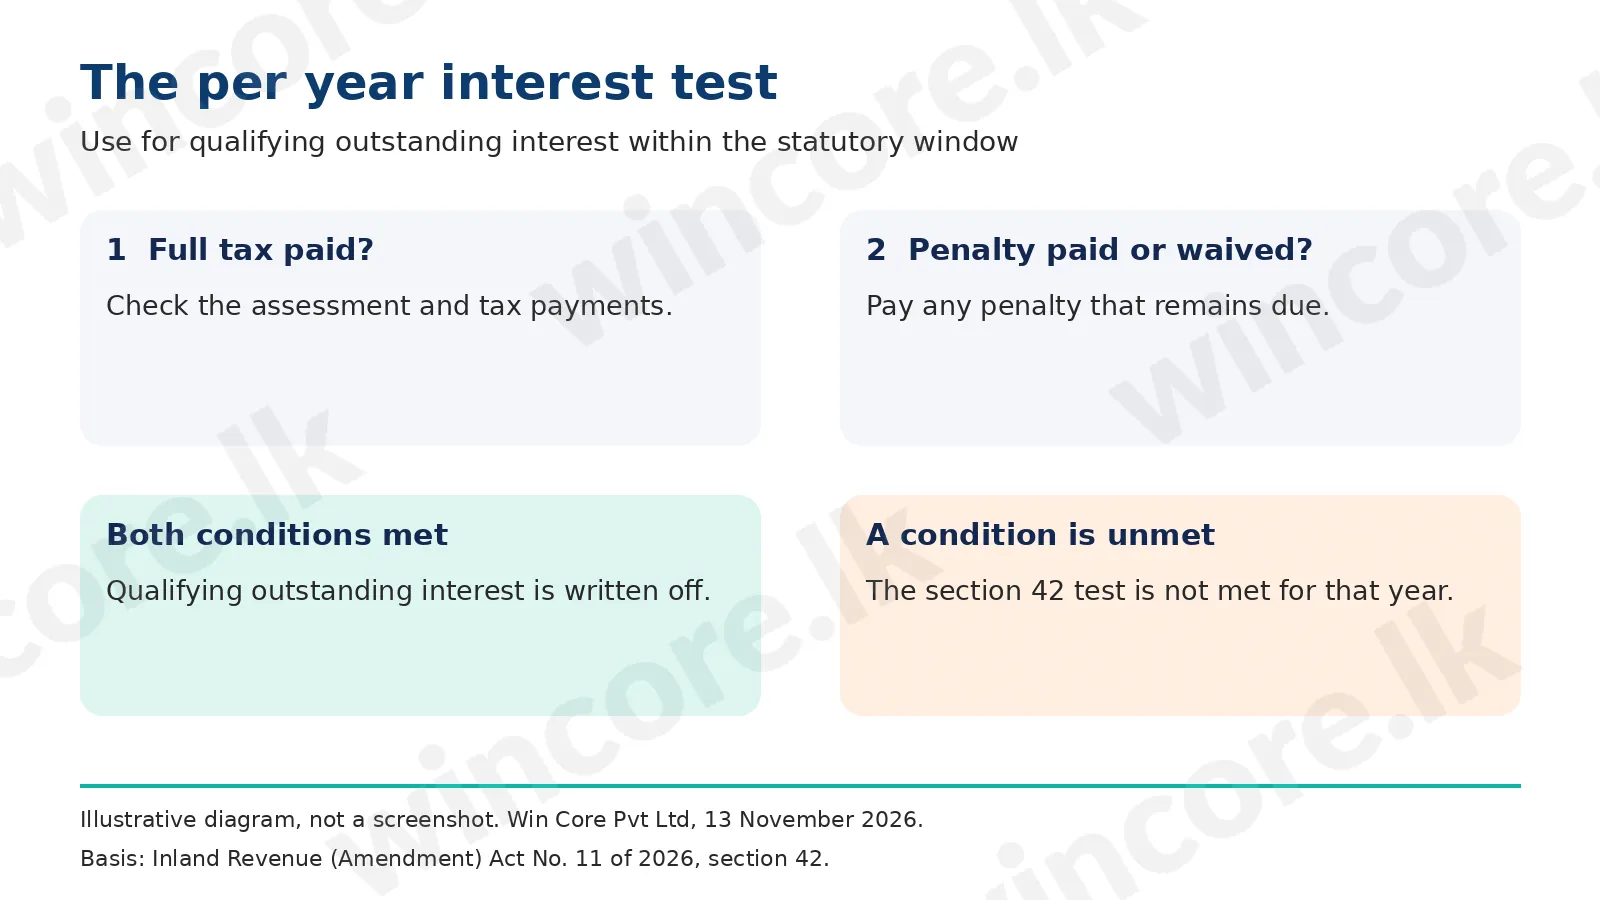
The full principal tax for the relevant assessment and applicable penalties, other than any amount waived by the Commissioner-General, must be paid within the statutory period. Section 42(2) sets the condition; notice 03 names 2 December 2026 as the final settlement date and says any balance penalty payable must be settled on or before that date. Arrange payment before 2 December and check that it is credited to the correct tax and period. [1] [2]
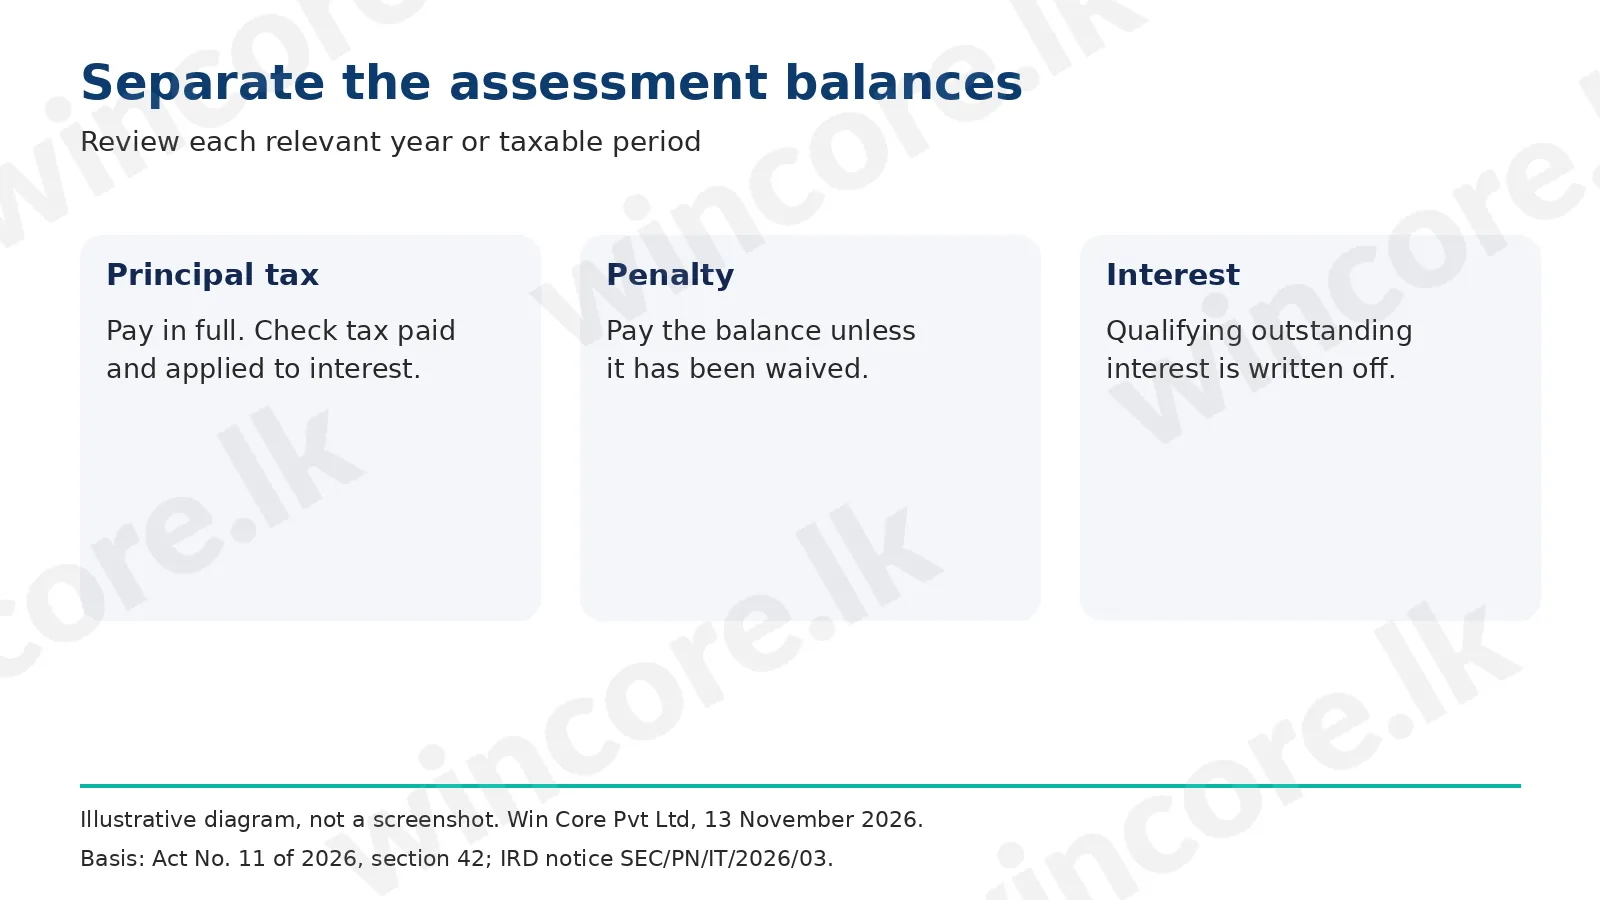
Start with the assessment and a detailed statement for each year. Separate principal, penalty and interest. Under section 154, a payment of a specific tax is applied first to related interest, then penalties, and then principal. [4] Check whether a tax payment has been allocated to interest: section 42(3)(c) treats that amount as principal solely for the section 42 test. The IRD notice says such an amount is transferred and credited to the outstanding principal. Ask the IRD unit handling the file to reconcile any difference before settling the balance. [1] [2]
If the full tax and applicable unwaived penalties were already paid before 3 June 2026, section 42(3)(a) treats the condition as met. The notice says interest paid as interest before 3 June 2026 is not refunded. A write-off of outstanding interest is therefore different from a refund of interest already paid. [1] [2]
Are penalties written off too?
No. Section 42 writes off qualifying interest, not the tax or the penalty. The IRD says a penalty may be waived in whole or part for reasonable cause after a taxpayer's request. A waiver is a separate decision and should not be assumed merely because interest relief is available. [1] [2]
After paying the full tax, send a written request with reasons to the Commissioner of the relevant unit or regional office, as the notice directs. Send it promptly and pay any balance penalty that remains payable by 2 December. The notice does not specify whether the waiver decision must be issued before that date; check the position with the IRD unit handling the file. [2]
Keep the request and evidence of payment together with the assessment and statement. Under section 176(9), the Commissioner-General may refrain from assessing, remit or waive a penalty in whole or part where reasonable cause is shown. That power is distinct from the interest write-off. [4] The RAMIS penalties guide explains the broader distinction between penalty and interest. Do not describe this relief as a tax amnesty or penalty amnesty.
Does the write-off cover VAT or SSCL?
No. Section 42 lists section 157 interest under the Inland Revenue Act, surcharge tax and debt repayment levy; it does not list VAT or SSCL interest. A separate VAT or SSCL balance therefore needs its own review and should not be subtracted from the payment needed for this relief. [1]
The guide to Act No. 11 of 2026 covers the wider amendments. This page deals with the section 42 interest test. The IRD's notice applies its stated 2024/25 limit to the covered assessments, while the wording in section 42(1) explicitly attaches the year limit to its Inland Revenue Act limb. Confirm any uncertain surcharge tax or levy period with the relevant IRD unit. [1] [2]
How does the calculation work for one assessment?
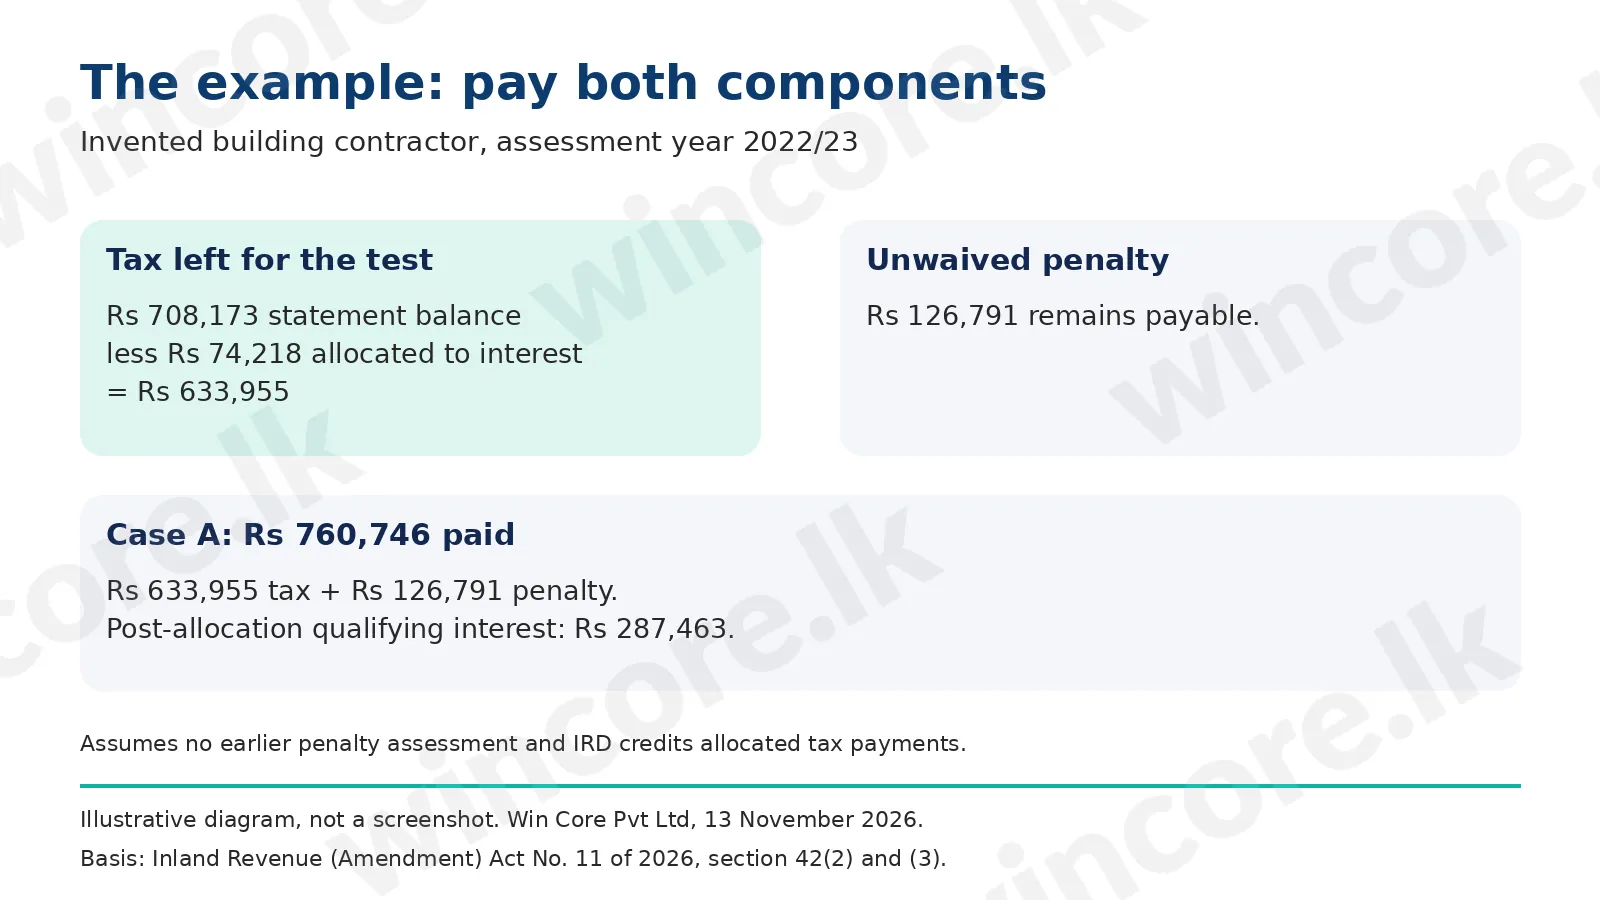
The invented contractor's additional assessment for 2022/23 is Rs 1,846,370. For this calculation, assume the penalty had not yet been assessed when the earlier tax payment was allocated, and that any later tax payment allocated to interest is credited back to principal under the notice. The stated remaining interest is measured after the required reallocation. On our reading, the calculation works as follows. Of Rs 1,212,415 paid towards tax, the IRD applied Rs 74,218 to interest. The statement therefore shows Rs 1,138,197 as tax paid and Rs 708,173 as tax outstanding. For section 42 only, the Rs 74,218 counts as principal: Rs 708,173 less Rs 74,218 leaves Rs 633,955. [1]
The assessment also carries an unwaived late payment penalty of Rs 126,791 and outstanding interest of Rs 287,463. The cases below assume the assessment and statement amounts are accurate and the payment reaches the appropriate account in time.
| Step or case | Calculation | Result |
|---|---|---|
| Statement tax paid | Rs 1,212,415 less Rs 74,218 | Rs 1,138,197 |
| Statement tax balance | Rs 1,846,370 less Rs 1,138,197 | Rs 708,173 |
| Tax remaining for section 42 test | Rs 708,173 less Rs 74,218 | Rs 633,955 |
| Case A: tax and unwaived penalty paid | Rs 633,955 plus Rs 126,791 = Rs 760,746 | Condition met; qualifying outstanding interest of Rs 287,463 is written off. |
| Case B: partial payment with no waiver | Rs 760,746 required less Rs 633,955 paid = Rs 126,791 short | Condition not met; confirm how the IRD allocated the payment. |
Illustrative figures: section 42(2) and (3), effective 3 June 2026, and IRD notice 03.
The partial payment must not be assumed to settle only principal: section 154 sets the payment order, and the notice describes crediting tax payments that were applied to interest. Check the actual allocation and any penalty decision against the IRD statement. [2] [4]
A year for which the full tax and applicable unwaived penalties were paid before 3 June 2026 satisfies the condition under section 42(3)(a). Apply the test separately to every relevant year. These figures illustrate the statutory test; confirm actual allocations and any waiver on the taxpayer's own record. [1]
What if the assessment is under appeal?
The IRD notice says a taxpayer may settle an assessment under administrative review or appeal and meet the conditions for relief. If the taxpayer wishes to continue the dispute, the notice provides for a written request to the Commissioner-General stating the intention to claim a refund if the final determination is favourable. [2]
Section 142 says assessed tax remains due during administrative review or a Tax Appeals Commission appeal unless the Commissioner-General extends time under section 151. [4] It describes a later refund as a Commissioner-General's initiative under section 150(4)(b), with a claim within six months of final determination. Section 150(4) addresses years commencing on or after 1 April 2024; section 150(3) addresses earlier years. Check the correct statutory basis with the IRD for an earlier assessment. [4] Keep the payment evidence, request and final determination together. A payment does not itself decide the appeal. [2]
If a return for an eligible year is under audit, the notice says the audit can be finalised before 2 December and the requirements met. Contact the relevant IRD unit promptly about the assessment and timing. The separate assessment appeal guide explains the review route. [2]
What happens if you miss 2 December?
The IRD's notice identifies 2 December 2026 as the last settlement date for this window. If the conditions are not met within it, do not assume the section 42 write-off applies to that year. Interest on unpaid tax can continue under section 157, and the separate penalty waiver process does not itself waive interest. [1] [2] [4]
Check the IRD's latest notices before paying: a later notice or instrument could change the position. This page was checked against the official sources on 13 November 2026. Ask the IRD unit handling the file about the balance and any available relief.
What this means for you
Obtain a statement broken down by tax, year, principal, penalty and interest. Reconcile tax payments allocated to interest under section 154 and confirm the section 42 calculation with the IRD unit. Pay full principal and any unwaived penalty before the stated deadline, allowing time for crediting. If disputing the assessment, follow the notice's written request procedure and record the final determination date for any refund claim.
Checklist: documents needed
- Assessment and statement for each relevant year or period
- Payment records and allocation of tax payments to interest
- Penalty assessment and any waiver decision or written request
- Review or appeal papers and payment evidence, where relevant
FAQ
Is the principal tax written off?
No. Section 42 provides for qualifying outstanding interest to be written off, subject to full payment of the principal and applicable unwaived penalties for the relevant year or period. The IRD notice gives 2 December 2026 as the final date for settlement. Check each assessment separately and pay early enough for the payment to be credited. [1] [2]
Can I request a penalty waiver?
Yes. The IRD notice says a taxpayer may request a full or partial penalty waiver for reasonable cause. After paying the full tax, submit the written request and reasons to the Commissioner of the relevant unit or regional office. A request is not an automatic waiver; settle any penalty balance still payable within the notice's deadline. [2]
Can I pay while disputing an assessment?
Yes. The notice permits payment of an assessment under review or appeal to seek this relief. A taxpayer who wishes to continue the dispute may make the written request described in the notice, stating the intention to claim a refund if the final determination is favourable. The notice states a six-month claim period after final determination. [2]
The short version
The relief concerns qualifying outstanding interest. Full tax and applicable penalties not waived must be paid for each relevant year or period within the window. The IRD names 2 December 2026 as the final settlement date. Check the balances and act early.
Talk to us. For IRD audit and inquiry support, see our income tax services or book a consultation at our contact page.
WinCore Pvt Ltd
This article is general information verified on 13 November 2026 and is not tax, legal or accounting advice on your specific position.
Sources and references (6)
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act, No. 11 of 2026, sections 1 and 42. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 13 November 2026.
- Inland Revenue Department. Notice SEC/PN/IT/2026/03, Interest relief for underpayments and late payments, conditions 1 to 3, pending audits and appeals, and Important. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/789/SEC_PN_IT_2026-03.pdf . Primary. Accessed 13 November 2026.
- Inland Revenue Department. Tax Calendar 2026, November, income tax return 2025/26. https://www.ird.gov.lk/en/publications/Tax%20Calendar_Documents/Tax_Calendar_2026_E.pdf . Primary. Accessed 13 November 2026.
- Inland Revenue Department. Inland Revenue Act No. 24 of 2017, consolidated through 31 March 2025, sections 142, 150(4), 151, 154, 157 and 176(9); read with the 2026 amendment in reference 1. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary consolidation. Accessed 13 November 2026.
- Inland Revenue Department. Notice SEC/PN/IT/2026/02, item 22, 8 June 2026. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/794/SEC_PN_IT_2026-02_E.pdf . Primary. Accessed 13 November 2026.
Related reading: Amend income tax return Sri Lanka: a guide.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationRecent articles
Continue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
Certified 3 June 2026, Act No. 11 carries nine start dates. Here is each change, the date it bites, the penalty attached and the 2 December write-off.
RAMIS penalty guide for Sri Lanka with the legal rules for late filing, late payment, interest and incorrect returns, plus practical prevention controls.
How to answer an IRD assessment: the 30-day objection, the grounds, paying while you object, and the Tax Appeals Commission deadlines and deposit.