
How to calculate quarterly income tax instalments in Sri Lanka
Five worked cases for 2026/27 instalments: expected WHT, an underpaid quarter, losses that ran out, a mid-year switch and a landlord on a salary.
On this page
Last verified against the primary sources on 22 October 2026.
To calculate quarterly income tax instalments in Sri Lanka for 2026/27, take last year's tax (A), subtract the instalments already paid and the withholding tax you have suffered or expect this year (C), and divide by the instalments left, including the current one (B). That is s.90(3) of the Inland Revenue Act as amended by Act No. 11 of 2026, for years of assessment from 1 April 2026 [4]. Payments fall due on 15 August, 15 November, 15 February and 15 May [5]. An instalment still unpaid 14 days after its due date attracts a 10 percent penalty under s.179(2), and interest runs from the due date [5] [7].
This piece is the arithmetic companion to our explainer on Circular SEC/2026/E/06, which covers the IRD's methods one by one, and to our piece on quarterly instalments after the SET form. Here we work five hypothetical cases through the formula, including the ones where it surprises people.
The formula has not changed, but A and C now mean something different
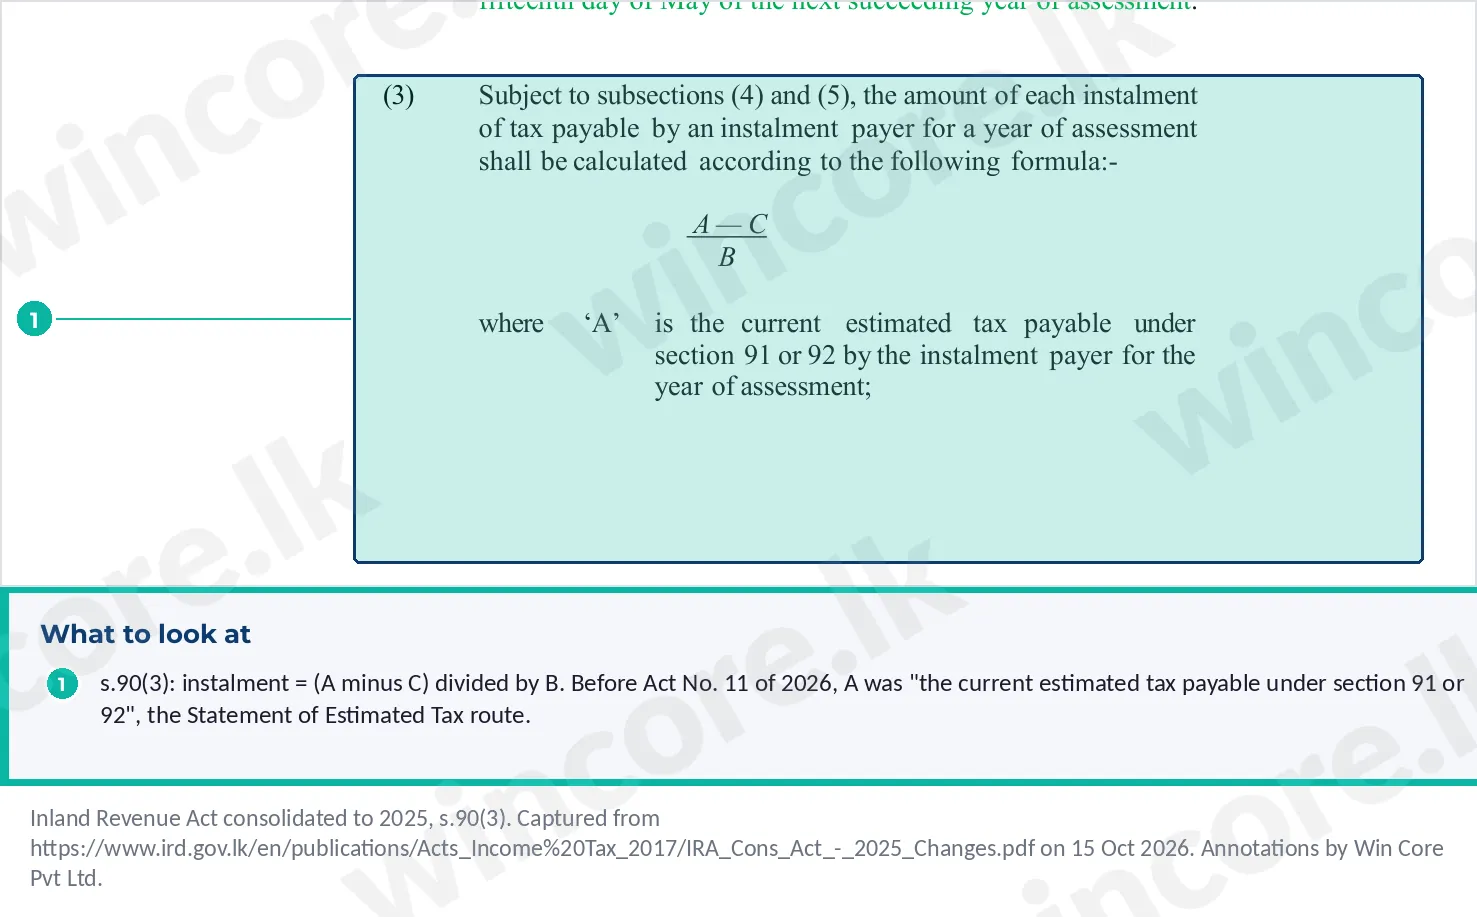
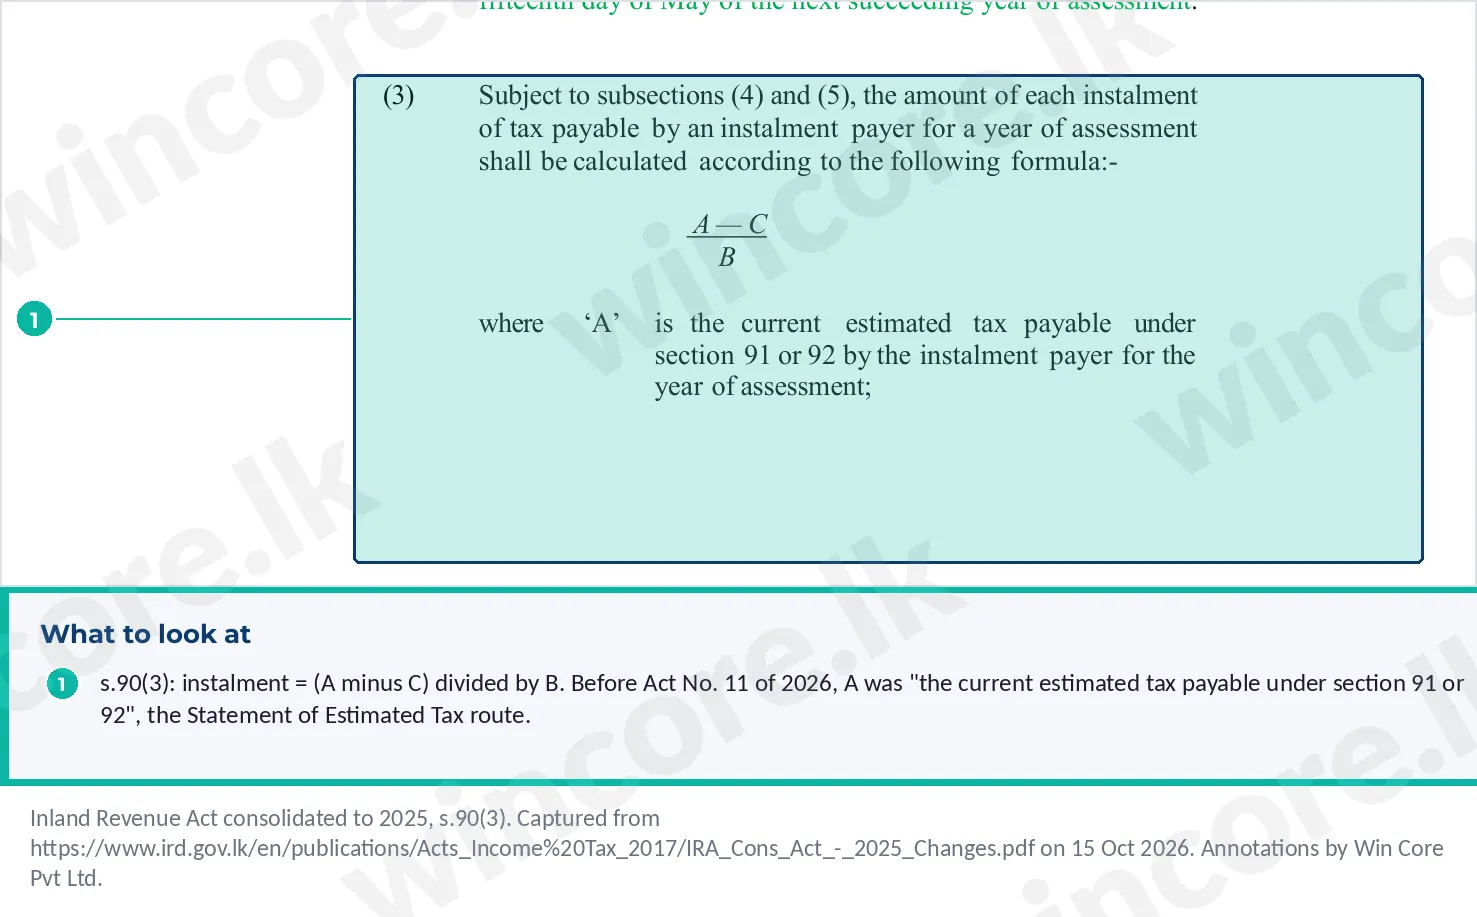
Section 90(3) still reads "A - C over B" [5]. Act No. 11 of 2026 changed what goes into it [4].
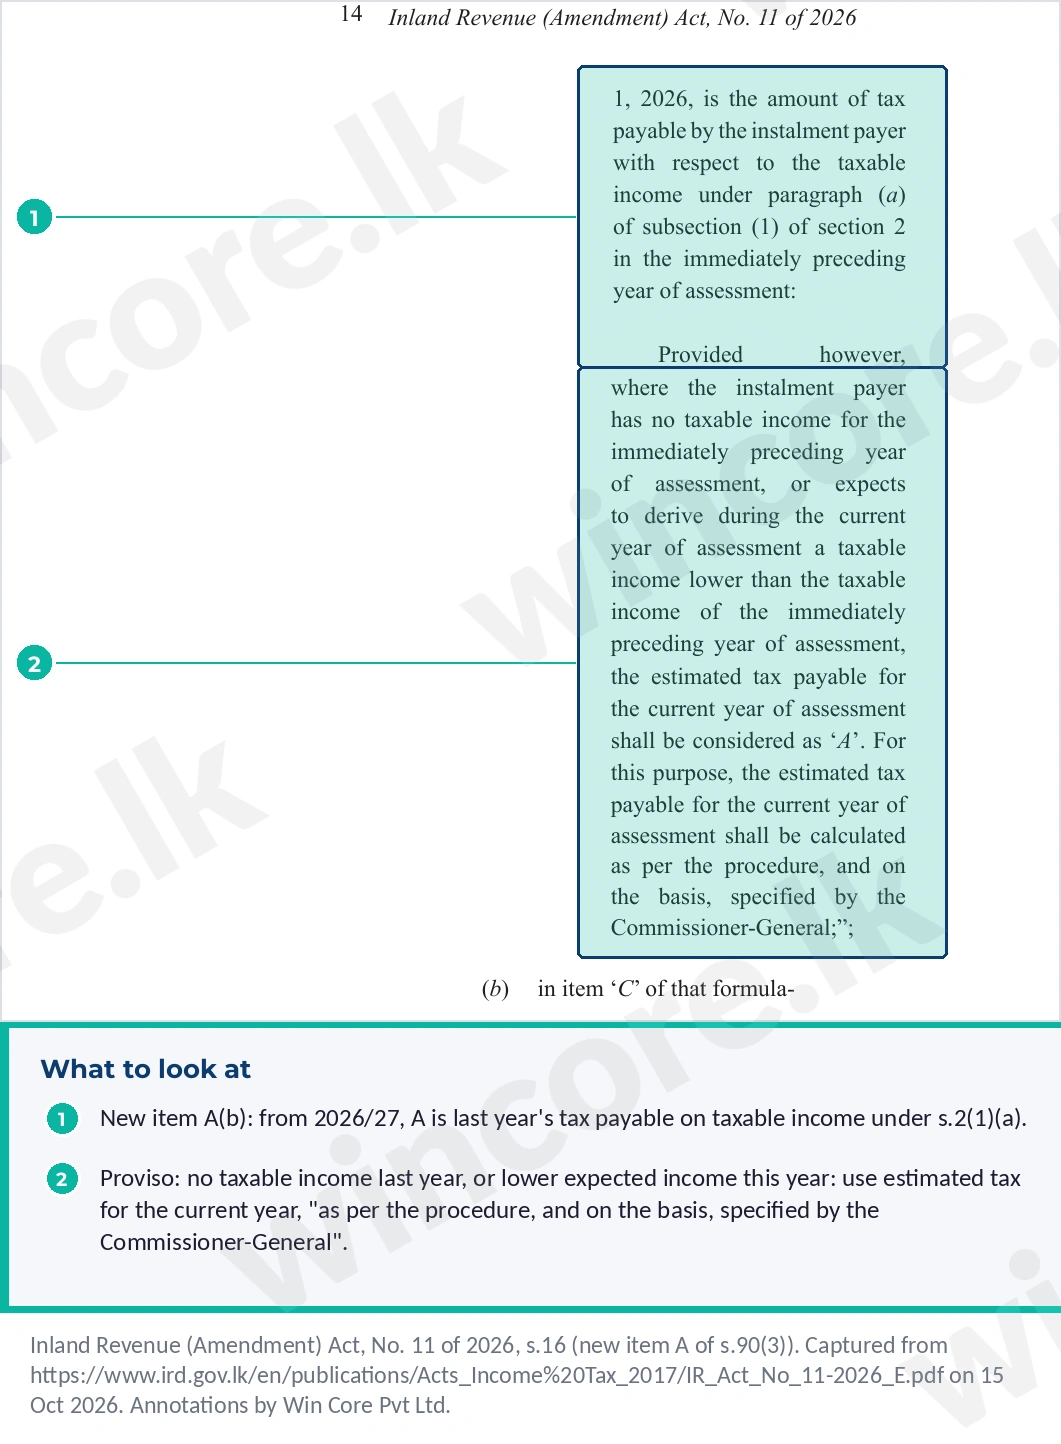
A, the annual anchor. Before 2026/27, A was "the current estimated tax payable under section 91 or 92" [5]. Sections 91 and 92 now apply only to earlier years, and the IRD's June notice lists the SET requirement as discontinued [4] [6]. From 2026/27 it is "the amount of tax payable by the instalment payer with respect to the taxable income under paragraph (a) of subsection (1) of section 2 in the immediately preceding year of assessment" [4]. The proviso is the route down: where there was no taxable income last year, or the payer "expects to derive during the current year of assessment a taxable income lower than the taxable income of the immediately preceding year of assessment", the estimated tax for the current year "shall be considered as 'A'", calculated "as per the procedure, and on the basis, specified by the Commissioner-General" [4]. The circular is that procedure [1].
B, the divisor. "the number of instalments remaining for the year of assessment including the current instalment" [5]. So 4, 3, 2, then 1.
C, the credits. Earlier instalments paid in the year; new limb (ba), "tax withheld or to be withheld during the relevant year of assessment under Division II", from 2026/27; and tax paid under s.86(3) or (4) [4] [5]. Division II of Chapter VIII covers APIT, withholding on investment returns and service fees, and AIT [5]. The words "or to be withheld" are the real change: the old limb counted only tax already withheld before the due date [5]. The circular's own Example 2 deducts a full year's expected credits at the first instalment [1].
Foreign tax. New s.90(6) lets the payer count the s.80 foreign tax credit "only if the instalment payer has paid such tax or the instalment payer reasonably estimates that such tax will be paid" in the year [4].
Gains from realising an investment asset "shall not be considered for the purpose of quarterly installments" (s.90(1) proviso) [5].
How to calculate quarterly income tax instalments: five worked examples
All five cases are invented, with round numbers. Where a rate is used, it is stated as an assumption; check the First Schedule and any exemption for your own case. Our quarterly income tax instalment calculator gives a first figure for your own numbers.
Example 1: the standard basis, with expected withholding
A hypothetical engineering contractor's 2025/26 tax was Rs 12,000,000. It expects Rs 400,000 of withholding on its deposit interest during 2026/27.
| Instalment | Due (s.90(2)) | C before payment | A minus C | B | Instalment |
|---|---|---|---|---|---|
| 1 | 15 Aug 2026 | 400,000 | 11,600,000 | 4 | 2,900,000 |
| 2 | 15 Nov 2026 | 3,300,000 | 8,700,000 | 3 | 2,900,000 |
| 3 | 15 Feb 2027 | 6,200,000 | 5,800,000 | 2 | 2,900,000 |
| 4 | 15 May 2027 | 9,100,000 | 2,900,000 | 1 | 2,900,000 |
Instalments total Rs 11,600,000; with the Rs 400,000 withheld, the year's credits equal A. If the bank ends up deducting only Rs 300,000, C was overstated by Rs 100,000. If that is picked up at the fourth instalment, C becomes Rs 9,000,000 and the last instalment rises to Rs 3,000,000.
Example 2: the same contractor underpays the first instalment
It pays Rs 2,000,000 on 15 August instead of Rs 2,900,000. At the second instalment, C is Rs 2,000,000 plus Rs 400,000, so (12,000,000 minus 2,400,000) divided by 3 is Rs 3,200,000. The formula spreads the shortfall forward. But the first instalment was still Rs 900,000 short on its due date. If it is not made good within 14 days, s.179(2) charges 10 percent of the tax due but not paid, Rs 90,000, and interest under s.157 runs from 15 August at 1.5 percent per month or part month, Rs 13,500 for each month or part month on the Rs 900,000 [5] [7]. How long that interest runs once the later, larger instalments are paid is an open point below.
Example 3: Method 2(ii), losses that ran out
A hypothetical tea exporter had business income of Rs 20,000,000 in 2025/26, wiped out by brought-forward losses, so its taxable income was nil. The losses are now used up. The circular says A is then calculated by applying "all taxing rules and the income tax rates specified in the First Schedule to the IR Act to the taxable income of immediately preceding year of assessment, disregarding any losses deducted or tax exemptions applied in that year" [1]. Assuming, for illustration only, a 30 percent rate, A is Rs 6,000,000. With no expected withholding, the first instalment is Rs 1,500,000. The circular's own Example 3 works a similar expiring-loss case [1].
If the 2025/26 computation was not final by 15 August, the circular lets such a taxpayer use the final 2025/26 SET for the first instalment, but "for the 2nd quarter installment, this should be revised on the basis of the tax return", "with only one revision permitted" [1].
Example 4: a mid-year switch to the lower-income basis
The contractor in Example 1 pays Rs 2,900,000 on 15 August and 15 November. In December its largest customer leaves. Under Method 2(iii) it recalculates its 2025/26 tax "by excluding the gains or profits from business or investment activities that are not expected to arise in the current year", which gives Rs 8,000,000 [1]. A Method 1 payer may, on or before the last day of the month before the next instalment (31 October, 31 January or 30 April), "inform a revision to the basis of calculation" where its projected taxable income is lower than last year's, and then adopt Method 2 or Method 3 [1]. It informs the CDMU by 31 January 2027 with supporting calculations.
Third instalment: C is Rs 5,800,000 plus Rs 400,000, so (8,000,000 minus 6,200,000) divided by 2 is Rs 900,000. Fourth instalment: C is Rs 7,100,000, so Rs 900,000. The two instalments already paid are not reopened by the formula. The circular's Attachment declaration states that "giving false information is an offence" [1], so the recalculation needs to hold up; we have not mapped that declaration to a penalty section.
Example 5: a salaried landlord
A hypothetical salaried individual also lets a flat at Rs 125,000 a month. Tax on 2025/26 income was Rs 560,000, but a rent cut from April means tax on total 2026/27 income is expected to be Rs 500,000. Because expected income is lower than last year's, the proviso to item A lets that estimate be A, on the IRD's procedure [4]. The employer will deduct Rs 330,000 of APIT, and the tenant Rs 150,000 of AIT, since rent above Rs 100,000 a month to a resident attracts 10 percent [5]. The circular says APIT "deducted or expected to be deducted by the employer" may be subtracted "before applying the formula" [1], and the tenant's AIT is Division II withholding counted in C [4]. (500,000 minus 330,000 minus 150,000) divided by 4 is Rs 5,000 a quarter. Had the AIT covered the whole remaining liability, the circular says no instalments and no credit schedule are needed [1].
One drafting detail. Act No. 11 limited the old APIT proviso to years "prior to the year of assessment commencing on April 1, 2026" [4]. For 2026/27 the statutory home of the APIT credit is limb C(ba). On our reading the arithmetic is the same, because subtracting a credit from A or adding it to C gives the same A minus C.
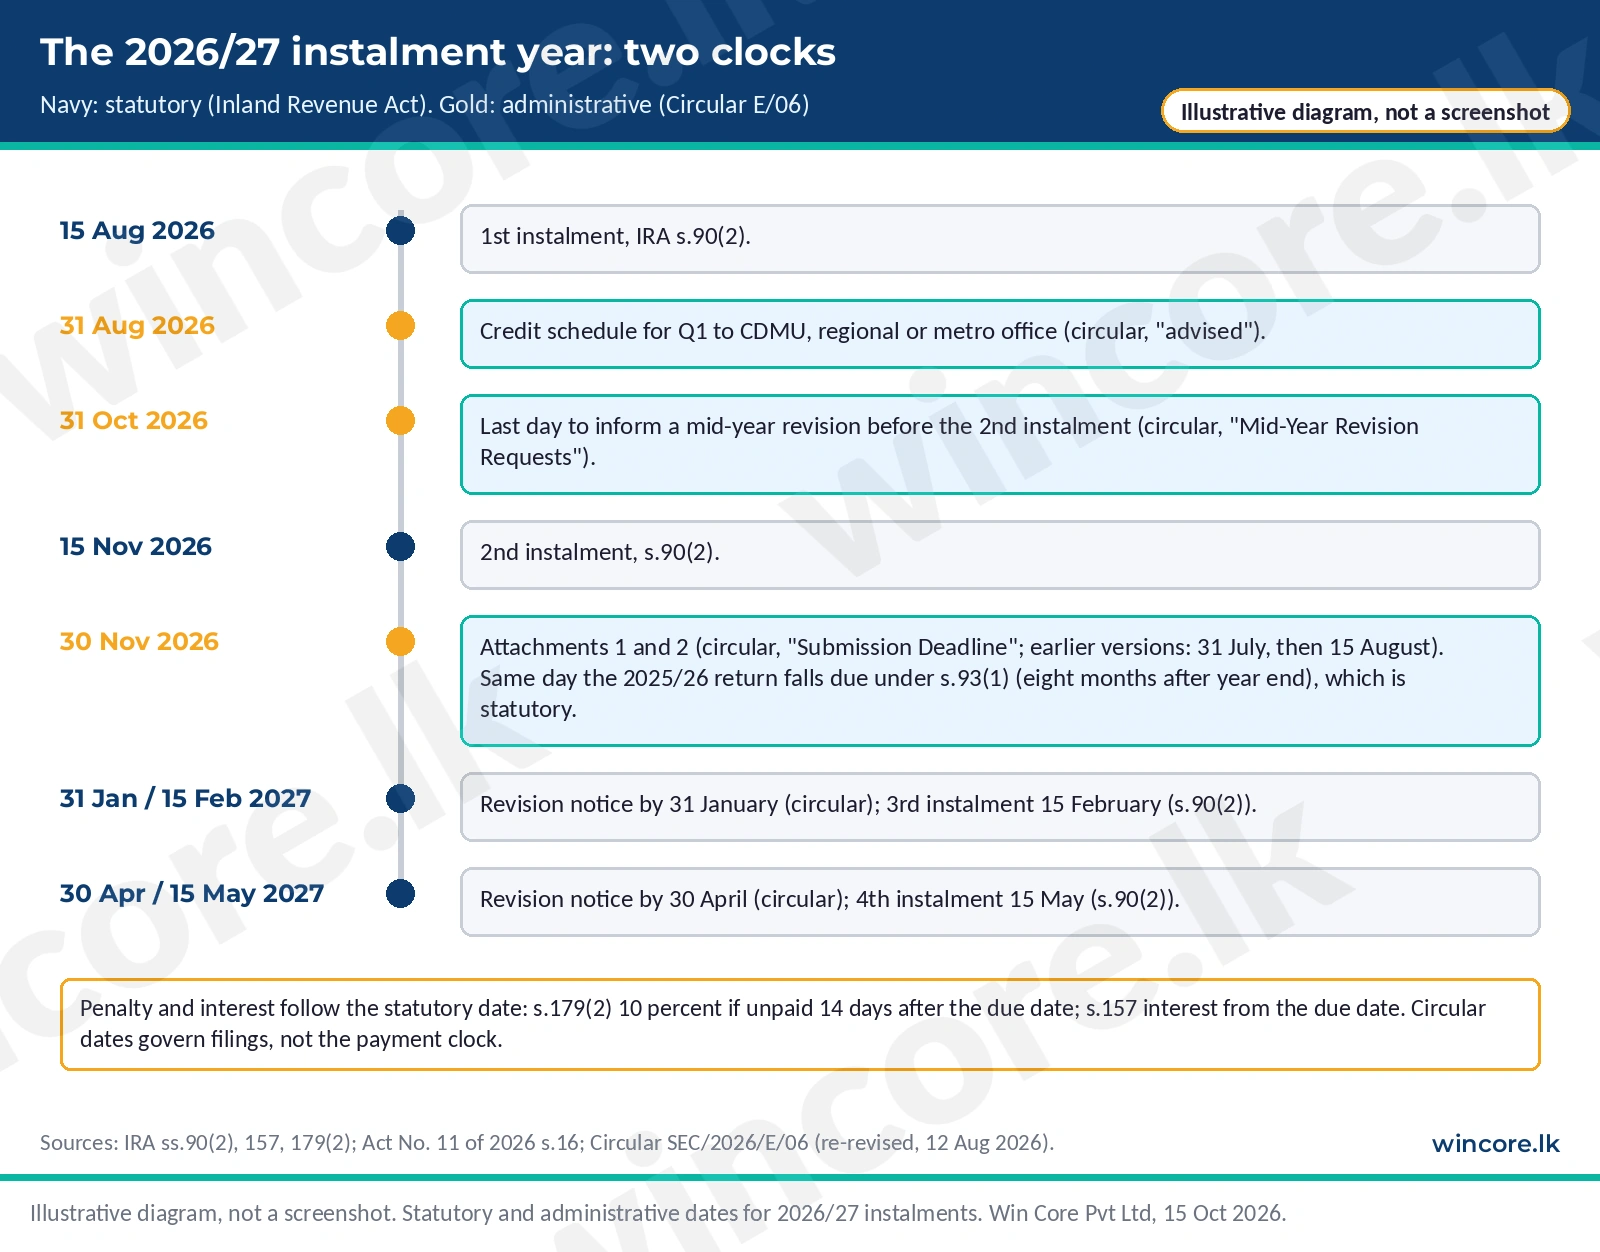
The Act sets the payment dates; the circular sets the filing dates
| Date | What | Source | Type |
|---|---|---|---|
| 15 Aug, 15 Nov 2026; 15 Feb, 15 May 2027 | Instalments due "on or before the fifteenth day" | IRA s.90(2) [5] | Statutory |
| 14 days after each 15th | Point at which the s.179(2) penalty attaches | IRA s.179(2) [5] | Statutory |
| 30 Nov 2026 | 2025/26 return due "on or before 30 November 2026" | IRD return guide [7]; eight months under IRA s.93(1) as enacted | Statutory |
| 31 Aug, 30 Nov 2026; 28 Feb, 31 May 2027 | Credit schedule to the CDMU | Circular, "Credit Schedules" [1] | Administrative |
| 30 Nov 2026 | Attachments 1 and 2 | Circular, "Submission Deadline" [1] | Administrative |
| 31 Oct 2026, 31 Jan, 30 Apr 2027 | Inform a mid-year revision | Circular, "Mid-Year Revision Requests" [1] | Administrative |
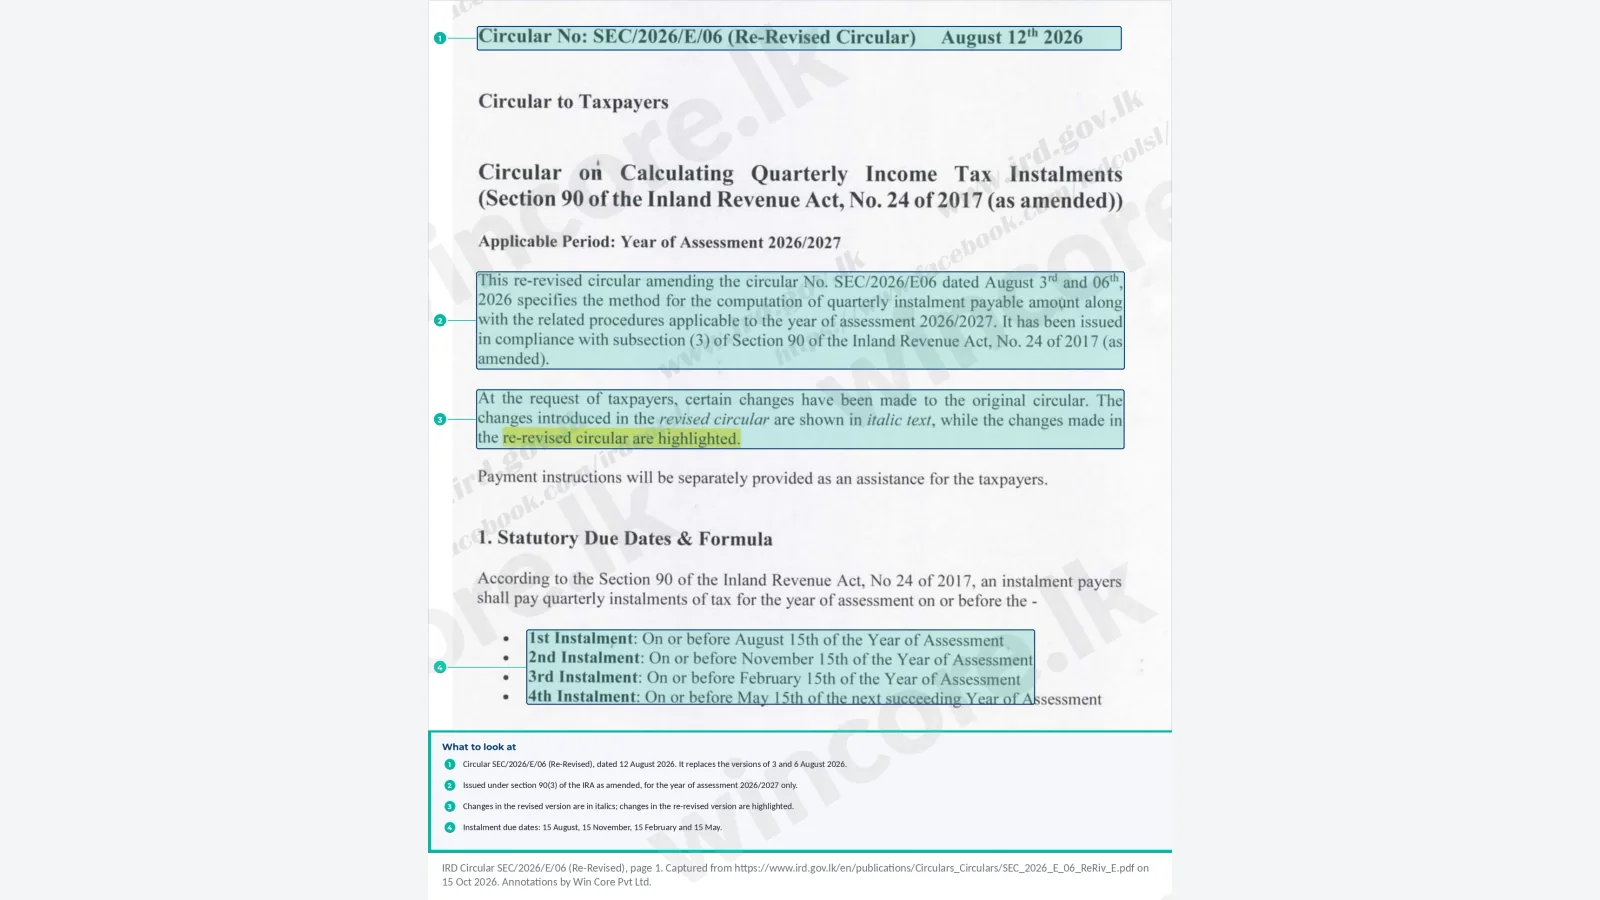
The circular was issued three times in August 2026, and the Attachment deadline moved from 31 July to 15 August and then to 30 November 2026 [1] [2] [3]. None of that moved a payment date. The re-revised version says its specifications "relate solely to the calculation of amount 'A' in the formula" and that B and C "remain unchanged" [1]. Our Circular SEC/2026/E/06 explainer tables the three versions.
A late instalment costs 10 percent after 14 days, plus interest from the 15th
| Default | Section | Consequence |
|---|---|---|
| Instalment not paid, in whole or part, within fourteen days of the due date | s.179(2) | "a penalty equal to ten per cent of the amount of tax due but not paid" [5] |
| Any tax not paid by the due date | s.157(1), rate in s.159(1) | Interest at "one and one-half per cent per month or part month, computed monthly" [5] |
| Tax due for a tax period not paid "within fourteen days of the due date, or by the due date specified in the notice of assessment, if later" | s.179(1) | "a penalty equal to twenty per cent of the amount of tax due but not paid", suspended while a s.151 extension runs (s.179(3)) [5] [7] |
| Unpaid tax with no review or appeal pending | s.163(4A) | Recovery as a deemed fine through the Magistrate's Court [4] |
The 14 days in s.179(2) do not delay the instalment due date, and s.157 interest runs from the 15th. The circular warns that under Method 1 "Any under payment, late payment or no payment will attract an interest and penalty" [1], which points back to the same sections. Our guide to RAMIS penalties covers late filing and late payment across the return.
Four misreadings of the formula
- "Each instalment is a quarter of last year's tax." Only when credits arrive evenly, as in Example 1. Underpayments, late withholding and revisions change later instalments.
- "The 30 November date gave us until November to pay." It covers Attachments, not payment [1].
- "Catching up at the next quarter cures the shortfall." It closes the year-end gap. It does not undo a s.179(2) penalty that has already attached.
- "No SET means no estimate." The proviso to item A still uses an estimate, on the IRD's procedure [4].
What this means for you
From 2026/27, treat last year's tax as your instalment base unless you can document a lower figure under the circular. Then:
- Compute A from the 2025/26 return once it is final, before deducting credits, as the circular reads it [1].
- List the Division II credits you expect for the full year and keep the certificates as they arrive.
- Recalculate every quarter. Each instalment is a fresh (A minus C) divided by B, not a quarter of the year.
- Pay by the 15th. The 14 days in s.179(2) relate only to the penalty.
- Diary the circular dates separately: credit schedules at month end, Attachments by 30 November 2026, revision notices by 31 October, 31 January or 30 April.
Good bookkeeping behind each credit figure makes step 3 quick. Our income tax services team can run the computation, the credit schedule and any Attachment with you.
Checklist: documents needed
- The final 2025/26 tax computation or return, which gives A
- The final 2025/26 SET, if you use the first-quarter bridge under Method 2(ii) or 2(iii)
- WHT, AIT and APIT certificates received, and a forecast of withholding expected in 2026/27, which give C
- Receipts for every 2026/27 instalment already paid
- For a lower basis, the Method 2 calculations and Attachment 1 or 2
- Any mid-year revision notice sent to the CDMU, with the date it was sent
Open points we are keeping open
- Attribution of catch-up payments. In Example 2, the Act does not say whether a larger second instalment is set against the first-quarter shortfall for s.157 interest. We have not seen IRD guidance on this.
- C greater than A. If credits exceed A after a revision, the formula gives a negative figure. The Act and the circular do not say how that is handled during the year.
- Investment-asset gains in A, and gross or net A, remain open as stated in our Circular SEC/2026/E/06 explainer.
- APIT drafting. The circular subtracts APIT before the formula; the statutory proviso it reflects now applies only to earlier years, though limb C(ba) gives the same result on our reading.
FAQ
How do I calculate my first quarterly instalment for 2026/27?
Take your 2025/26 tax on taxable income as A, subtract the withholding tax you expect for the whole of 2026/27 as C, and divide by 4. A company with Rs 12 million of 2025/26 tax and Rs 400,000 of expected withholding pays Rs 2.9 million by 15 August 2026, unless it qualifies for a lower basis under the circular [1] [4].
Can I deduct withholding tax I have not suffered yet?
Yes, if it is tax "to be withheld" during the year under new limb C(ba) of s.90(3) [4]. The circular's own example deducts a full year's expected credits at the first instalment [1]. If the withholding then falls short, C was overstated, and the later instalments have to rise to make up the difference before the year ends.
What is the penalty for a late quarterly instalment in Sri Lanka?
An instalment not paid within 14 days of its due date attracts a penalty of 10 percent of the amount unpaid under s.179(2) [5]. Interest at 1.5 percent per month or part month also runs from the due date itself under ss.157 and 159(1) [5]. A balance unpaid fourteen days after its due date attracts 20 percent under s.179(1) [5].
Did the 30 November 2026 deadline move the instalment dates?
No. The 30 November 2026 date in the re-revised circular covers Attachments 1 and 2 only [1]. The payment dates of 15 August, 15 November, 15 February and 15 May are set by s.90(2) of the Act [5], and the interest and penalty clocks run from those statutory dates, not from the circular's filing dates.
What if my income will be lower than last year?
You can move to a lower basis. Inform the CDMU, with supporting calculations, by the last day of the month before the next instalment (31 October, 31 January or 30 April), then use Method 2 or Method 3 [1]. Instalments already paid are not reopened; the lower A applies to the remaining quarters through the formula.
Talk to us. If you want your 2026/27 instalments worked through or a lower basis documented before the next due date, contact us at our contact page.
WinCore Pvt Ltd
This article is general information on the law as at 22 October 2026 and is not advice on your specific position.
References
- Inland Revenue Department. Circular to Taxpayers: Circular on Calculating Quarterly Income Tax Instalments, SEC/2026/E/06 (Re-Revised Circular) (12 August 2026), Methods 1 to 3, Credit Schedules, Mid-Year Revision Requests, Submission Deadline, Examples 2 and 3, Attachment 1. https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2026_E_06_ReRiv_E.pdf . Primary. Accessed 22 October 2026.
- Inland Revenue Department. Circular on Calculating Quarterly Income Tax Instalments, SEC/2026/E/06 (Revised) (6 August 2026). https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2026_E_06_Riv_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Circular on Calculating Quarterly Income Tax Instalments, SEC/2026/E/06 (3 August 2026). https://www.ird.gov.lk/en/publications/Circulars_Circulars/SEC_2026_E_06_E.pdf . Primary. Accessed 15 October 2026.
- Parliament of Sri Lanka. Inland Revenue (Amendment) Act, No. 11 of 2026, ss.16, 17, 18 and 28. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 22 October 2026.
- Inland Revenue Department. Inland Revenue Act, No. 24 of 2017, consolidated with amendments to 2025, ss.84A, 90, 157, 159 and 179, the First Schedule rate for rent under s.84A(1A), and Chapter VIII Division II. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary. Accessed 22 October 2026.
- Inland Revenue Department. Notice to the Taxpayers: Amendments to the Inland Revenue Act, No. 24 of 2017, SEC/PN/IT/2026/02 (8 June 2026), item 11. https://www.ird.gov.lk/en/Lists/Latest%20News%20%20Notices/Attachments/794/SEC_PN_IT_2026-02_E.pdf . Primary. Accessed 15 October 2026.
- Inland Revenue Department. Guide to the Return of Income Tax, Y/A 2025/26, Section 09 (penalty of 20 percent of the tax due but not paid; 10 percent on an instalment; interest at 1.5 percent a month or part month). https://www.ird.gov.lk/en/Downloads/IT_Individuals_Doc/Asmt_IIT_004_2025_2026_E.pdf . Primary. Accessed 22 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationContinue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
The IRD rewrote its instalment circular twice in nine days. What the 12 August version says on A, C, Method 2, the SET bridge and the November dates.

The SET filing requirement is gone from Y/A 2026/27. Quarterly instalments now follow a formula based on the previous year's tax. Here is how it works.

RAMIS penalty guide for Sri Lanka with the legal rules for late filing, late payment, interest and incorrect returns, plus practical prevention controls.