Who can represent you before the IRD: section 195 and your duties
Your consultant can file and argue your case, but you still sign, keep the records and carry the penalties. The clauses, and the questions to ask.
On this page
Last verified against the primary sources on 26 October 2026.
Who can represent me before the IRD in Sri Lanka? A tax consultant can register you, prepare and file your returns on RAMIS, run withholding and instalments, and take an assessment through review and appeal. The liability stays with you, and this guide to IRD representation shows where the Inland Revenue Act, No. 24 of 2017 (the Act) draws that line. You or your "duly authorised agent" sign the return, "attesting to its accuracy and completeness" (s.126(4)); penalties are assessed on the person liable (s.176(6)); and your records stay with your business for at least five years (s.120(6)) [1].
Who may act for you is also set by law. Section 195 defines an "authorised representative" by a list, and since 3 June 2026 that list names members of the Chartered Institute of Taxation of Sri Lanka [2].
IRD representation: the work moves, the legal duties do not
A consultant takes over the preparation; the Act still puts each duty on you.
| Task | What a consultant usually does | What the law leaves with you |
|---|---|---|
| Registration | Prepares the TIN and tax type applications | The duty to register is yours (s.102); failure carries a penalty of up to Rs 50,000 (s.177) |
| Income tax return | Prepares the return and files it on RAMIS | You or your duly authorised agent sign it (s.126(4)); due eight months after the year of assessment ends, so 30 November (s.93(1)) |
| APIT and WHT or AIT | Computes the deductions and the schedules | As withholding agent you pay within fifteen days after the month ends (s.86(1)) and file the annual statement within thirty days after 31 March (s.86(2)) |
| VAT | Prepares the return and the schedules | Tax paid by the 20th of the month after the taxable period (VAT Act s.26(1)); return by the last day of that month (s.21(1)(a)(iii)) [9] |
| Quarterly instalments | Works out each instalment | An instalment unpaid fourteen days after its due date costs 10% of the unpaid amount (s.179(2)) |
| Assessment | Drafts the request for administrative review | In writing within thirty days of notification, with detailed grounds (s.139(2)); the tax stays payable unless time is extended (s.142) |
For a company, section 146(1)(b) makes "a director or principal officer of the company" its representative, and section 146(6) makes every representative "responsible for performing duties or obligations imposed by this Act on the person, including maintaining records, filing returns and other documents, and the payment of tax" [1]. An outside agent fills that role only where no principal officer resides in Sri Lanka (s.146(4)). On our reading, hiring a consultant does not move this off your directors.
Who can represent me before the IRD in Sri Lanka? The section 195 list
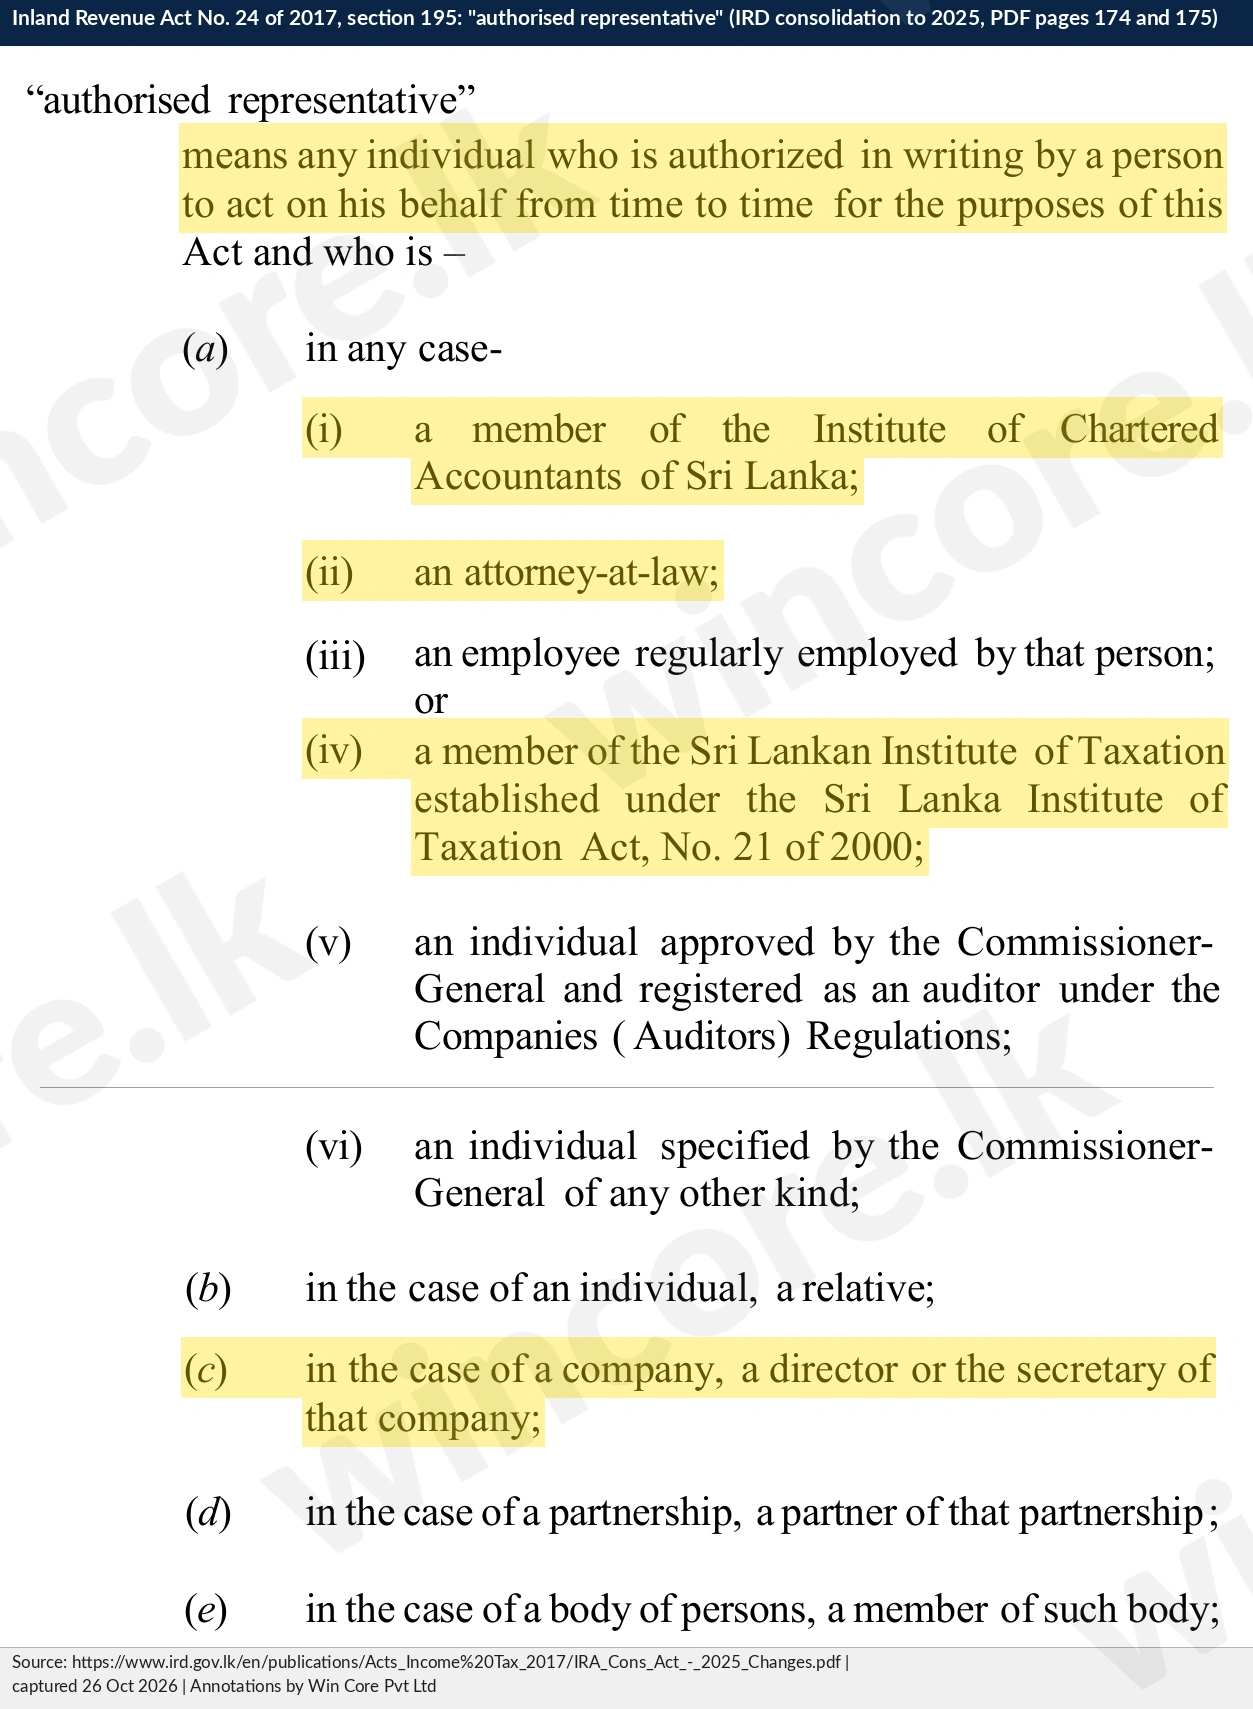
The Act does not use the words "tax consultant" or "tax agent" (word search of the IRD consolidation and of Act No. 11 of 2026, 26 October 2026). Its term is "authorised representative": in section 195, "any individual who is authorized in writing by a person to act on his behalf from time to time for the purposes of this Act" and who is a member of the Institute of Chartered Accountants of Sri Lanka, an attorney-at-law, your regular employee, a member of the tax institute in sub-paragraph (iv), an approved registered auditor, or an individual the Commissioner-General specifies. It also lists a relative (for an individual), a director or the secretary (company), a partner (partnership) and a member (other bodies of persons) [1].
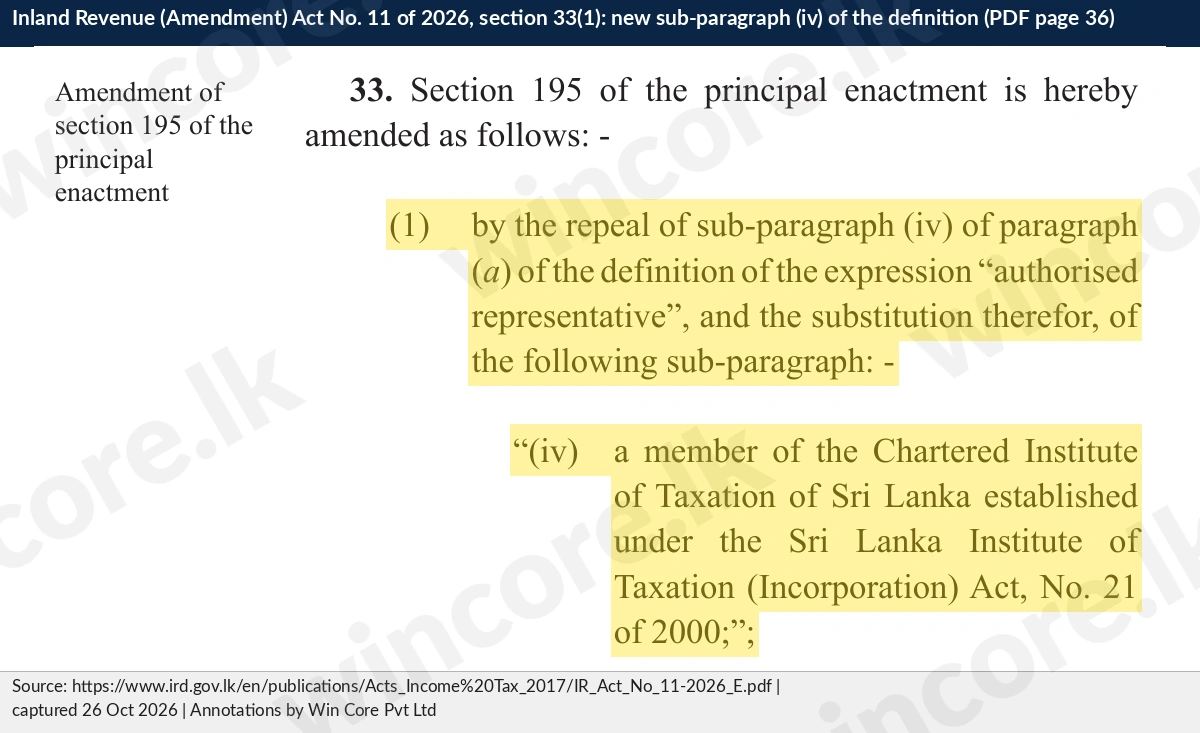
Section 33(1) of the Inland Revenue (Amendment) Act, No. 11 of 2026 replaced sub-paragraph (iv) with "a member of the Chartered Institute of Taxation of Sri Lanka established under the Sri Lanka Institute of Taxation (Incorporation) Act, No. 21 of 2000" [2]. Section 33 is not in the Act's table of special dates, so under section 1(2) it operates from certification on 3 June 2026. The earlier amending Acts (No. 10 of 2021 to No. 2 of 2025) do not touch this definition.
Section 115 lets the Commissioner-General "specify the circumstances under which a taxpayer may designate an authorized representative to communicate with the Department on behalf of the taxpayer" [1]. On RAMIS, the IRD's e-Services page offers "Authorisation of Staff/Tax Agent", described as "To authorise staff/Tax agent to act on your behalf for tax matters", and a separate "Tax agent" login profile [5]. On our reading, that authorisation is the clean route: the consultant works under its own access and your own PIN stays with you.
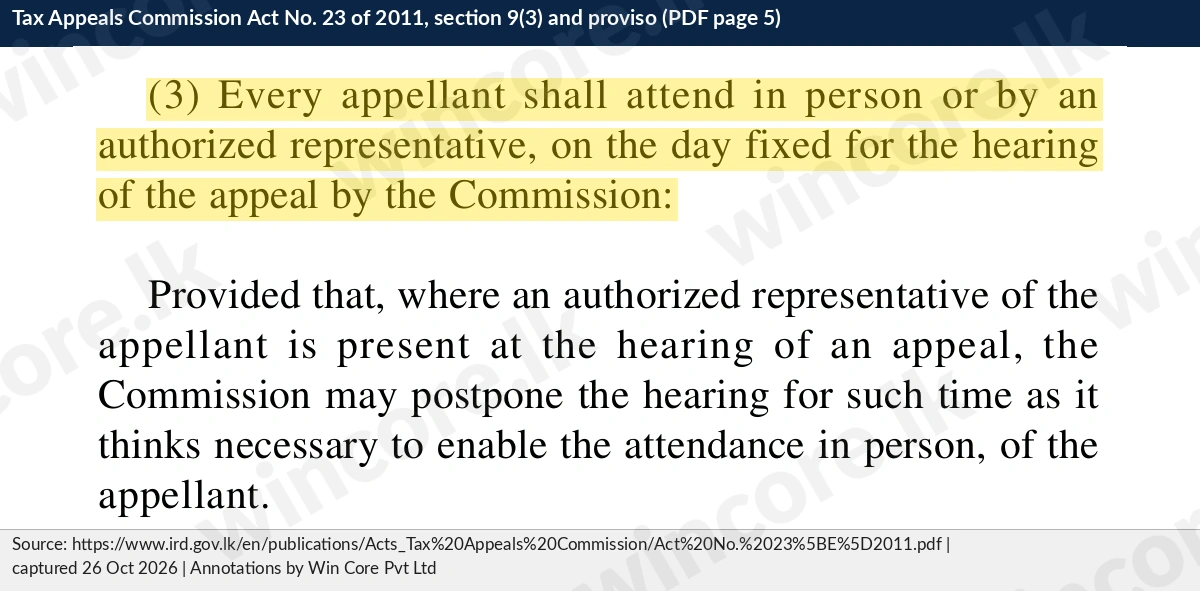
Appeals follow a second Act. After administrative review, you may petition the Tax Appeals Commission within thirty days of the Commissioner-General's decision, or of seven months passing without one (s.140(2) and (5)) [1]. Section 9(3) of the Tax Appeals Commission Act, No. 23 of 2011 then reads: "Every appellant shall attend in person or by an authorized representative, on the day fixed for the hearing of the appeal by the Commission". Under the proviso, where your authorized representative is present, the Commission may still postpone the hearing "to enable the attendance in person, of the appellant" [6]. That Act does not define the term, and its amending Acts No. 4 of 2012 and No. 20 of 2013 left subsection (3) unchanged. On our reading, the safe choice is someone on the section 195 list; we keep that point open. If you disagree with an assessment, see how an IRD assessment appeal works.
In 2024 the Chartered Institute of Taxation of Sri Lanka asked the Government to legally recognise the profession of "Tax Consultant" [8] (Secondary). So check what a person is under section 195, not what they call themselves.
You or your agent sign the return, and a paid preparer must certify their part
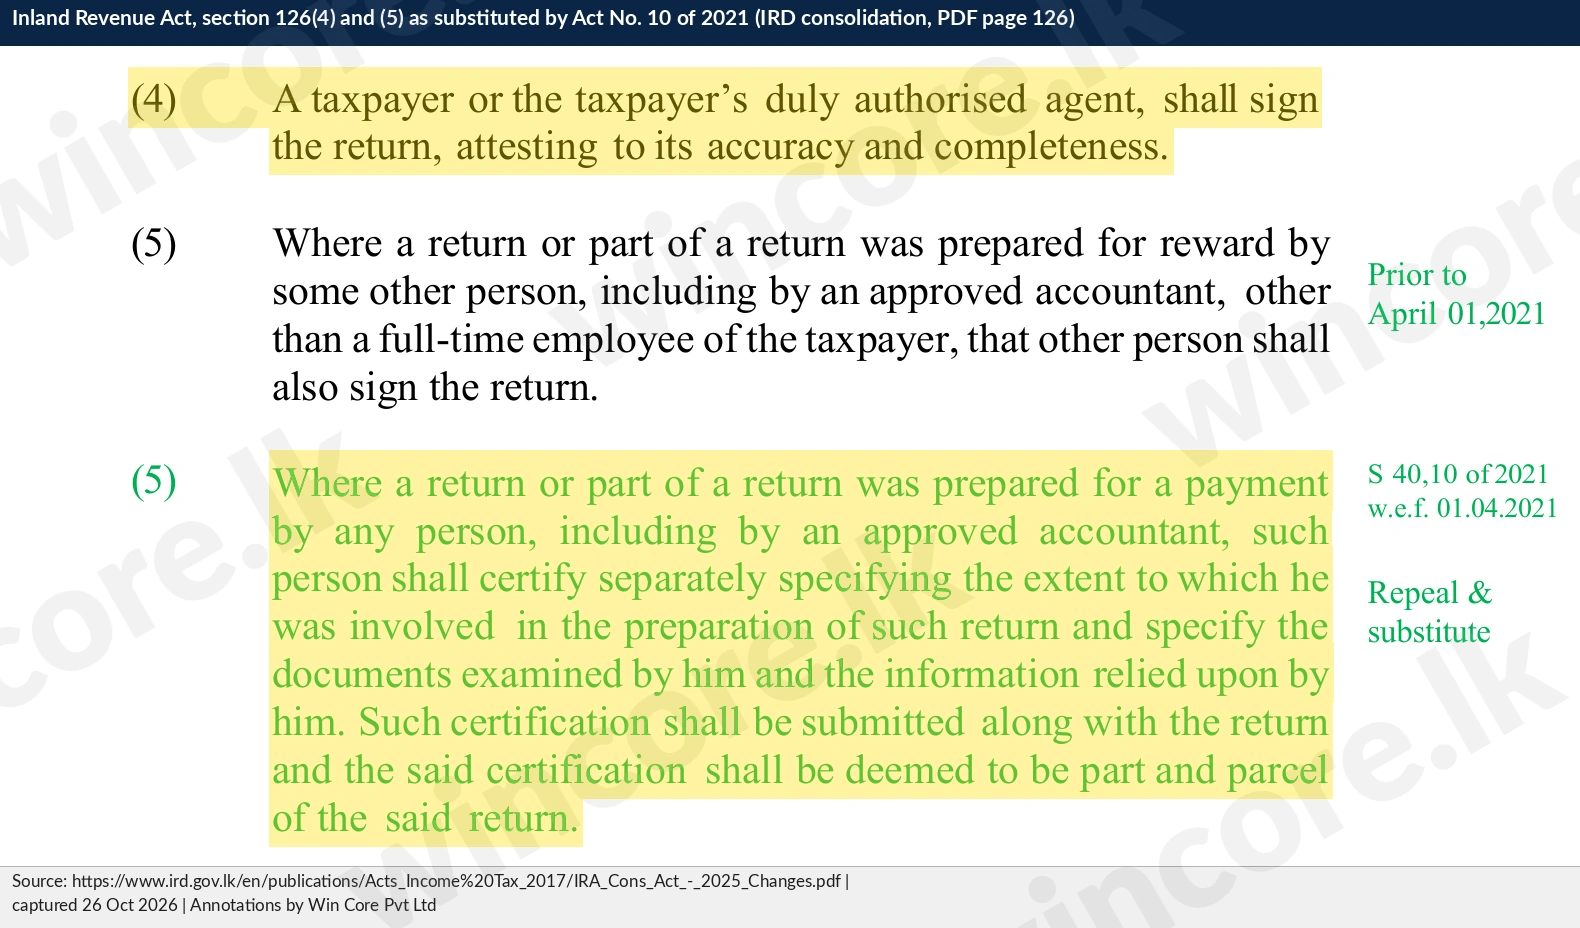
Section 126(4): "A taxpayer or the taxpayer's duly authorised agent, shall sign the return, attesting to its accuracy and completeness." Section 126(5), as substituted by section 40 of Act No. 10 of 2021 from 1 April 2021, adds that where a return "was prepared for a payment by any person, including by an approved accountant, such person shall certify separately specifying the extent to which he was involved in the preparation of such return and specify the documents examined by him and the information relied upon by him." That certification goes in with the return and is "deemed to be part and parcel of the said return" [1] [3].
Two deeming rules then hold the return against you. Under section 128 a return furnished on your behalf is deemed furnished with your authority "unless the contrary is proved", and the signer is "deemed to be cognisant of all matters contained therein". Section 131 says the same of a return filed on your behalf [1]. So read the return before it goes in, and ask for the section 126(5) certification. It lists the documents the preparer examined, which is your record of what they were and were not given. Our RAMIS filing guide covers the filing steps.
Penalties are charged to the taxpayer, not to the consultant
A penalty notice "shall be served on the person who is liable to the penalty" (s.176(6)) [1]. The common ones each fall on the person with the duty:
- Late return: the greater of 5% of the tax owing plus 1% a month, or Rs 50,000 plus Rs 10,000 a month, capped at Rs 400,000 a return (s.178(1) and (2)).
- Late payment: 20% of the tax due but not paid, where it is not paid "within fourteen days of the due date, or by the due date specified in the notice of assessment, if later" (s.179(1)); 10% for an instalment (s.179(2)); suspended while a section 151 extension runs (s.179(3)).
- Underpayment from an incorrect return: 25% of the underpayment, or 75% where it is higher than Rs 10 million or higher than 25% of the liability, where the error results from "intentional conduct or negligence on the part of the taxpayer" (s.180).
Section 176(9) lets the Commissioner-General refrain from or waive a penalty where reasonable cause is shown [1]. For errors in your return, the Act does not charge the preparer; its own exposure there turns on fraud or wilful conduct: section 190A (fraudulently preparing or certifying a document for the Commissioner-General, fine up to Rs 1 million or up to six months), section 187 (wilfully aiding or abetting an offence) and section 190 (wilfully impeding the Department, including by a false or misleading statement to a tax official). On our reading, a consultant's mistake does not shift the penalty to the consultant; any claim against them rests on your engagement terms. Our guide to RAMIS penalties works through the formulas, and the penalty calculator runs them.
Records stay with you for five years, and errors are fixed within twelve months
Section 120(1) requires records "sufficient to record all transactions", kept in Sri Lanka. Section 120(4) keeps them "at the place of business or investment activity of the person unless the Commissioner-General approves of them being kept at some other place". Section 120(5) adds source documents such as invoices and bank statements (s.120(10)). Section 120(6) sets the period: "five years from the date on which the transaction took place" or, if longer, "until expiration of the time limit for assessment of tax for any tax period to which the records are relevant and until any related proceedings have been completed" [1].
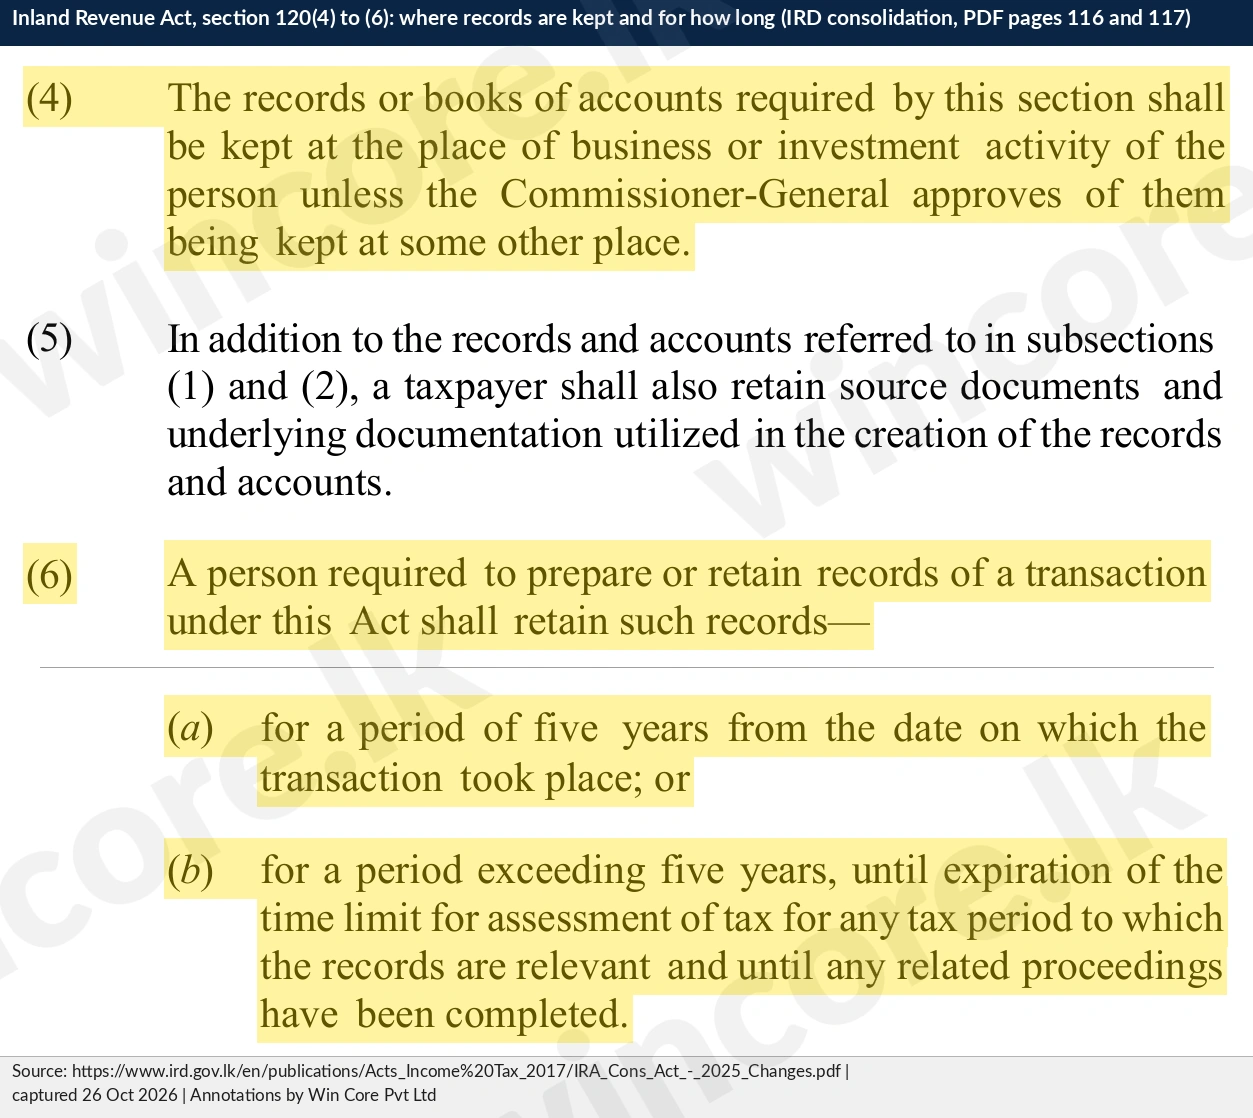
On our reading, if your only set of books sits at the consultant's office, that is "some other place" needing the Commissioner-General's approval. Keep the originals, or a complete copy, at your premises.
Errors in an income tax return are corrected by applying to amend the self-assessment under section 136. The application states the amendments and the reasons, and for a year of assessment starting on or after 1 April 2022 it must be filed "within a period of twelve months from the date on which the self-assessment return was filed" (s.136(2), as amended by Act No. 45 of 2022) [1] [4]. With no decision within ninety days, it is deemed refused (s.136(6)).
Worked example: an electrical contractor with VAT, APIT and WHT
An invented example: an electrical contracting company with turnover of about Rs 140,000,000 a year files VAT quarterly, has 11 staff on payroll and rents its workshop from a resident individual for Rs 150,000 a month. A consultant prepares its filings.
| Obligation | Rule | Amount or date |
|---|---|---|
| AIT on rent | Rent to a resident above Rs 100,000 a month: 10% on the full amount (First Schedule para 10(1)(d)(iii)) | Rs 15,000 withheld; landlord receives Rs 135,000 |
| Pay November AIT and APIT | Within fifteen days after the month ends (s.86(1)) | By 15 December 2026 |
| Certificate to the landlord | Within thirty days after the month ends (s.87(3)) | By 30 December 2026 |
| Quarterly AIT statement, October to December 2026 | Within thirty days after the quarter ending 31 December (s.86(8)) | By 30 January 2027 |
| VAT for October to December 2026 | October tax by 20 November, November tax by 20 December, balance by 20 January (VAT Act s.26(1) proviso, on our reading of the quarterly rule) | Return by 31 January 2027 (s.21(1)(a)(iii)) |
| Annual withholding statement, Y/A 2026/27 | Within thirty days after 31 March (s.86(2)) | By 30 April 2027 |
| Income tax return, Y/A 2026/27 | Eight months after the year ends (s.93(1)) | By 30 November 2027 |
| Amending that return | Twelve months from filing (s.136(2)(b)); filed 25 November 2027 | Apply by 25 November 2028, on our reading of the count |
Now suppose the November AIT of Rs 15,000 is paid on 5 January 2027. Fourteen days after the 15 December due date ended on 29 December, so section 179(1) applies: 20% of Rs 15,000 is Rs 3,000, plus interest under section 157(1) at 1.5% a month or part month (s.159(1)), which is Rs 225 for the part month from 15 December to 5 January [1]. The notice goes to the company, whoever missed the date.
To check the withholding for other payments, use our withholding tax calculator.
Check these points before you engage a tax consultant
Membership you can verify yourself. Ask which section 195 category the person falls in and for their membership number. CA Sri Lanka publishes a "Practicing Members List" on its own website [7]; for the Chartered Institute of Taxation of Sri Lanka, confirm the number with the Institute. Our guide to comparing accounting firms in Sri Lanka covers the wider shortlist.
A written engagement letter. This is practice, not a legal requirement. It should list the taxes and years covered, the deadlines, the documents you send and when, and who approves and files each return.
RAMIS access. Agree whose login files each return. Use the "Authorisation of Staff/Tax Agent" route rather than sharing your TIN and PIN, and withdraw it when the engagement ends.
Records and corrections. Agree where the books are kept (s.120(4)), how errors are fixed within the section 136 window, and who bears the cost of the preparer's own error.
Questions for a first meeting:
- Which section 195 category are you in, and what is your membership number?
- Who prepares my returns, and who reviews them?
- Will you give the section 126(5) certification with each return?
- Will you file under your own tax agent access, or do you need my login?
- What happens to my records and RAMIS access if we stop working together?
What this means for you
Hire a consultant for the work, not the liability. The return counts as yours even when an agent signs; you still pay, keep the records and receive the penalty notices. Confirm the person fits the section 195 list, get the scope in writing, authorise them on RAMIS instead of sharing your PIN, and keep your books at your place of business. If you are setting up, register your TIN and tax types first; if you file as an individual, our income tax return filing guide covers the return itself.
Checklist: documents needed
- Written authority for your representative, naming what they may do
- Signed engagement letter with scope, years, deadlines and filing responsibility
- Proof of the representative's membership or category under section 195
- RAMIS staff or tax agent authorisation record
- Section 126(5) preparer certification for each return
- Payment receipts and RAMIS acknowledgements for each filing
- Books, source documents and bank statements kept at your place of business
FAQ
Do I need a tax consultant to file my tax return in Sri Lanka?
No, the Act requires you to file, not to hire anyone. Section 93(1) puts the duty to file a return of income on every person, subject to the exceptions in section 94, and section 113(1B) requires returns to be filed electronically, with a senior citizen allowed to file on paper from the 2025/26 year of assessment under section 113(1D). A consultant is a choice you make for time and accuracy.
Who can represent me before the Inland Revenue Department?
An authorised representative as defined in section 195: an individual you authorise in writing who is a CA Sri Lanka member, an attorney-at-law, your regular employee, a Chartered Institute of Taxation of Sri Lanka member, an approved registered auditor or someone the Commissioner-General specifies. A relative also qualifies for an individual, a director or the company secretary for a company, and a partner for a partnership.
Am I liable if my tax consultant makes a mistake?
Yes, as far as the IRD is concerned. You or your agent sign the return under section 126(4), the return is treated as filed with your authority under sections 128 and 131, and penalty notices go to the person liable under section 176(6). Any recovery from the consultant depends on your engagement terms, on our reading.
How long must a business keep tax records in Sri Lanka?
At least five years from the date of each transaction, under section 120(6)(a). Where the time limit for assessment or any related proceedings runs longer, the records must be kept until those end, under section 120(6)(b). The records stay at your place of business unless the Commissioner-General approves another place, under section 120(4).
Can my tax consultant appear for me at the Tax Appeals Commission?
Yes, if they are your authorized representative. Section 9(3) of the Tax Appeals Commission Act, No. 23 of 2011 says every appellant "shall attend in person or by an authorized representative", and even with your representative present, the Commission may postpone a hearing so you attend in person. That Act does not define the term, so on our reading choose someone on the section 195 list.
Talk to us. If you want your returns prepared and filed on RAMIS on a set calendar, with IRD correspondence handled, see our income tax advisory services. Our fees are on the pricing page.
WinCore Pvt Ltd
This page reflects the Acts as read on 26 October 2026. It is general information, not advice on your situation.
Sources and references (9)
- Inland Revenue Department. Inland Revenue Act, No. 24 of 2017, consolidated text (amendments up to 31 March 2025), ss.86, 87, 93, 100, 102, 113, 115, 120, 126, 128, 131, 136, 139, 142, 143, 146, 157, 159, 176 to 181, 187, 190, 190A, 195; First Schedule para 10. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IRA_Cons_Act_-_2025_Changes.pdf . Primary (IRD consolidation, not the certified text). Accessed 26 October 2026.
- Inland Revenue (Amendment) Act, No. 11 of 2026 (certified 3 June 2026), ss.1, 25 and 33. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No_11-2026_E.pdf . Primary. Accessed 26 October 2026.
- Inland Revenue (Amendment) Act, No. 10 of 2021 (certified 13 May 2021), s.40. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No._10_2021_E.pdf . Primary. Accessed 26 October 2026.
- Inland Revenue (Amendment) Act, No. 45 of 2022 (certified 19 December 2022), s.27. https://www.ird.gov.lk/en/publications/Acts_Income%20Tax_2017/IR_Act_No._45_2022_E.pdf . Primary. Accessed 26 October 2026.
- Inland Revenue Department. Access to e-Services, Authorisation of Staff/Tax Agent and login profiles. https://www.ird.gov.lk/en/eServices/SitePages/Access%20To%20e-Services.aspx?menuid=1803 . Primary (IRD guidance). Accessed 26 October 2026.
- Tax Appeals Commission Act, No. 23 of 2011 (certified 31 March 2011), s.9(3), read with the Tax Appeals Commission (Amendment) Acts No. 4 of 2012 and No. 20 of 2013, which amend other parts of s.9. https://www.ird.gov.lk/en/publications/Acts_Tax%20Appeals%20Commission/Act%20No.%2023%5BE%5D2011.pdf . Primary. Accessed 26 October 2026.
- CA Sri Lanka. Practicing Members List. https://www.casrilanka.com/casl/index.php?option=com_content&view=article&id=4310&Itemid=605&lang=en . Primary (the body's own site). Accessed 26 October 2026.
- Daily FT. Chartered Institute of Taxation of Sri Lanka urges Govt. to legally recognise profession of "Tax Consultant" (29 May 2024). https://www.ft.lk/Business/Chartered-Institute-of-Taxation-of-Sri-Lanka-urges-Govt-to-legally-recognise-profession-of-Tax-Consultant/34-762276 . Secondary. Accessed 26 October 2026.
- Inland Revenue Department. Value Added Tax Act, No. 14 of 2002, consolidated text (amendments up to 31 December 2025), ss.21(1) and 26(1), definition of "taxable period"; read with the Value Added Tax (Amendment) Act, No. 14 of 2026, s.5. https://www.ird.gov.lk/en/publications/Value%20Added%20Tax_Acts/VAT_Act_No_14%5BE%5D_2002_%28Consolidation_2025%29.pdf . Primary (IRD consolidation). Accessed 26 October 2026.
Put these insights to work
WinCore specialists can review your current workflow, document gaps, and build a practical 90-day action plan.
Book a free consultationRecent articles
Continue reading
Explore more WinCore analysis to keep your finance, tax, and compliance roadmap moving.
A practical RAMIS filing checklist for Sri Lankan businesses covering account access, return preparation, submission order, and deadline control.
RAMIS penalty guide for Sri Lanka with the legal rules for late filing, late payment, interest and incorrect returns, plus practical prevention controls.
Step-by-step guide to filing income tax returns in Sri Lanka: deadlines, RAMIS process, relief, bands, WHT credits, and common penalty traps.